The RiskSpan difference — why Portfolio Managers and Traders choose our platform
RiskSpan wins because we price assets the way investors need them priced — at the loan level, with proprietary models and a data moat that no one else has built at this depth or breadth.
- Loan-level pricing, not pool-level approximations
- Proprietary regression models built on decades of loan performance data — prepayment, default, loss severity
- Covers public ABS and private ABF in a single, integrated platform
- Modern point-of-purchase analysis is compute-intensive — only RiskSpan's data and infrastructure engineering runs it at scale
- Structured finance is shifting from security-level to loan-level analytics
- Real estate and resi is local — granularity is essential to price, trade, and manage risk
- Regulatory pressure, private credit growth, and bank retrenchment are accelerating demand for loan-level infrastructure
- Loan-level surveillance detects performance deterioration before it aggregates to deal level
- Early risk signals enable proactive portfolio rebalancing, not reactive damage control
- RiskSpan is the only platform built from the ground up for this level of collateral visibility
Make trading decisions and execute investment analysis.
Who Buys
What They Use
- Loan-level pricing and cash flow analytics
- AI tape cracking and collateral analysis
- Private ABF deal modeling
- Scenario stress across rates and credit
- Proprietary prepay and credit models
Monitor portfolio risk and manage exposure.
Who Buys
What They Use
- Real-time risk analytics (OAS, DV01, VaR)
- Automated surveillance and watchlist alerts
- Credit risk and anomaly detection
- Automated batch risk delivery and data services
- Performance attribution and reporting
Model assets for ALM and stress-test performance across scenarios.
Who Buys
What They Use
- Asset modeling for ALM
- CECL modeling and scenario analysis
- Regulatory analytics (NAIC RBC C3)
- Cross-manager exposure aggregation
- Look-through loan and collateral analysis
- Manager comparison and concentration detection
Residential Behavioral Models.
Proprietary prepayment and credit models spanning agency (Fannie Mae, Freddie Mac, Ginnie Mae) and Non-QM collateral — built and regularly updated by our in-house modeling team, with interactive diagnostics for back-testing across any custom segmentation.
Complexity Other Vendors Simplify Away
Off-the-shelf roll-rate models and single-curve prepay assumptions break down on complex collateral. Ours don't — which is why teams who've evaluated other vendors keep coming back to RiskSpan.
Breadth of Coverage, Depth of Attributes
Proprietary prepayment and credit models covering the full spectrum of residential mortgage behavior — built and maintained in-house, validated on an ongoing basis.
- Prepayment & Default Models Turnover, refinance, and default curves calibrated across agency, non-agency, and private-label collateral.
- Custom Segmentation Slice model output by FICO, LTV, loan purpose, geography, servicer, or any custom cohort you define.
- Regularly Refreshed Models are re-estimated on a recurring cadence by our in-house quant team as new performance data arrives.
- Built for Every Workflow Same model output feeds pricing, portfolio management, CECL, and surveillance — no re-keying.
| Collateral Type | Credit Model | Prepayment Model |
|---|---|---|
| AgencyFannie Mae · Freddie Mac · Ginnie Mae | ✓ | ✓ |
| Agency-Eligible Jumbo | — | ✓ |
| Agency-Eligible Investor | — | ✓ |
| Non-QMBank Statement · DSCR · Full Doc · Other | ✓ | ✓ |
Agency, Jumbo & Investor Coverage
A multi-state credit transition model for agency collateral, paired with a turnover-and-refinance prepayment engine that extends coverage across agency, agency-eligible jumbo, and agency-eligible investor loans.
- Multi-State Credit Transition Model A 13-state Markov transition model — Current through REO — for Fannie Mae, Freddie Mac, and Ginnie Mae collateral, paired with a Weibull-based liquidation timing model and a loss-severity model.
- Prepayment Coverage Beyond Agency Turnover-and-refinance S-curve prepayment models extend to agency-eligible jumbo and agency-eligible investor collateral — each calibrated with its own turnover, refinance, and burnout behavior, not proxied from conforming agency pools.
- Built on GSE Loan-Level Data Trained on Fannie Mae, Freddie Mac, and Ginnie Mae loan-level performance data — the COVID forbearance period is explicitly excluded from training to avoid distorting transition and prepayment behavior.
- Feeds the MSR Engine Credit Model output maps directly into 18 MSR components — servicing fee, escrow float income, corporate advances, foreclosure/REO cost, and more.
A 13-state Markov transition model for agency collateral — Current through REO — paired with Weibull-based liquidation timing and a dedicated loss-severity model.
Classic turnover-and-refinance S-curve decomposition covering agency, agency-eligible jumbo, and agency-eligible investor collateral, with burnout tracking built in.
Spotlight on Non-QM
A full transition-state model, estimated independently by doc type — Bank Statement, DSCR, Full Doc, and Other — replacing a simplified roll-rate approach with backtesting and tunability built in from day one.
- Granular States Delinquency tracked across 9+ states — Current (clean/dirty), 30/60/90/120/180+, FCL, REO — not a simplified 3-state roll rate. Distinguishes "always current" from loans with delinquency history, which many competitors don't.
- Doc-Type Native Separate models for Bank Statement, DSCR, Full Doc, and Other — fit on ~$87B / 226K loans of Non-QM data, not proxied from agency collateral.
- Backtesting Built In Compare projected transition rates against your portfolio's actuals directly in-platform — S-curve, aging, and factor-date views.
- Tunable to Your View Blend projections with your house view, adjust transitions deal-by-deal, or supply your own transition matrix — disclosed assumptions and loan-level dials for every deal.
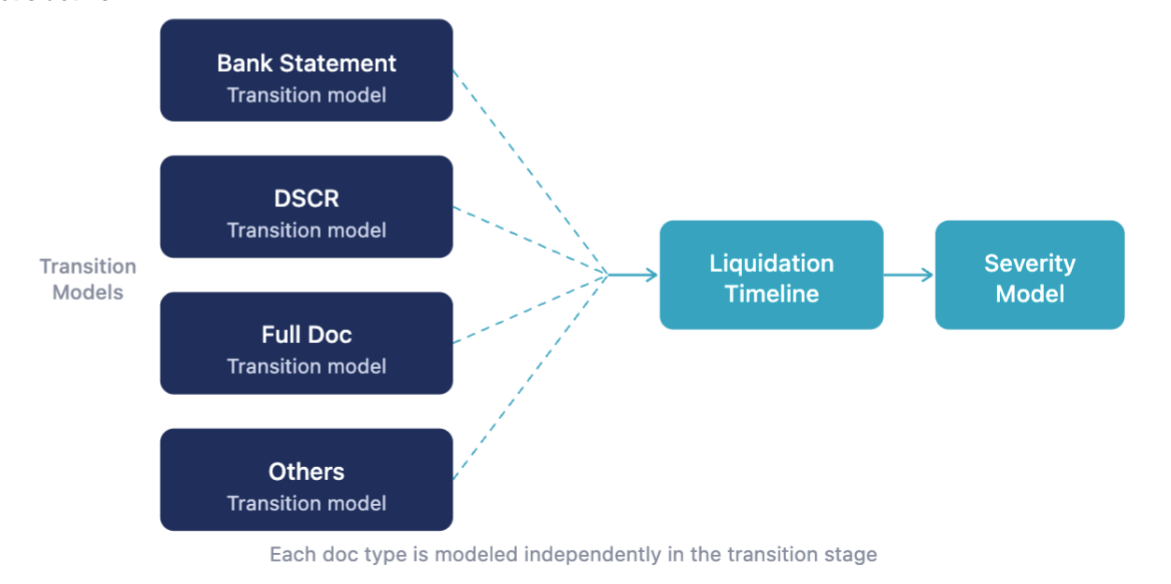
Each delinquency transition — Current through REO — estimated independently by doc type, with a calculation-based severity option alongside the statistical approach.
Bank Statement, DSCR, Full Doc, and Other doc types each get their own S-curve, anchored to PMMS incentive and coupled with the Credit Model on a shared monthly state clock.
Tunable Knobs, Purpose-Built Presets
Every model exposes disclosed, adjustable overrides on the RiskSpan Platform — start from a validated baseline, then tune to your own view without touching the underlying model.
- Credit Model Knobs Liquidation timing override, severity floor, pipeline cure-rate multiplier, and separate roll-rate and loss-severity multipliers — all adjustable per deal.
- Prepayment Model Knobs Independent multipliers on turnover, refinancing, and burnout, plus an S-curve elbow shift and aging/seasoning ramp — tune behavior without re-fitting the model.
- 20+ Collateral-Type Presets Named presets — Legacy Prime, Alt-A, Subprime, Agency, Option ARM, HELOC, Second Lien, Scratch & Dent, and more — each bundling a credit knob set, prepay knob set, and severity multiplier calibrated to that collateral type.
- No Black Box Every override, multiplier, and preset is disclosed and documented — nothing is buried in an opaque model file.
Disclosed overrides on liquidation timing, severity, turnover, refinancing, and burnout, plus 20+ named collateral-type presets to start from a validated baseline.
Compare projected vs. actual performance at the loan or cohort level, with drill-down diagnostics for any segmentation.
Build ad-hoc cohorts by FICO, LTV, geography, servicer, or vintage to stress-test model behavior before you rely on it.
RiskSpan's modeling team re-estimates and revalidates behavioral models on an ongoing cadence — no stale assumptions.
Plug model output directly into pricing, CECL, ALM, and surveillance workflows via API, data feed, or dashboard.
Why RiskSpan, Not a Single-Purpose Model
Purpose-Built, Not Re-Tuned
RiskSpan's residential models span the full collateral spectrum — agency-grade credit and prepayment models re-estimated on Fannie Mae, Freddie Mac, and Ginnie Mae data, plus a purpose-built Non-QM model fit on $87B of UPB and 226K loans. Every model exposes disclosed, tunable knobs and runs inside the same platform as tape cracking and cashflow analytics — no black box, no handoff.
Real Quantitative Research
That tunability reflects years of dedicated quantitative research — built to evolve with the market, not just accurate in a backtest. Use it as your primary model or an independent benchmark; the knobs are disclosed and documented, so your team always knows what it's saying and why.
Built to Keep Pace
Pick the model you'll still be running three or five years from now, not the one built to solve a problem the market already moved past. RiskSpan's residential models are re-estimated on a recurring cadence and extended to new collateral types as they emerge — they're built to keep pace with the market, not to be replaced by the next vendor who catches up.
Pre-Trade & Pricing Analytics.
Investment and risk management signals — in your hands sooner, without the grunt work. Ingest, analyze, and act on collateral data before execution.
Tape to Deal-Ready Insight. No Handoffs.
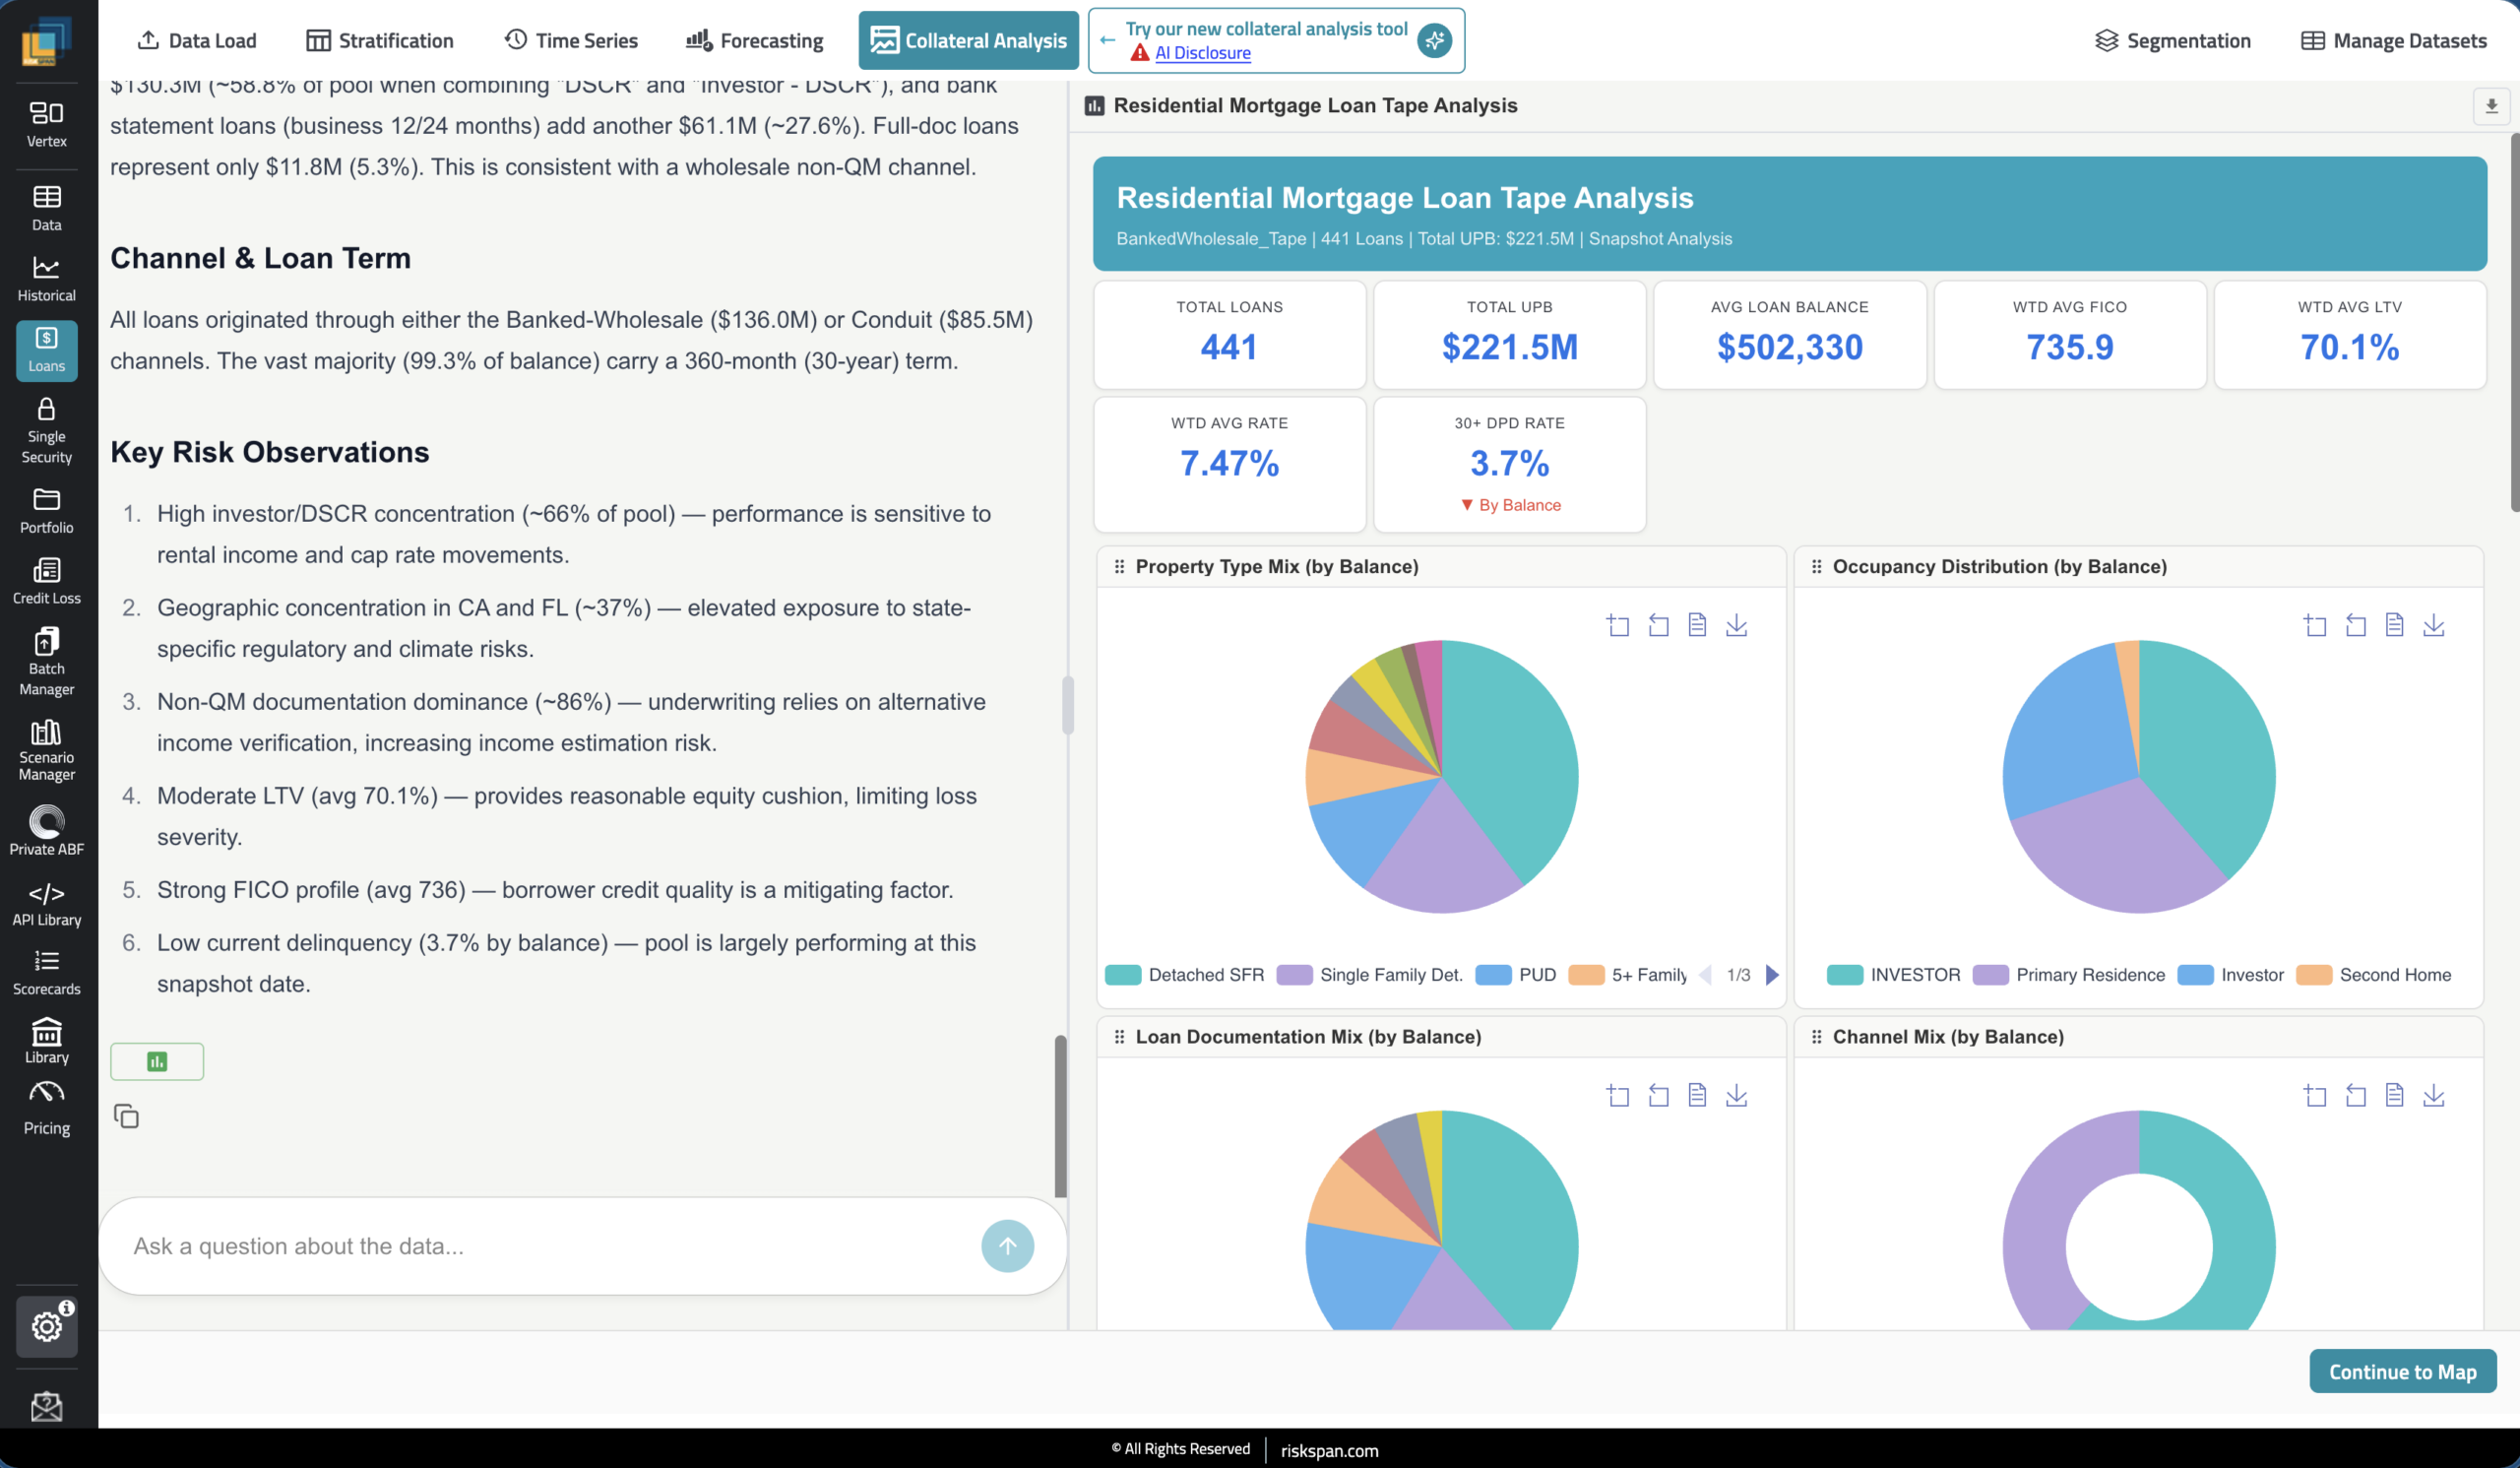
Upload any tape and get an institutional-grade collateral analysis in minutes — then push straight through to pricing and cash flows without leaving the platform.
- AI Tape Cracking & Auto-Mapping Ingests any file, any layout, any servicer. Proposes a complete field mapping in seconds, grounded in RiskSpan's data dictionary — no manual prep required.
- Collateral Summary Before You Commit Loan-level risk observations, property/occupancy/channel mix breakdowns, and concentration flags — before spending analyst hours on a deal that won't close.
- From Tape to Pricing in One Flow Map, QC, and run scenario cash flows in the same platform. No tool-switching, no re-keying data between systems.
- Transparent QC Field-impact visibility shows which fields feed which models. QC failures are actionable with a single click — no support tickets, no black box.
Private ABF Waterfall Cash Flow Modeling
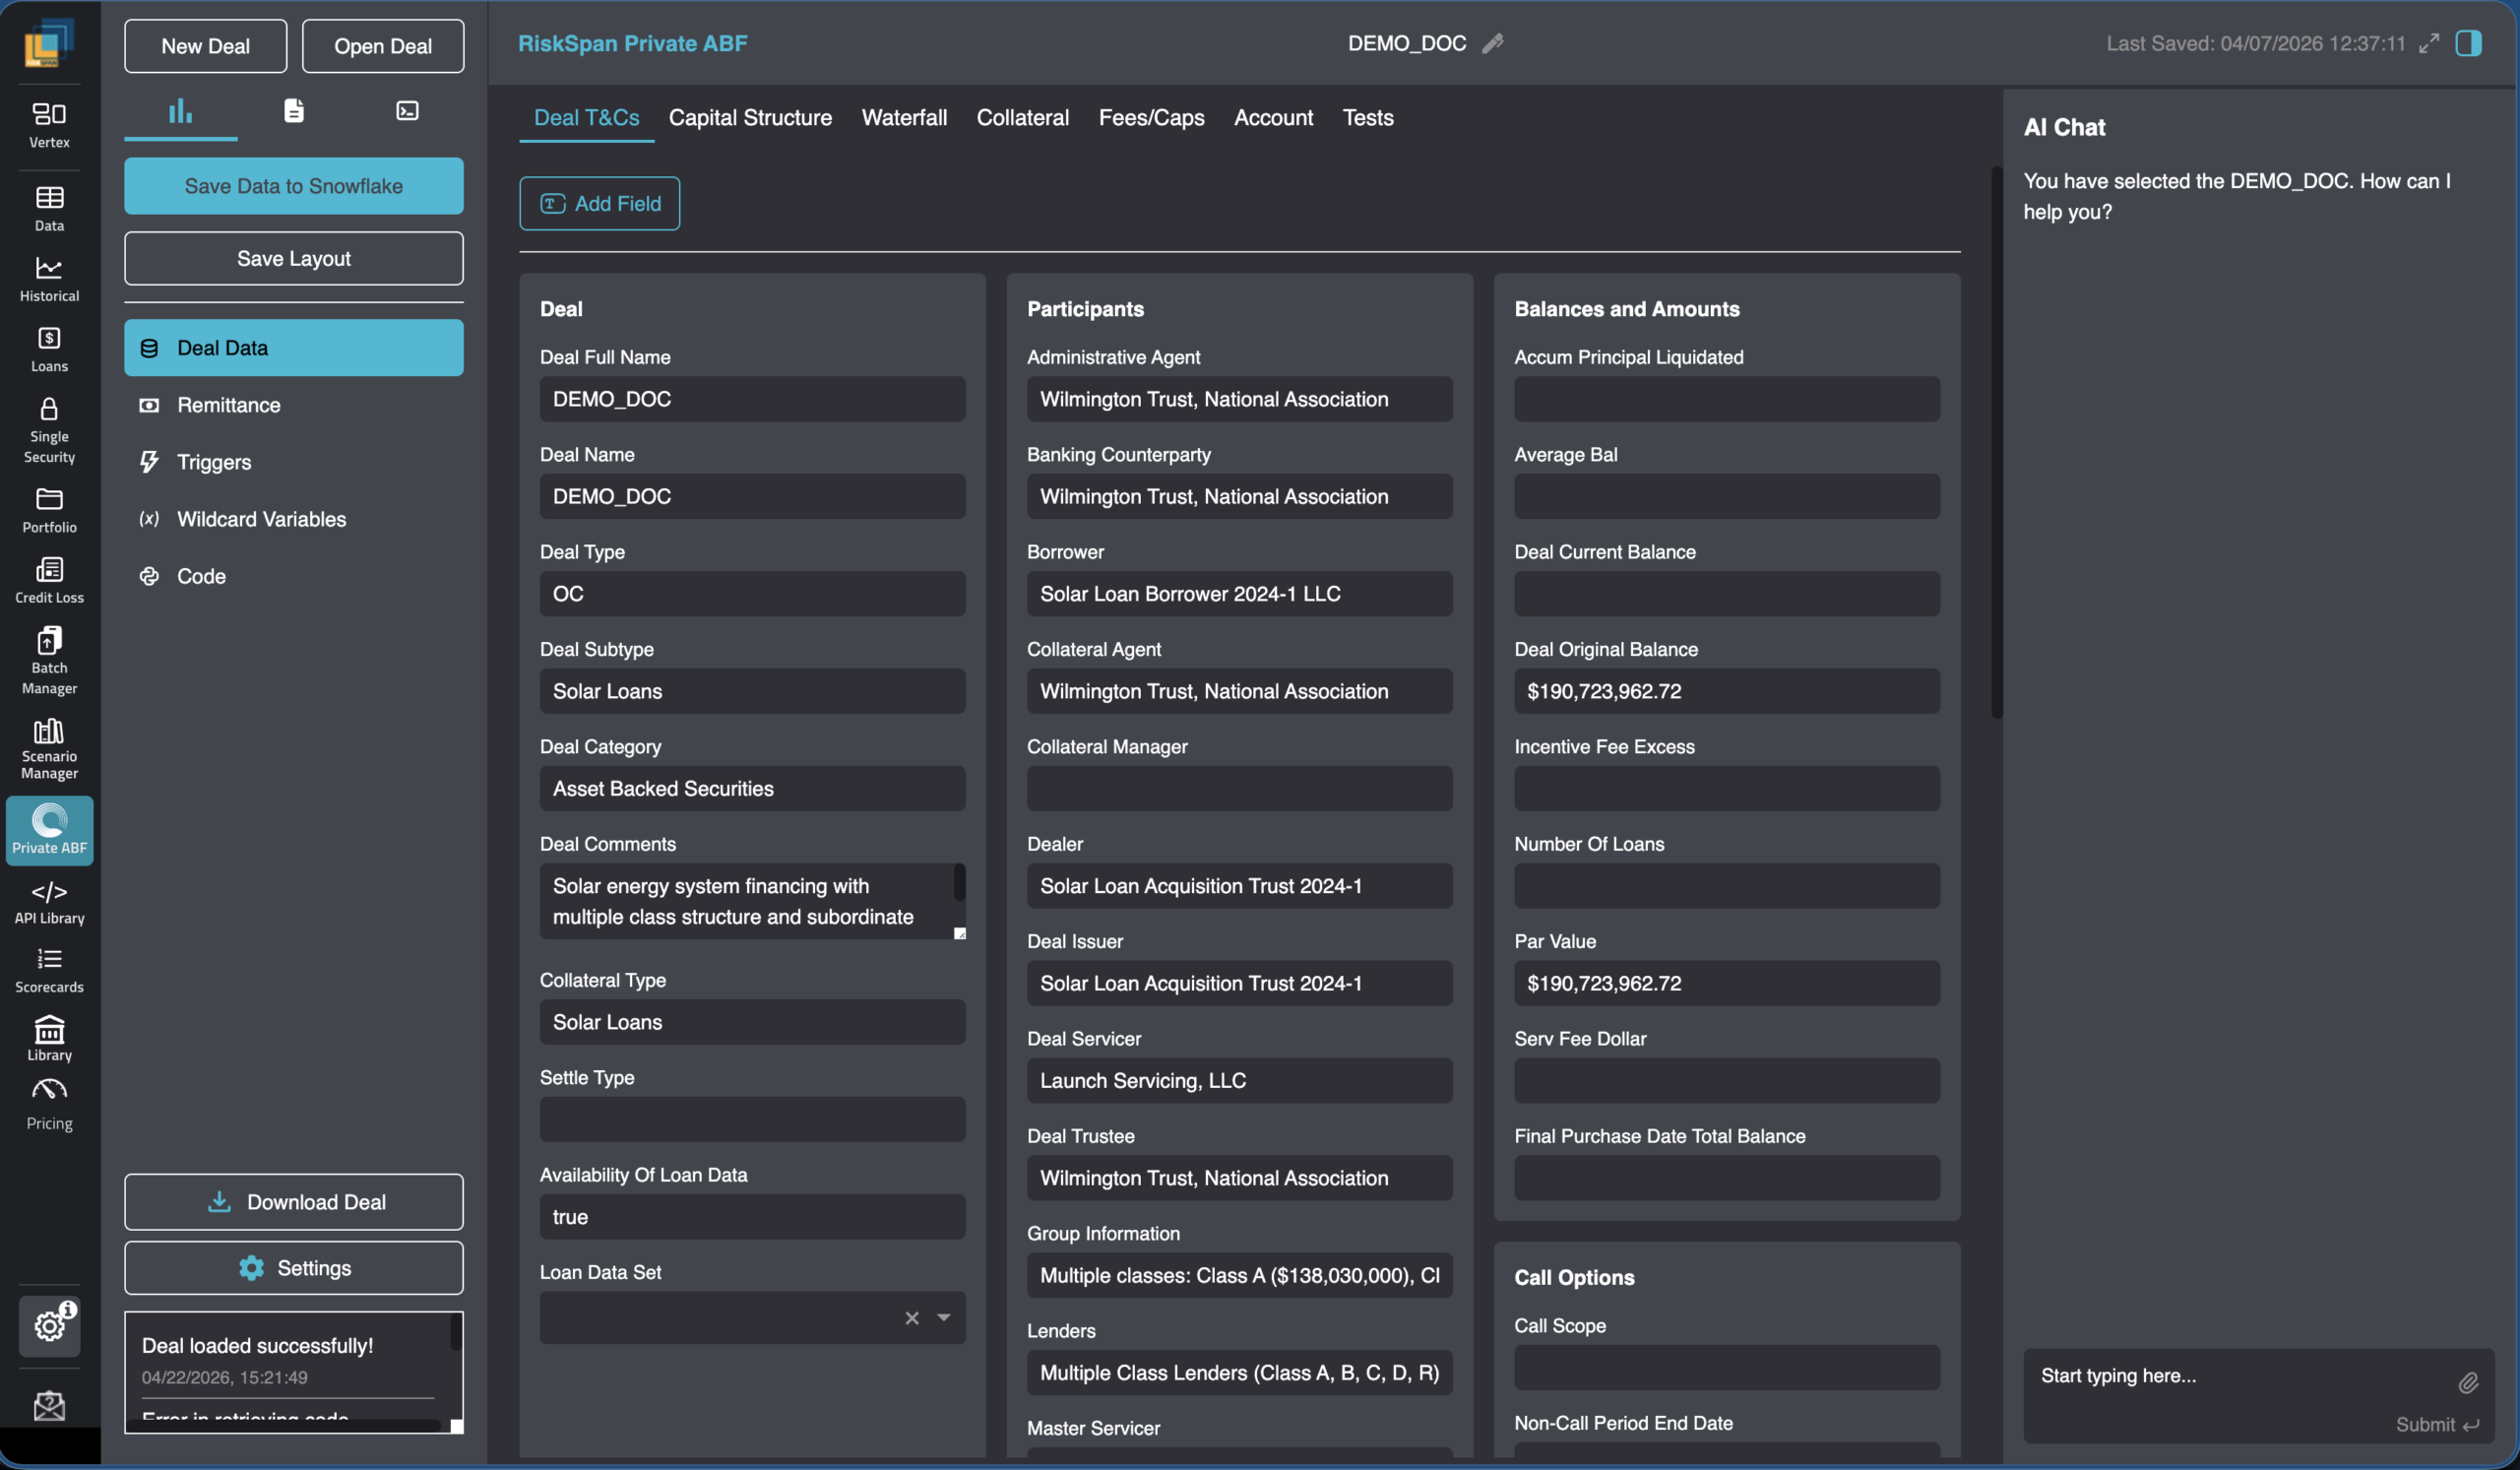
From deal document to live surveillance — model bespoke private ABF structures in hours, not weeks.
- AI-Assisted Deal Ingestion Extract waterfall logic, triggers, covenants, fees, and borrowing bases directly from the deal document.
- Structured Deal Workspace Deal T&Cs, capital structure, waterfall, collateral, fees/caps, account and tests — organized in one workspace.
- Resi, Consumer, Commercial & Bespoke Built for flexibility — model solar loans, consumer ABS, CRE, and other non-standard private ABF structures.
- Integrated AI Chat Ask questions about the deal, balances, and participants — the agent answers grounded in the loaded deal data.
Single Security Analytics
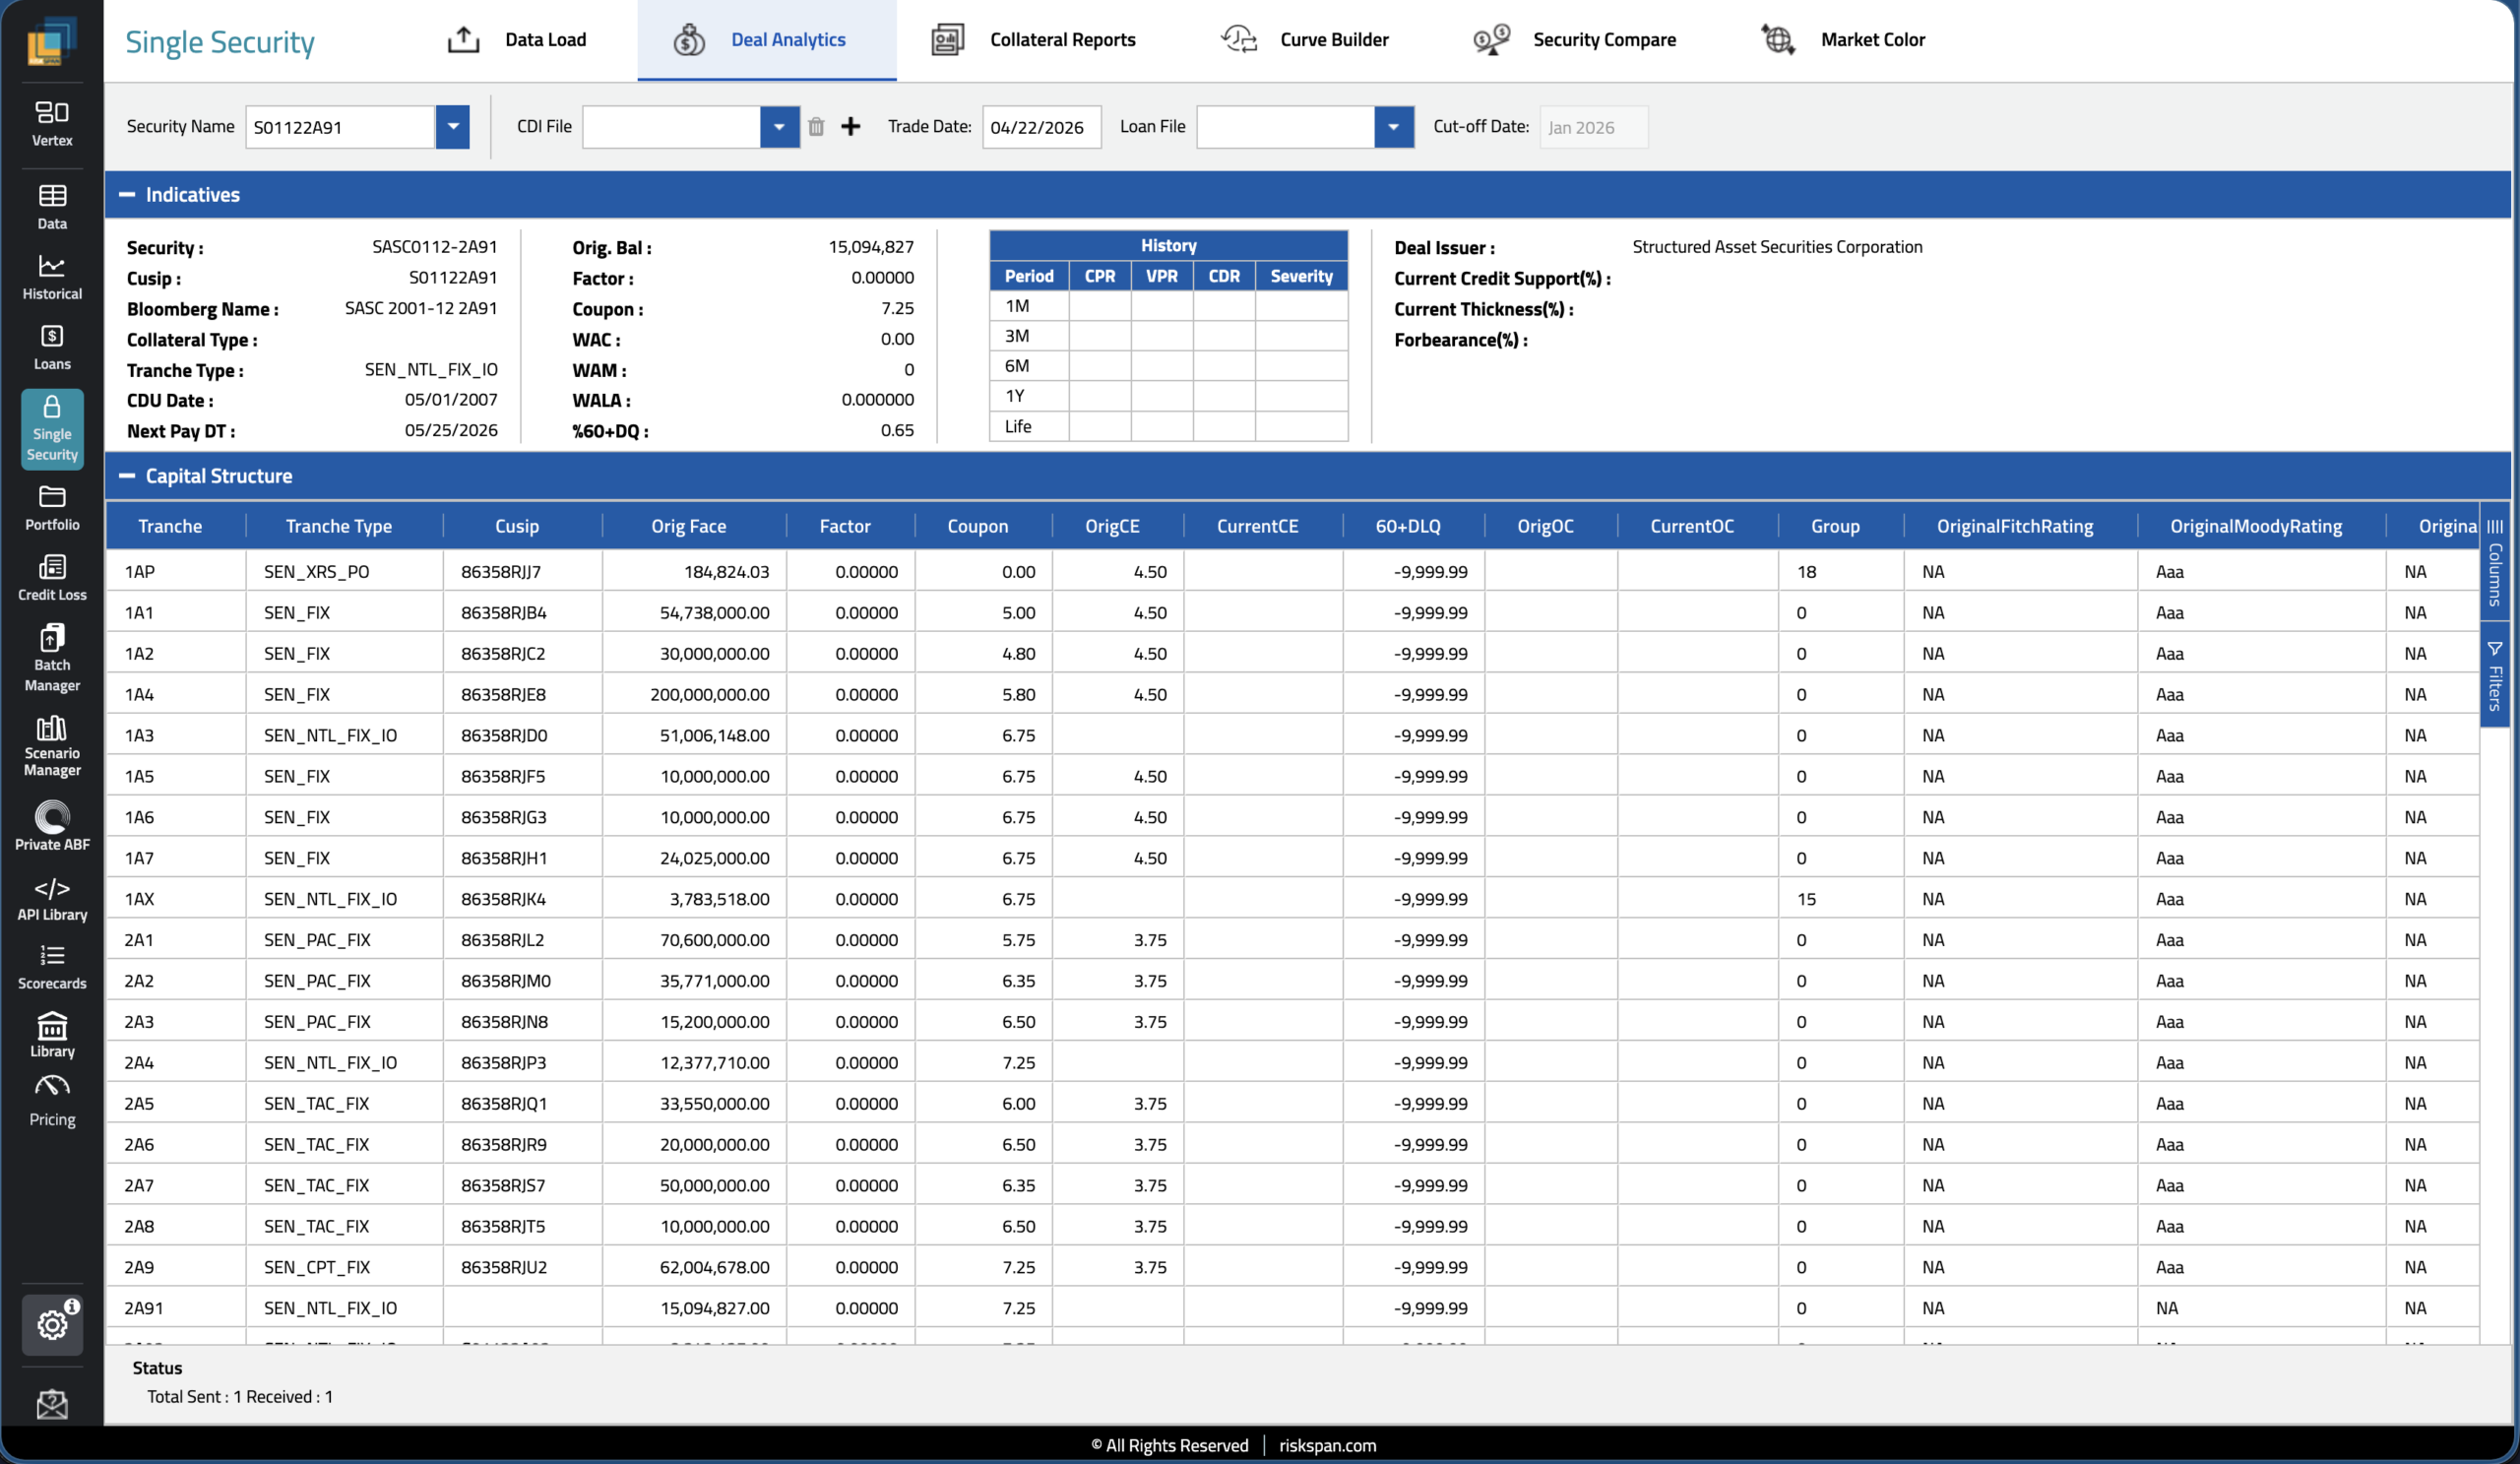
Deep dive into any agency or non-agency security — indicatives, cash flows, capital structure, and pricing.
- Complete Security Indicatives CUSIP, Bloomberg Name, Coupon, WAC, WAM, CPR/VPR/CDR history, credit support, and factors — all in one view.
- Full Capital Structure See every tranche, rating, original and current balance, coupon, and credit enhancement in a single grid.
- Deal Analytics & Cash Flows Run scenario cash flows, price at any date, and stress across rates and credit — at the bond or tranche level.
- Collateral, Reports & Compare Jump from a single security to underlying collateral, curve builder, and side-by-side security comparisons.
Query loan-level RMBS performance data going back to before the Financial Crisis — rank cohorts and benchmark shelves before deals arrive.
Compare credit support and collateral quality against benchmarks — with geographic maps, FICO-LTV scatterplots, and export-ready visuals.
Run proprietary loan-level models across multiple scenarios to identify relative value and mispriced bonds — with full Intex deal coverage.
Ingest tapes from any counterparty in any format — ML maps fields automatically, flags exceptions, and generates a full audit report.
Model cash flows for any loan type or esoteric structure — with real-time scenario analysis and a Curve Builder weighted by cohort performance and loan age.
View recent transaction prices for comparable bonds to triangulate market valuations and price with confidence.
Portfolio Analytics.
A fully-managed, end-to-end solution for loan and structured finance portfolio analytics — built for speed, precision, and scale across 70+ asset classes.
Cohesive, Multi-Asset Class Portfolio Analytics
One screen to price, stress, and report on the entire book — down to the loan, up to the portfolio.
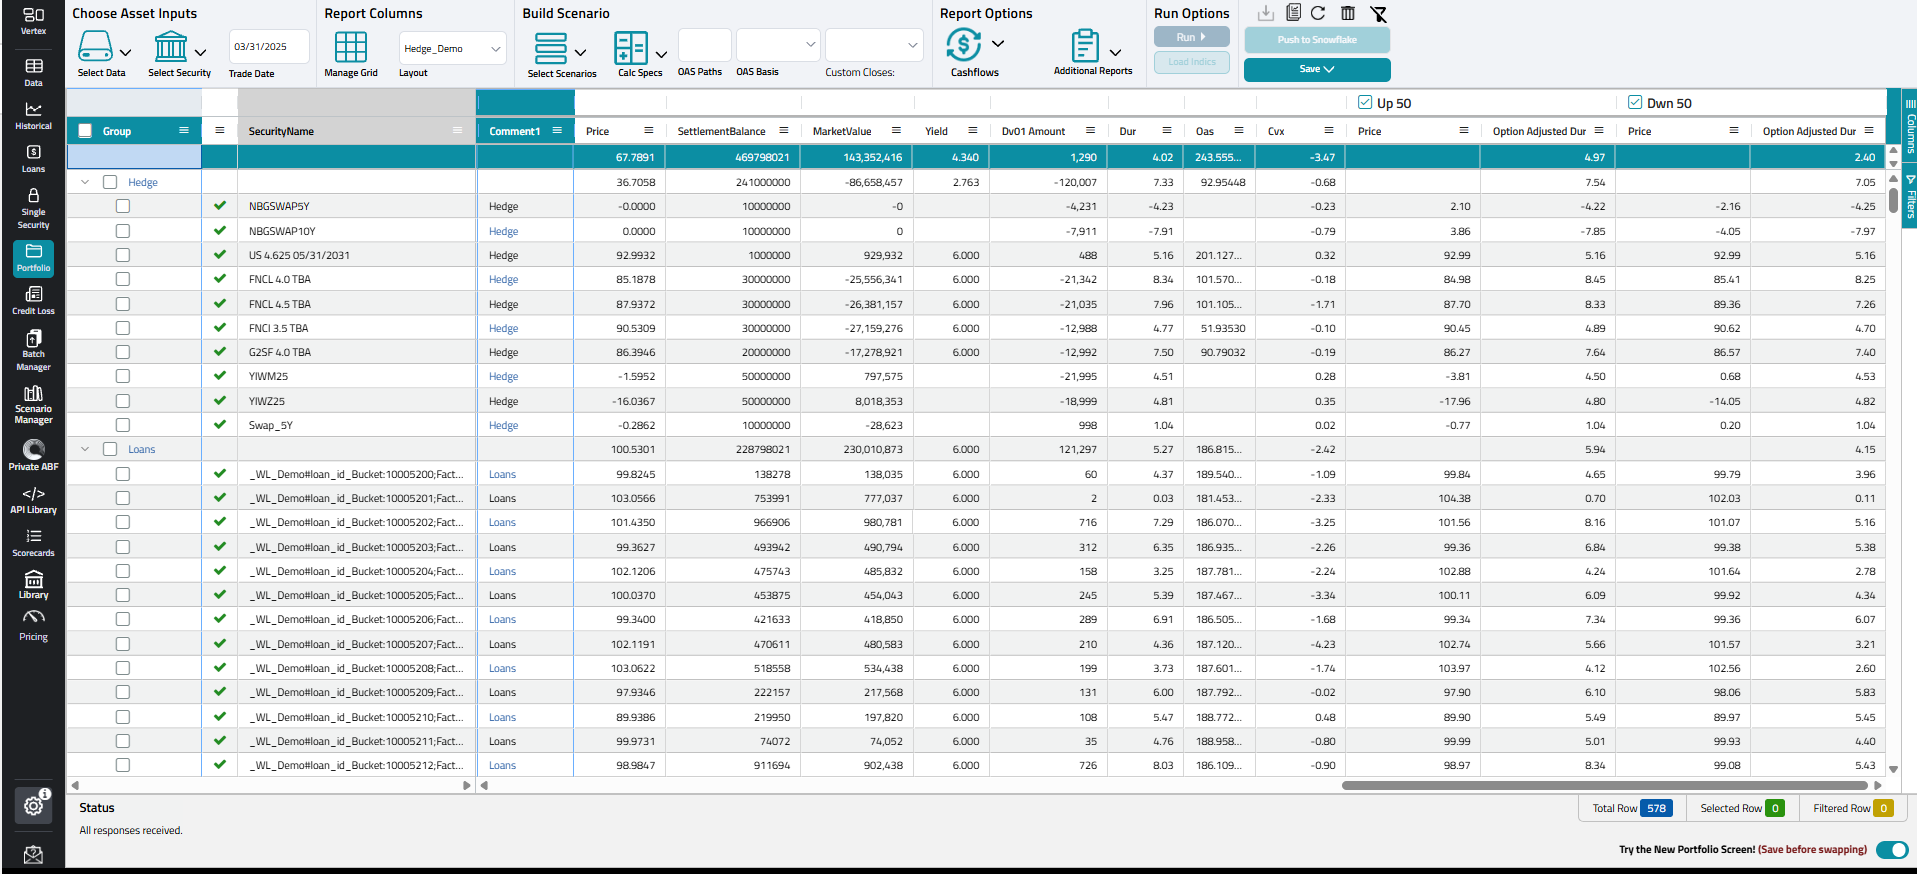
- Flexible Asset Inputs Mix whole loans, MSRs, public securities, and private ABF deals in a single portfolio view.
- Configurable Report Columns Choose scenarios, cash flow columns, OAS/DV01 and other analytics with the ability to save layouts per workflow.
- Scenario-Driven Runs Build or select a scenario once, run it across the full portfolio, and deliver via the Platform UI, Snowflake, or FTP.
- Run Options at Scale Trigger ad-hoc or scheduled batch jobs with audit trails — no servers, no IT queue.
Private ABF Portfolio & Deal Surveillance Dashboards
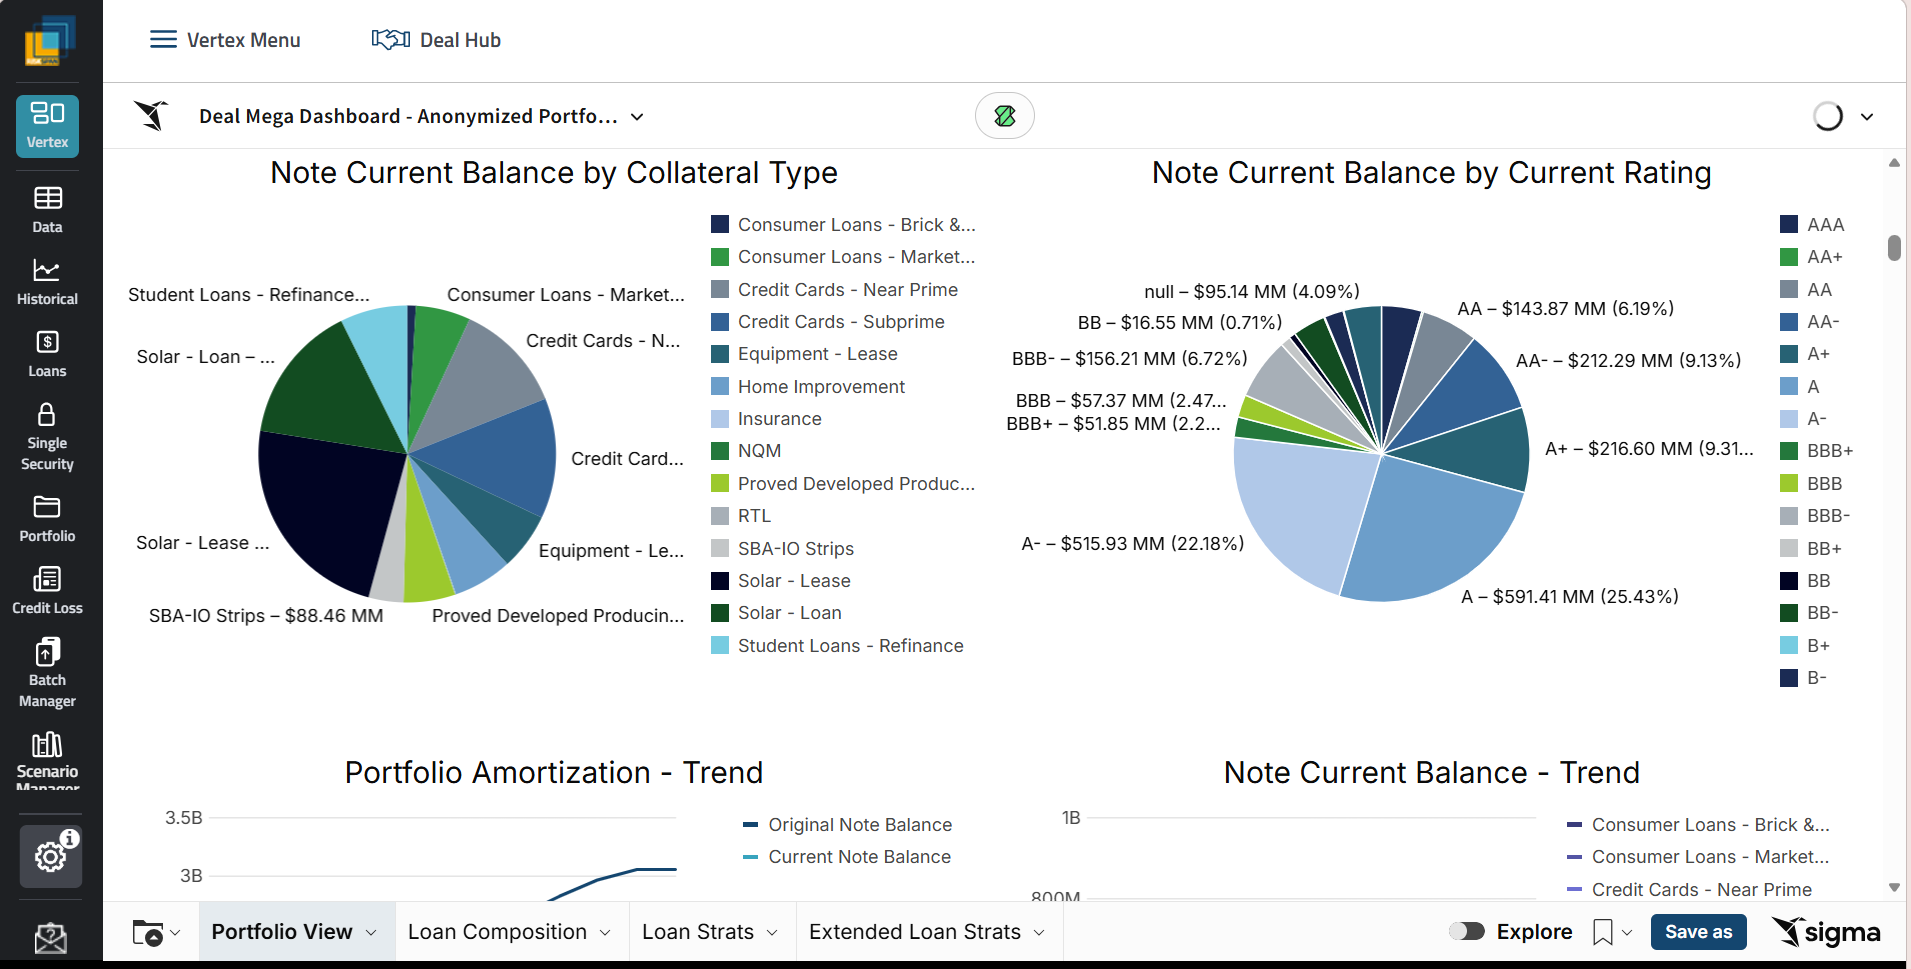
Monitor your entire ABF book and drill into any individual deal — with live data, flexible filters, and analyst-ready views in one integrated platform.
- Portfolio Views & Filters See every sector and collateral type at a glance with live loan counts and balances, and filter by investor, sector, collateral type, or reporting window to isolate the segment you need.
- Multiple Analytical Perspectives Toggle between Portfolio View, Loan Composition, Loan Strats, and Roll Rates to analyze the book from every angle.
- Deal Snapshot & Key Terms Access total balance, closing date, collateral type, country of risk, and the full counterparty roster — seller, borrower, sponsor, backup servicer, and more — in a single deal-level summary.
- Performance & Trigger Monitoring Track collateral and deal performance over time with source attribution, plus automated default and amortization trigger status across reporting periods.
- Investor Holdings & Analyst Commentary Review investor positions and analyst notes by date, with quick navigation to Capital Structure, Performance Charts, and Loan-Level Analysis.
Loan-level pricing and analytics across residential, auto, consumer, and private credit — with interactive queries, composition reports, and data export.
Trading-quality prepayment and credit models with OAS valuations, cohort CPR trends, and automated overnight runs via Snowflake.
Hosted pool and loan-level data for agency MBS, with loan-level pricing for private label securities under any market scenario.
Proprietary prepayment and credit models regularly updated by our in-house team — with interactive diagnostics for back-testing across custom segmentations.
Configurable dashboards tracking prepayment, default, and recapture — with automated investor reporting and direct data feed integration.
300M loans, 25,000+ instruments, 50B cash flow projections — delivered via API, data feed, or dashboard on AWS infrastructure.
Scenario Analytics & Reporting.
Stress test portfolios, model regulatory scenarios, and forecast credit losses across any market condition — with comprehensive, audit-ready output designed for compliance teams, validators, and examiners.
Scenario Library Assumptions
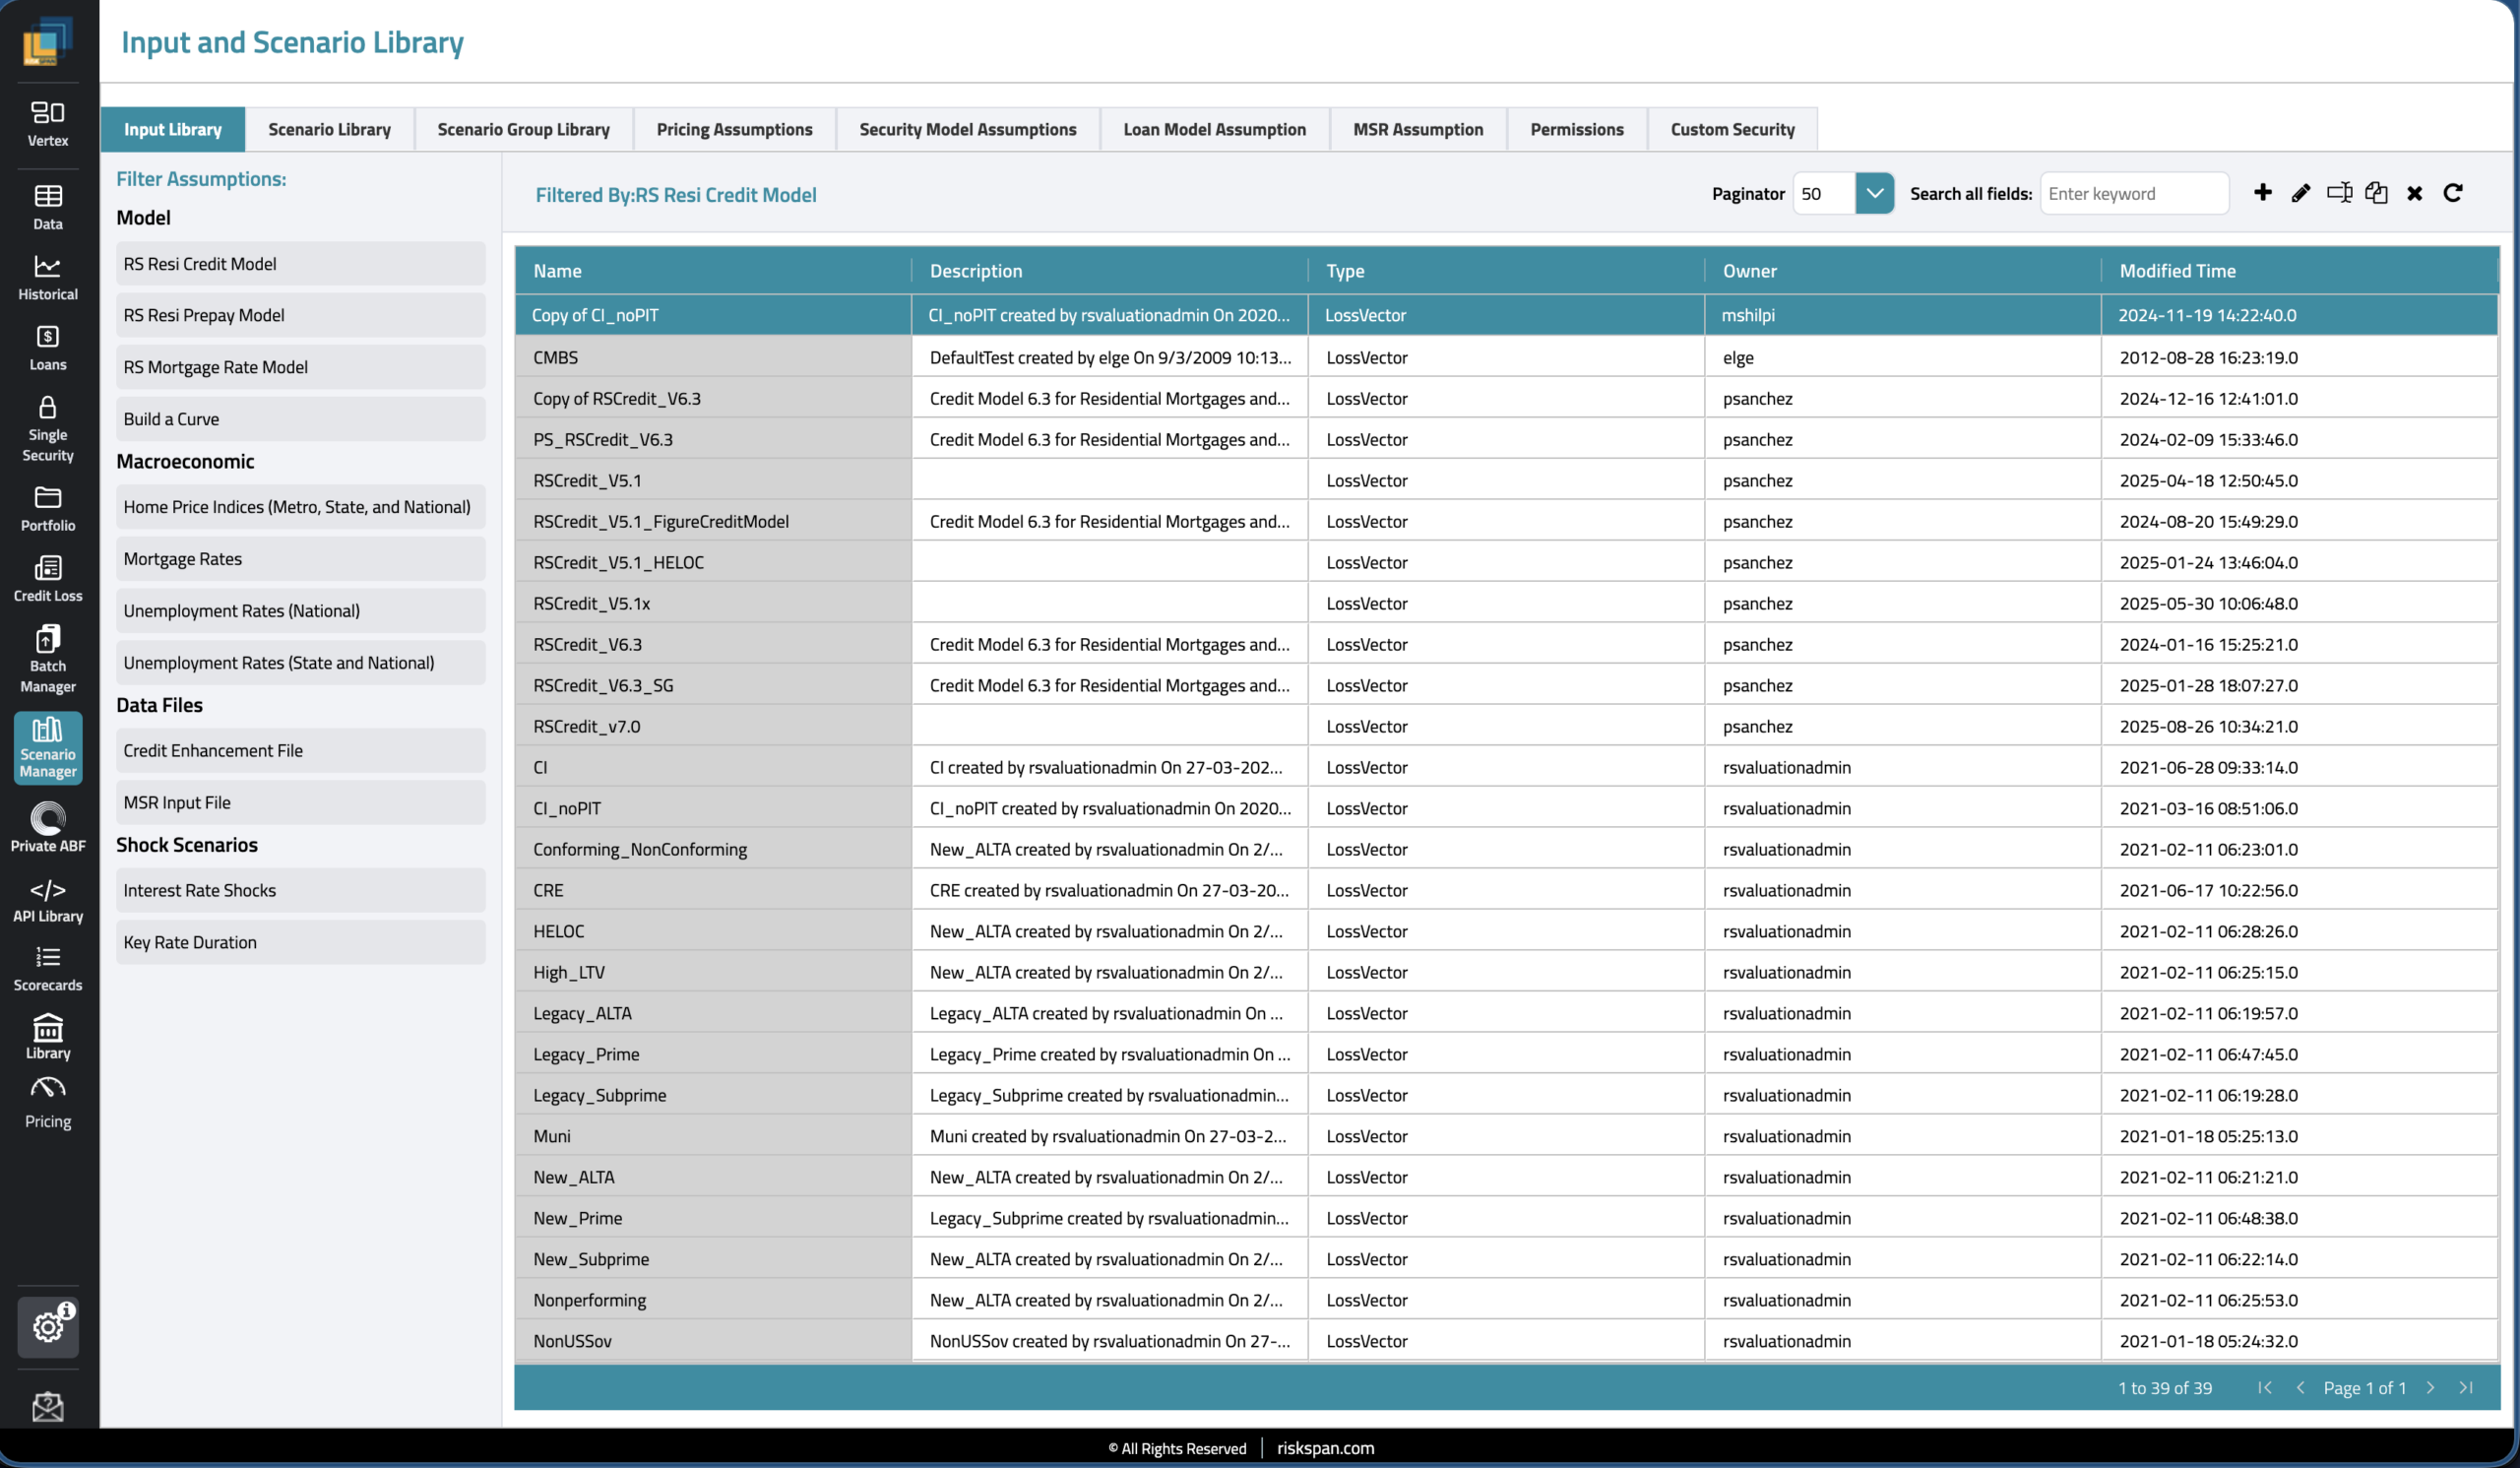
A governed library of models, scenarios, and assumptions — versioned, permissioned, and audit-ready.
- Centralized Model Repository Credit, prepay, rate shock, loan-model and MSR assumptions — all discoverable in one searchable library.
- Versioned & Auditable Every change is tracked with owner, modified time, and description — defensible for auditors and regulators.
- Shared or Private Scenarios Roll out firm-wide scenario groups or keep bespoke decks private to a desk or analyst.
- Ready for Batch & Ad-Hoc Plug any library entry into pricing, surveillance, CECL, ALM, and regulatory workflows — no re-keying.
Audit-ready credit loss accounting covering ASC 326-20 (CECL) and ASC 326-30/320-10 (OTTI) — SOC 1 & 2 certified, with a model support team on hand for examiners.
Custom macro scenarios with adjustable model inputs — delivering VaR, DV01, CS01, and key rate durations across 100+ instrument types at cloud speed.
Model validation reports that satisfy internal stakeholders and regulators — with a support team ready to respond to examiner questions.
ALM analytics, insurance capital modeling, and portfolio valuation — with on-demand performance data and the full structured products toolkit.
Cash flow forecasts translated into book entries per applicable accounting standards — Day 1 and Day 2 outputs with disclosures and an audit-ready package.
RiskSpan's modeling team builds and validates financial, forecasting, and ML models — delivering reports that satisfy both internal stakeholders and regulators.
Surveillance & Data Management.
Our platform and team of mortgage data experts handle your data warehousing, aggregation, validation, and normalization needs — so you can focus on your business. Reduce annual operating costs by over 30%.
Continuous Portfolio Surveillance
Validation and monitoring run at every stage of the data lifecycle — not just a query library, but ongoing surveillance that flags issues before they reach your models or your book.
- Automated Exception & QC Alerts Validation applied at every stage of the data lifecycle — from tape ingestion through daily servicing updates — with exceptions flagged and routed automatically.
- Delinquency & Trigger Tracking Monitor delinquency roll rates, covenant triggers, and performance thresholds across your portfolio continuously, not just at month-end close.
- Daily Portfolio Refresh Unified loan and MSR data sourced directly from originators and servicers and refreshed daily — surveillance runs against current data, not stale snapshots.
- Full Audit Trail Every validation, exception, and override is logged and traceable — defensible for internal risk teams, auditors, and examiners.
Historical Performance Data
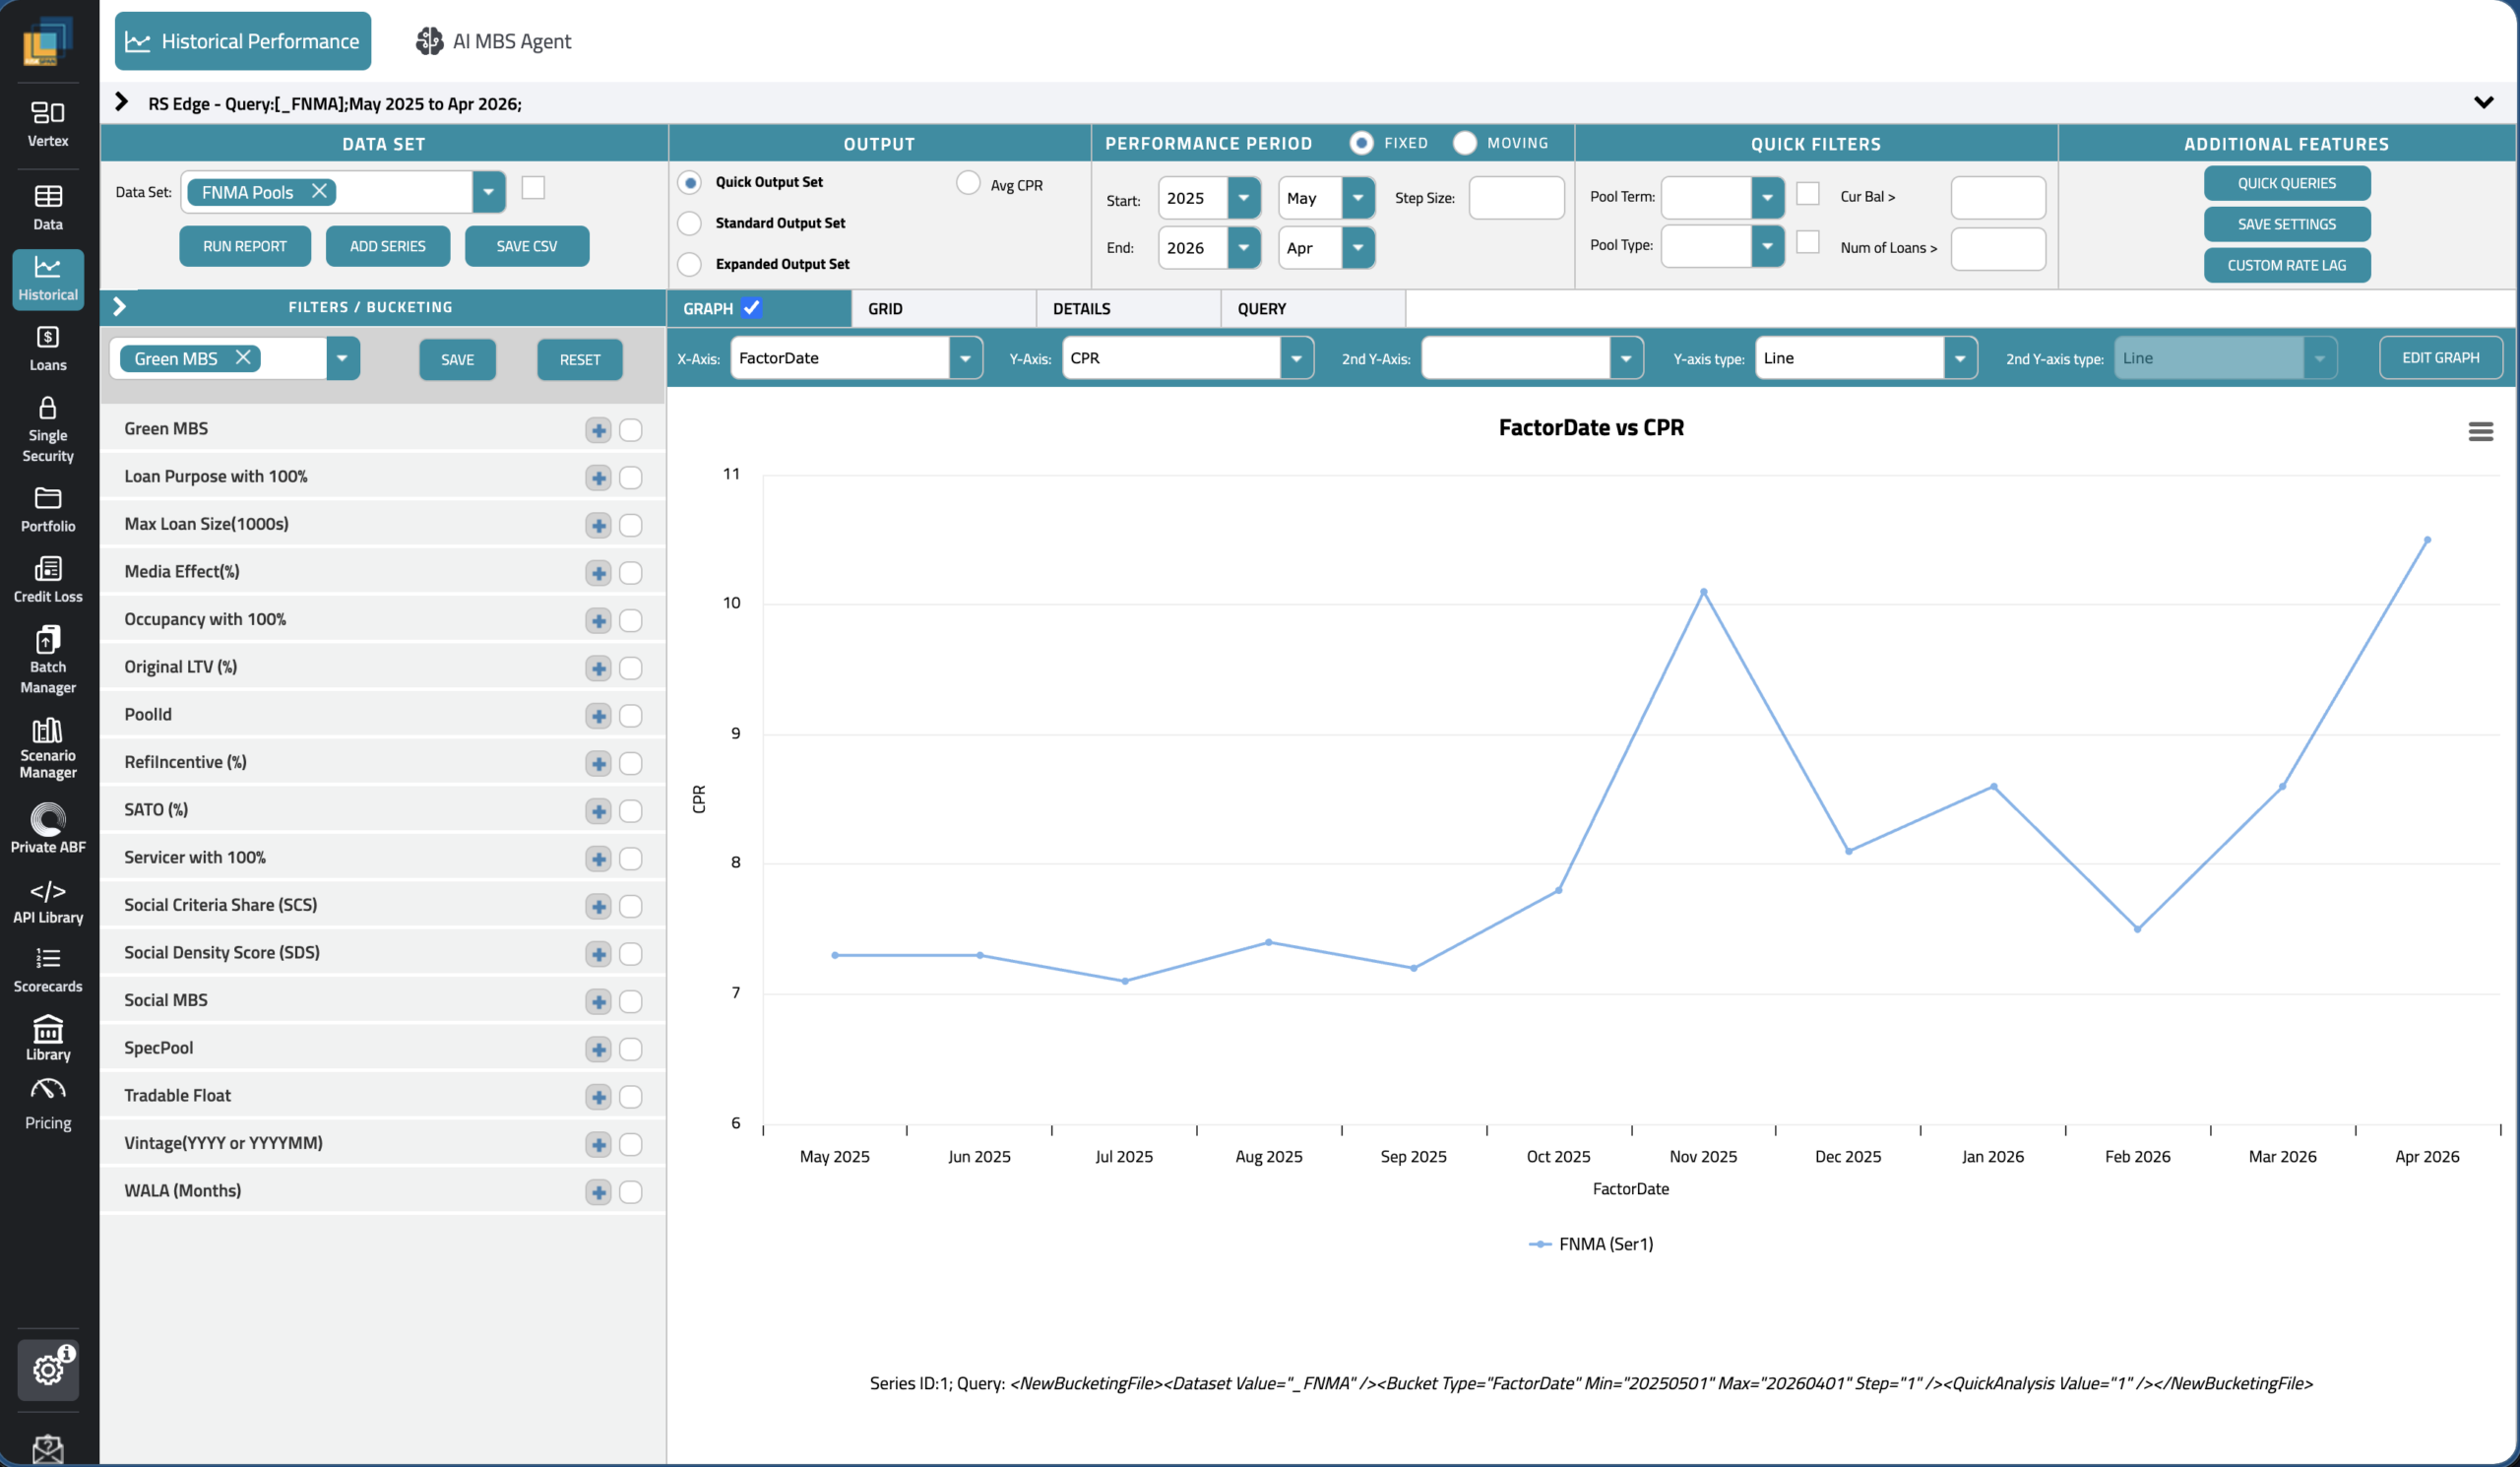
Decades of residential mortgage performance data — query any cohort, any factor, any time window.
- Any Pool, Any Layout, Any Servicer Run CPR, CDR, delinquency, and severity queries against FNMA, FHLMC, GNMA, Non-Agency and proprietary data sets.
- Flexible Bucketing & Filters Build custom cohorts on the fly — loan purpose, LTV, occupancy, SATO, refinancing, pool composition, and more.
- Graph, Grid & Query Views Toggle between chart, table, and raw query outputs; save, share, or schedule any report.
- Benchmark with Confidence The industry's most trusted Agency and Non-Agency performance library — the data behind RiskSpan's behavioral models.
Snowflake & Database Management
As a Snowflake Select Partner, RiskSpan connects, architects, and manages your data warehouse end-to-end — accurate, up-to-date, and accessible however your team works.
- Snowflake Select Partner RiskSpan connects your data sources directly to Snowflake, architecting and managing the warehouse so your team isn't stuck maintaining infrastructure.
- One Warehouse, Every Interface Query the same governed warehouse via the RiskSpan Platform, API, or Tableau — accurate and up-to-date, with no duplicate copies drifting out of sync.
- Full Data Lineage Every table traces back to its source system, so your team and your auditors can see exactly where a number came from.
- Scales With Your Portfolio From a single desk to an enterprise-wide deployment, the same warehouse architecture scales without a re-platform.
Select Partner
Data Processing & Aggregation
Daily unified loan and MSR data sourced directly from originators and servicers — RiskSpan's pipelines do the aggregation work so your team doesn't have to.
- Daily Portfolio Unification Unified loan and MSR data sourced directly from originators and servicers — replacing legacy systems and manual processes from day one.
- Scalable ETL Infrastructure Purpose-built pipelines for loan and securities data, with API-based edits, dynamic ingestion, and reporting as a service.
- Aggregation Across Counterparties Normalize and combine data from any originator, servicer, or custodian format into one consistent structure — no manual reconciliation.
- Data Science & ML Services From anomaly detection to loan performance prediction, RiskSpan's data scientists build custom ML solutions on top of your processed data.
AI-Powered ETL
SmartMapper: A Tape Workflow That Gets Better Every Time
Cut tape-cracking time by 40% with mapping that learns from every correction. Save datamaps, share across the team, and run loan-level analytics without leaving the platform.
- LLM-Powered Auto-Mapping SmartMapper draws on your prior datamaps and RiskSpan's data dictionary to propose a complete field mapping in seconds. Each suggestion is explainable.
- A Learning Loop That Compounds Every correction feeds back into the model — first-pass accuracy climbs toward ~90% over time, up from ~50% with manual methods.
- Reusable Datamap Library Save datamaps to a shared library. Apply across deals, share with the team, and manage field mappings as a reusable asset rather than starting from scratch each time.
- Transparent QC — No Black Box Field-impact visibility shows which fields feed which models. QC failures are actionable with a single click — no support tickets, no guesswork.
AI Embedded Across the RiskSpan Platform — Not Bolted on
RiskSpan builds AI directly into the same platform that cracks tapes, analyzes collateral, and prices cashflows — so issuers, investors, and servicers get AI-driven speed without stitching together outside tools. The toolkit below is growing; these are the capabilities live today.
Smart Mapper
AI-driven ETL that auto-maps loan tapes in any format on load — no manual column mapping.
Learn More →CAT (Collateral Analysis Tool)
Turns loan and bond collateral into decision-ready insight automatically.
Agentic AI for MBS Data
A natural-language agent that answers agency MBS questions in seconds, with the SQL to prove it.
Learn More →...and more on the way. RiskSpan is continually adding AI tools and agents to the platform as new use cases emerge.
Why It's Different
Native to the Platform
No bolt-on vendor AI. Every tool runs on the same data, models, and cashflow engine already inside the RiskSpan Platform — no hand-offs.
Human-in-the-Loop
AI surfaces recommendations, mappings, and insights; your analysts confirm and tune — nothing runs fully autonomously without review.
Audit-Ready by Design
Every agent answer and mapping decision is traceable — SQL, assumptions, and source data are visible, not a black box.
Continuously Learning
Models and mappings improve from real client activity and RiskSpan's own loan and MBS data — not static rules.
RS Assistant
RS Assistant is RiskSpan's conversational AI, layered directly on RiskSpan Platform data — the newest and broadest member of the AI toolkit, spanning the same capabilities behind Smart Mapper and the Agentic AI for MBS Data tool. Ask a question in plain English across loan tapes, structured products, private ABF deals, or market data; RS Assistant queries live platform data, runs the calculation, and returns an answer with full lineage back to its source.
What RS Assistant Covers
Loan Tapes & Portfolio Analytics
- Ingests and maps raw loan tapes via Smart Mapper across residential, commercial, and consumer assets
- Runs strats, tape-to-tape reconciliation, and portfolio analytics (NPV, Greeks, OAS) down to the loan level
MBS & Structured Products
- Agency MBS collateral and prepayment analysis, including credit-score vintage comparisons
- Bond-level forecasting, ALM scenarios, stress/default testing for MBS, ABS, and CLO tranches
Private ABF & Market Data
- Extracts deal structures from offering docs and generates executable cashflow code for PABF deals
- Tracks rate curves and vol surfaces, and builds custom stress scenarios
See It In Action
“Map this new bank statement tape to RiskSpan Platform format and flag any fields that don’t match our standard schema.”
Loan Tape Processing“Pull the waterfall, triggers, and fees from this deal’s offering memo and generate the cashflow code.”
Private ABF“Every answer comes with full data lineage — trace any number back to the query or calculation that produced it.”
Trust & LineageWhy RiskSpan's AI, Not Generic AI
RiskSpan's AI tools are trained and tuned on real loan, MBS, and structured finance data — the same data and models that power the RiskSpan Platform's tape-cracking, collateral analytics, and cashflow engines. There's no hand-off between a generic chatbot and your actual portfolio data, and no re-tuning a consumer AI model to understand doc types, delinquency states, or pool factors. For issuers, investors, and servicers evaluating AI tools, that's the difference between an agent that understands mortgage data and one that's guessing.
Ready to see RiskSpan's AI tools on your own data?
Contact Your RiskSpan Representative →MBS Agent
Stop Waiting on Reports.
Get Instant Answers.
Ask questions in plain English. Get instant answers from Agency MBS data. No SQL. No Python. No waiting.
Who It’s For
Built for the workflows that matter most.
Natural language queries. Auditable SQL. Export-ready outputs. No data team required.
Practitioners,
Not Generalists.
Advisory, delivery, and on-demand expertise — from practitioners who've lived the workflows you're trying to fix. Platform + expert consulting, working as one.
Cleaner Data.
Faster Decisions.
Comprehensive data management consulting from strategy through production. We modernize data infrastructure, automate pipelines, and enable cloud-native architectures for structured finance.
- Data strategy & architecture
- Cloud & Snowflake implementation
- Automated data pipelines & QA
- Data warehousing & normalization
- Regulatory data readiness
Models.
That Stand Up to Scrutiny
End-to-end model lifecycle support from development through validation. Our quants and data scientists build, validate, and maintain credit, prepayment, and risk models for ABF portfolios.
- Model development & implementation
- Independent model validation (SR 11-7)
- Model risk management (MRM)
- Prepayment & credit model calibration
- AI & ML model deployment
Why RiskSpan Consulting.
Trusted Practitioners
Peers to your team — not generalists. We bring credibility, judgment, and structured finance experience from day one.
ABF-Fluent Across Data, Models & Infrastructure
Fluent at the intersection of data, models, and infrastructure in the most complex ABF workflows. No learning curve.
Speed to Value
POV engagements under 60 days, fixed fee. ROI demonstrated well before traditional firms finish discovery.
Unified Delivery Capabilities
Our consultants and platform work as one — implementations are faster, more consistent, and built to last.