Register here for next month’s call: Thursday, October 15th 2026, 1 p.m. ET.
Key Takeaways
- Prepayment models continue to track realized speeds well across Fannie, Freddie, and Ginnie collateral, with modeled CPRs running only modestly ahead of actuals
- Non-QM Credit Model 7.1 is getting an October 4th update that broadens the default definition (60+ days delinquent that liquidates = default), roughly doubling measured default rates — though re-estimated severity should offset much of that on a total-loss basis
- The planned “v4.0” prepayment model rebuild has been re-sequenced: an incremental v3.9 release (better FICO/LTV/loan-size controls, FHA/VA accuracy, re-estimated turnover) now comes first, with beta testing in early Q1 2027; the full structural rebuild slides to a Q4 2027 beta
- New deployment options — a Python wheel now in beta, with a REST API/Docker container, Windows DLL, and AWS Batch support to follow — will let clients run RiskSpan’s models inside their own infrastructure, with an MCP/AI connector on the longer-term roadmap
- The Fed funds rate looks set to stay elevated through 2026-2027, the 10-year Treasury is at its highest level since roughly 2007 (~5%), and mortgage rates could push above 7.5% by mid-2027 — a higher-for-longer environment that should keep housing inventory tight but limit the risk of a significant home price decline
This month’s call covered prepayment model back-testing, a deep dive on the model development roadmap (Non-QM Credit Model 7.1, the re-sequenced prepayment model plan, and new deployable model options), and the latest macro and housing picture. Janet Joswick, RiskSpan’s Head of Product, presented in place of Divas Sanwal this month.
You can read the recap below or click here for the entire recording.
Prepayment Model Back-Testing
Modeled CPRs continue to track observed speeds closely across both agency and Ginnie Mae collateral, with model results running only slightly fast versus actuals in the most recent observations. The full interactive backtesting dashboards — with additional cohort and cut options — are available in the RiskSpan platform under RS Insights.
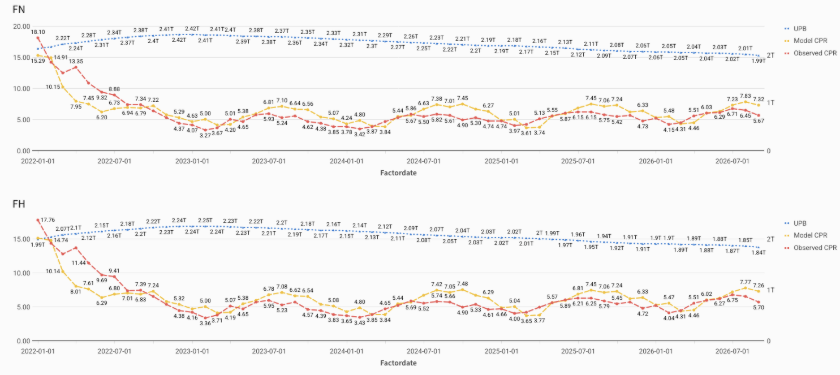
FN/FH WAC 5.5 and Below — Modeled vs. Observed CPR
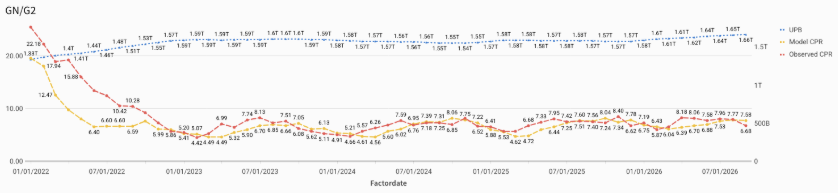
GN/G2 WAC 6 and Higher — Modeled vs. Observed CPR
Model Roadmap Updates
Non-QM Credit Model 7.1
An update to Credit Model 7.1 rolls out on October 4th. The headline change is a simplified default definition: any loan that reaches 60+ days delinquent and liquidates will now be flagged as a default, replacing a more nuanced (but harder to apply consistently) CoreLogic/Cotality-based definition. The change only affects late-stage transition rates (60→90, foreclosure, REO→default), but it roughly doubles measured default rates across documentation types.
Loss severity is being re-estimated in parallel, which is expected to partially offset the higher headline default rate on a total-loss basis — though the team is still working through how to model liquidations straight out of REO, where observed severity is frequently zero. Also landing in this release: prepayment penalty fees will flow through to final cashflows, which matters most for DSCR loans. Securities support for the credit model (currently whole-loan only) is targeted for December.
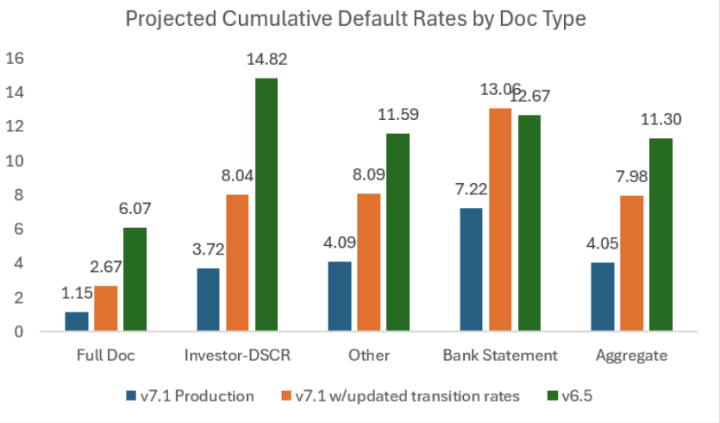
Projected Cumulative Default Rates by Doc Type: v7.1 Production vs. Updated Transition Rates vs. Legacy v6.5
Prepayment Model: Plan Shifted
Based on client feedback, RiskSpan has re-sequenced its prepayment model plans. Rather than moving straight to the full structural rebuild originally envisioned as v4.0, a faster, incremental v3.9 release will come first, building on the existing 3.8 agency model. Key improvements include additional FICO/LTV/loan-size controls, better floor and override controls, improved FHA-vs-VA accuracy within the Ginnie model (a frequent client pain point), and re-estimated turnover using post-COVID and recent jumbo-loan data. Beta testing is targeted for early Q1 2027, with full production shortly after.
The larger structural rebuild — now positioned as v4.0, with dedicated sub-models for curtailment, buyout, and cash-out — is still planned, with beta testing now targeted for Q4 2027 and production release in H1 2028. Clients interested in the v3.9 beta are encouraged to reach out to the RiskSpan team.
Deployable Model — Coming to Beta
RiskSpan is piloting a standalone, deployable version of its models for clients who want to run them inside their own infrastructure rather than through the platform UI or API. First out: a Python wheel (pip-installable, no server or network hop), already in beta with one client. On the roadmap: a REST API/Docker container, a Windows DLL for native C/C++ integration, and AWS Batch support. Further out, RiskSpan is also exploring an MCP connector that would let users run projections and calibrations conversationally through Claude or other AI tools, without writing code. Clients with use cases for model access outside the platform are encouraged to reach out.
Macroeconomic Update
The Fed funds rate is expected to stay elevated, with CME FedWatch data showing the current 375–400 bps range likely moving to 400–425 bps by year-end; a rate cut looks unlikely through 2026–2027.
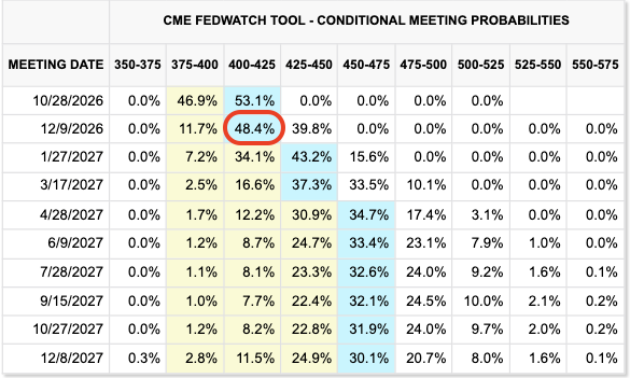
CME FedWatch Tool — Conditional Meeting Probabilities
The Treasury curve has shifted up in an almost parallel move over the past month, with the 10-year around 5% — its highest level since roughly July 2007.
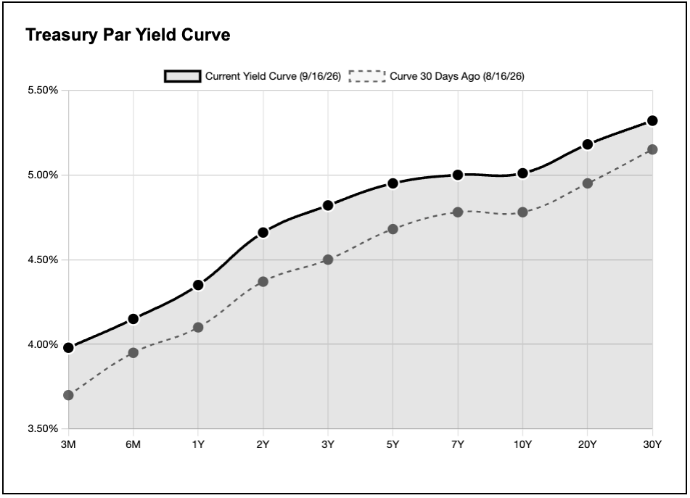
Treasury Par Yield Curve: Current vs. 30 Days Prior
Market consensus forecasts have the 10-year Treasury climbing above 5.4% in 2027, with 30-year mortgage rates potentially exceeding 7.5% by mid-2027. Mortgage rates have already moved sharply higher in recent weeks, with Mortgage News Daily quoting 7.24% as of September 16th.
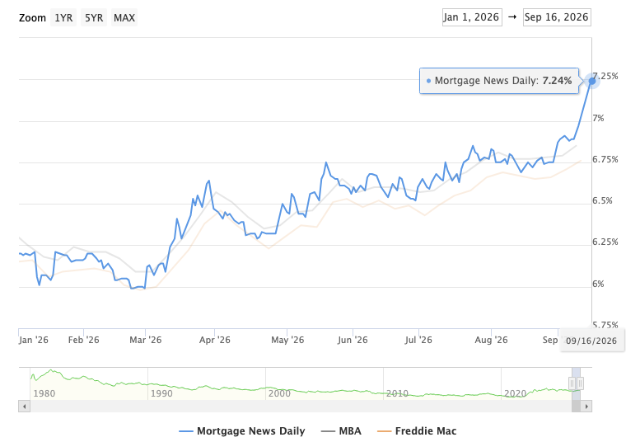
30-Year Fixed Mortgage Rate, Trailing 2 Years (Mortgage News Daily / MBA / Freddie Mac)
For housing, the combination of persistently high rates, negative homebuilder sentiment (fewer housing starts, less incentive spending), and low existing-home inventory — owners remain reluctant to give up lower-rate mortgages — should keep turnover and supply constrained.
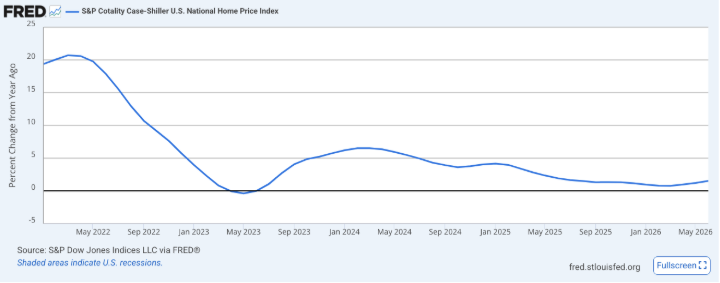
S&P Cotality Case-Shiller U.S. National Home Price Index, YoY % Change
RiskSpan’s view: that inventory scarcity should limit the risk of a significant home price decline, even as affordability stays stretched and core inflation remains elevated despite continued Fed intervention.
We continue to add additional analytics reports on the RiskSpan Platform. Please visit www.riskspan.com to request access.
As always, please feel free to contact us to discuss or learn more.
The way RMBS dealers communicate loan-level details to prospective investors today leaves a lot to be desired.
Any investor who has ever had to work with pre-issue Intex CDI files can attest to the problematic nature of the loan data they contain. Some are better than others, but virtually all of them lack information about any number of important loan features.
Investors can typically glean enough basic information about balances and average note rates from preliminary CDI files to run simple, static CPR/CDR scenarios. But information needed to run complex models — FICO scores, property characteristics and geography, and LTV ratios to name a few — is typically lacking. MBS investors who want to run to run more sophisticated prepayment and credit models – models that rely on more comprehensive loan-level datasets to run deeper analytics and scenarios – can be left holding the bag when these details are missing from the CDI file.
The loan-level detail exists – it’s just not in the CDI file. Loan-level detail often accompanies the CDI file in a separate spreadsheet (still quaintly referred to in the 21st Century as a “loan tape”). Having this data separate from the CDI file requires investors to run the loan tape through their various credit and prepayment models and then manually feed those results back into the Intex CDI file to fully visualize the deal structure and expected cash flows.
This convoluted, multi-step workaround adds both time and the potential for error to the pre-trade analytics process.
A Better Way
Investors using RiskSpan’s Edge Platform can streamline the process of evaluating a deal’s structure alongside the expected performance of its underlying mortgage loans into a single step.

Here is how it works.
As illustrated above, when investors set up their analytical runs on Edge, RiskSpan’s proprietary credit and prepayment models automatically extract all the required loan-level data from the tape and then connect the modeling results to the appropriate corresponding deal tranche in the CDI file. This seamlessness reduces all the elements of the pre-trade analytics process down to a matter of just a few clicks.
Making all this possible is the Edge Platform’s Smart Mapper ETL solution, which allows it to read and process loan tapes in virtually any format. Using AI, the Platform recognizes every data element it needs to run the underlying analytics regardless of the order in which the data elements are arranged and irrespective of how (or even whether) column headers are used.
Contact us to learn more about how RMBS investors are reaping the benefits of consolidating all of their data analytics on a single cloud-native platform.
Note: The following is the introduction from RiskSpan’s contribution to a series of essays on Climate Risk and the Housing Market published this month by the Mortgage Bankers Association’s Research Institute for Housing America.
Significant uncertainty exists about how climate change will occur, how all levels of government will intervene or react to chronic risks like sea level rise, and how households, companies, and financial markets will respond to various signals that will create movements in prices, demographics, and economic activity even before climate risk manifests. This paper lays out a pragmatic framework for assessing these risks from the perspective of a mortgage company. We evaluate available public and proprietary data sources and address data limitations, such as different sources providing a different view of risk for a particular property. We propose a sensitivity analysis approach to quantify risk and mitigate the uncertainties in measuring and responding to climate change.
Global temperatures will continue to increase over the next 50 years regardless of the actions people and governments take. The impacts of that warming are expected to accumulate and become more severe and frequent over time, causing stress throughout our economy. Regulators are clearly signaling that climate risk analysis will need to become a regular part of risk management activities. But detailed, industry-specific guidance has not been defined. FHFA and the regulated entities have yet to release a climate risk framework. They clearly recognize the threat to the housing finance system, however, and are actively working towards accounting for these risks.
Most executives and boards have become conceptually familiar with the physical and transition risks of climate change. But significant questions remain around how these concepts translate into specific, quantifiable business, asset, regulatory, legal, and reputation risks in the housing finance industry. Further complicating matters, climate science continues to evolve and there is limited historical data to understand how the effects of climate change will trickle into the housing market.
Sean Becketti[efn_note]Becketti, Sean R. “The Impact of Climate Change on Housing and Mortgage
Finance,” September 23, 2021.[/efn_note] describes the myriad ways climate change and natural hazard risk can permeate the housing and housing finance industries as well as some of the ways to mitigate its effects. However, quantifying these risks and inserting them into mortgage credit and prepayment models comes with significant challenges. No “best practices” have emerged for incorporating these into traditional model frameworks.
This paper puts forth a practical framework to incorporate climate risk into existing enterprise risk management practices for the housing finance industry. The framework incorporates suggestions to prepare for coming regulatory requirements on climate risk and, more importantly, proactively managing and mitigating this risk. Our approach is based on over two years of research and field work RiskSpan has conducted with its clients, and the resulting models RiskSpan has developed to deliver insights into these risks.
The paper is organized into two main sections:
- Prescribed Climate Scenarios and Emerging Regulatory Requirements
- A Practical Approach to Climate Risk Assessment for Mortgage Finance
Layering climate risk into enterprise risk management is likely to be a multiyear process. This paper focuses on steps to take in the initial one to two years after climate risk has been prioritized for investment of time and resources by corporate leadership. As explained in an MBA white paper from June 2022,[efn_note]Woodwell, Fratantoni, Seiler, “Who Owns Climate Risk in the U.S. Real Estate Market?,” June 2022[/efn_note] “Existing risk management practices, structures, and relationships are already capturing potential risks from climate change.” The aim of this paper is to investigate specific ways in which existing credit, operational, and market risk frameworks can be leveraged to address this challenge, rather than seeking to reinvent the wheel.
Quick take-aways
- HMDA data contains nearly every factor needed to replicate Fannie Mae’s Single Family Social Index. We use this data to explore how the methodology would look if the Fannie Mae Social Index were applied to other market participants.
- The Agencies and Ginnie Mae are not the only game in town when it comes socially responsible lending. Non-agency loans would also perform reasonably well under Fannie Mae’s proposed Social Index.
- Not surprisingly, Ginnie Mae outperforms all other “purchaser types” under the framework, buoyed by its focus on low-income borrowers and underserved communities. The gap between Ginnie and the rest of the market can be expected to expand in low-refi environments.
- With a few refinements to account for socially responsible lending beyond low-income borrowers, Fannie Mae’s framework can work as a universally applicable social measure across the industry.
Fannie Mae’s new “Single Family Social Index”
Last week, Fannie Mae released a proposed methodology for its “Single Family Social Index.” The index is designed to provide “socially conscious investors” a means of “allocat[ing] capital in support of affordable housing and to provide access to credit for underserved individuals.”
The underlying methodology is simple enough. Each pool of mortgages receives a score based on how many of its loans meet one or more specified “social criteria” across three dimensions: borrower income, borrower characteristics and property location/type. Fannie Mae succinctly illustrates the defined criteria and framework in the following overview deck slide.
 Figure 1: Source: Designing for Impact — A Proposed Methodology for Single-Family Social Disclosure
Each of the criteria is binary (yes/no) which facilitates the scoring. Individual loans are simply rated based on the number of boxes they check. Pools are measured in two ways: 1) a “Social Criteria Share,” which identifies the percentage of loans that meet any of the criteria, and 2) a “Social Density Score,” which assigns a “Social Score” of 0 thru 3 to each individual loan based on how many of the three dimensions (borrower income, borrower characteristics, and property characteristics) it covers and then averaging that score across all the loans in the pool.
If other issuers adopt this methodology, what would it look like?
The figure below is one of many charts and tables provided by Fannie Mae that illustrate how the Index works. This figure shows the share of acquisitions meeting one or more of the Social Index criteria (i.e., the overall “Social Criteria Share.” We have drawn a box approximately around the 2020 vintage,[1] which appears to have a Social Criteria Share of about 52% by loan count. We will refer back to this value later as we seek to triangulate in on a Social Criteria Share for other market participants.
 Figure 2: Source: Designing for Impact — A Proposed Methodology for Single-Family Social Disclosure
We can get a sense of other issuers’ Social Criteria Share by looking at HMDA data. This dataset provides everything we need to re-create the Index at a high-level, with the exception of a flag for first time home buyers. The process involves some data manipulation as several Index criteria require us to connect to two census-tract level data sources published by FHFA.
HMDA allows us break down the loan population by purchaser type, which gives us an idea of each loan’s ultimate destination—Fannie, Freddie, Ginnie, etc. The purchaser type does not capture this for every loan, however, because originators are only obligated to report loans that are closed and sold during the same calendar year.
The two tables below reflect two different approaches to approximating the population of Fannie, Freddie, and Ginnie loans. The left-hand table compares the 2020 origination loan count based on HMDA’s Purchaser Type field with loan counts based on MBS disclosure data pulled from RiskSpan’s Edge Platform.
The right-hand table enhances this definition by first re-categorizing as Ginnie Mae all FHA/VA/USDA loans with non-agency purchaser types. It also looks at the Automated Underwriting System field and re-maps all owner-occupied loans previously classified as “Other or NA” to Fannie (DU AUS) or Freddie (LP/LPA AUS).

The adjusted purchaser type approach used in the right-hand table reallocates a considerable number of “Other or NA” loans from the left-hand table. The approach clearly overshoots the Fannie Mae population, as some loans underwritten using Fannie’s automated underwriting system likely wind up at Freddie and other segments of the market. This limitation notwithstanding, we believe this approximation lends a more accurate view of the market landscape than does the unadjusted purchaser type approach. We consequently rely primarily on the adjusted approach in this analysis.
Given the shortcomings in aligning the exact population, the idea here is not to get an exact calculation of the Social Index metrics via HMDA, but to use HMDA to give us a rough indication of how the landscape would look if other issuers adopted Fannie’s methodology. We expect this to provide a rough rank-order understanding of where the richest pools of ‘Social’ loans (according to Fannie’s methodology) ultimately wind up. Because the ultimate success of a social scoring methodology can truly be measured only to the extent it is adopted by other issuers, having a universally useful framework is crucial.
The table below estimates the Social Criteria Share by adjusted purchaser using seven of Fannie Mae’s eight social index criteria.[2] Not surprisingly, Ginnie, Fannie, and Freddie boast the highest overall shares. It is encouraging to note, however, that other purchaser types also originate significant percentages of socially responsible loans. This suggests that Fannie’s methodology could indeed be applied more universally. The table looks at each factor separately and could warrant its own blog post entirely to dissect, so take a closer look at the dynamics.[3]

Ginnie Mae’s strong performance on the Index comes as no surprise. Ginnie pools, after all, consist primarily of FHA loans, which skew toward the lower end of the income spectrum, first-time borrowers, and traditionally underserved communities. Indeed, more than 56 percent of Ginnie Mae loans tick at least one box on the Index. And this does not include first-time homebuyers, which would likely push that percentage even higher.
Income’s Outsized Impact
Household income contributes directly or indirectly to most components of Fannie’s Index. Beyond the “Low-income” criterion (borrowers below 80 percent of adjusted median income), nearly every other factor favors income levels be below 120 percent of AMI. Measuring income is tricky, especially outside of the Agency/Ginnie space. The non-Agency segment serves many self-employed borrowers, borrowers who qualify based on asset (rather than income) levels, and foreign national borrowers. Nailing down precise income has historically proven challenging with these groups.
Given these dynamics, one could reasonably posit that the 18 percent of PLS classified as “low-income” is actually inflated by self-employed or wealthier borrowers whose mortgage applications do not necessarily reflect all of their income. Further refinements may be needed to fairly apply the Index framework to this and market segments that pursue social goals beyond expanding credit opportunities for low-income borrowers. This could just be further definitions on how to calculate income (or alternatives to the income metric when not available) and certain exclusions from the framework altogether (foreign national borrowers, although these may be excluded already based on the screen for second homes).
Positive effects of a purchase market
The Social Criteria Share is positively correlated with purchase loans as a percentage of total origination volume (even before accounting for the FTHB factor). This relationship is apparent in Fannie Mae’s time series chart near the top of this post. Shares clearly drop during refi waves.
Our analysis focuses on 2020 only. We made this choice because of HMDA reporting lags and the inherent facility of dealing with a single year of data. The table below breaks down the HMDA analysis (referenced earlier) by loan purpose to give us a sense for what our current low-refi environment could look like. (Rate/term refis are grouped together with cash-out refis.) As the table below indicates, Ginnie Mae’s SCS for refi loans is about the same as it is for GSE refi loans — it’s really on purchase loans where Ginnie shines. This implies that Ginnie’s SCS will improve even further in a purchase rate environment.

Accounting for First-time Homebuyers
As described above, our methodology for estimating the Social Criteria Share omits loans to first-time homebuyers (because the HMDA data does not capture it). This likely accounts for the roughly 6 percentage point difference between our estimate of Fannie’s overall Social Criteria Share for 2020 (approximately 46 percent) and Fannie Mae’s own calculation (approximately 52 percent).
To back into the impact of the FTHB factor, we can pull in data about the share of FTHBs from RiskSpan’s Edge platform. The chart above that looks a Purchase vs. Refi tells us the SCS share without the FTHB factor for purchase loans. Using MBS data sources, we can obtain the share of 2020 originations that were FTHBs. If we assume that FTHB loans look the same as purchase loans overall in terms of how many other Social Index boxes they check, then we can back into the overall SCS incorporating all factors in Fannie’s methodology.
Applying this approach to Ginnie Mae, we conclude that, because 29 percent of Ginnie’s purchase loans (one minus 71 percent) do not tick any of the Index’s boxes, 29 percent of FTHB loans (which account for 33 percent of Ginnie’s overall population) also do not tick any Index boxes. Taking 29 percent of this 33 percent results in an additional 9.6 percent that should be tacked on to Ginnie Mae’s pre-FTHB share, bringing it up to 66 percent.

Validating this estimation approach is the fact it increases Fannie Mae’s share from 46 percent (pre-FTHB) to 52 percent, which is consistent with the historical graph supplied by Fannie Mae (see Figure 2, above). Our FTHB approach implies that 92 percent of Ginnie Mae purchase loans meet one or more of the Index criteria. One could reasonably contend that Ginnie Mae FTHB loans might be more likely than Ginnie purchase loans overall to satisfy other social criteria (i.e., that 92 percent is a bit rich), in which case the 66 percent share for Ginnie Mae in 2020 might be overstated. Even if we mute this FTHB impact on Ginnie, however, layering FTHB loans on top of a rising purchase-loan environment would likely put today’s Ginnie Mae SCS in the low 80s.
[1] The chart is organized by acquisition month, our analysis of HMDA looks at 2020 originations, so we’ve tried to push the box slightly to the right to reflect the 1–3-month lag between origination and acquisition. Additionally, we think the chart and numbers throughout Fannie’s document are just Fixed Rate 30 loans, our analysis includes all loans. We did investigate what our numbers would look like if filtered to Fixed 30 and it would only increase the SCS slightly across the board.
[2] As noted above, we are unable to discern first-time homebuyer information from the HMDA data.
[3] We can compare the Fannie numbers for each factor to published rates in their documentation representing the time period 2017 forward. The only metric where we stand out as being meaningfully off is the percentage of loans in minority census tracts. We took this flag from FHFA’s Low-Income Area File for 2020 which defines a minority census tract having a ‘…minority population of at least 30 percent and a median income of less than 100 percent of the AMI.’ It is not 100% clear that this is what Fannie Mae is using in its definition.
Modeling Climate Risk and Property Valuation Stability
Part I of this white paper series introduced the case for why loan-level (as opposed to rep-line level) analytics are increasingly indispensable when it comes to effectively pricing an MSR portfolio. Rep-lines are an effective means for classifying loans across many important categories. But certain loan, borrower, and property characteristics simply cannot be “rolled up” to the rep-line level as easily as UPB, loan age, interest rate, LTV, credit score, and other factors. This is especially true when it comes to modeling based on available information about a mortgage’s subject property.
Assume for the sake of simplicity that human and automated appraisers do a perfect job of assigning property values for the purpose of computing origination and updated LTVs (they do not, of course, but let’s assume they do). Prudent MSR investors should be less interested in a property’s current value than in what is likely to happen to that value over the expected life of their investment. In other words, how stable is the valuation? How likely are property values within a given zip code, or neighborhood, or street to hold?
The stability of any given property’s value is tied to the macroeconomic prospects of its surrounding community. Historical and forecast trends of the local unemployment rate can be used as a rough proxy for this and are already built into existing credit and prepayment models. But increasingly, a second category of factors is emerging as an important predictor of home price stability, the property’s exposure to climate risk and natural hazard events.
Climate exposure is becoming increasingly difficult to ignore when it comes to property valuation. And accounting for it is more complicated than simply applying a premium to coastal properties. Climate risk is not just about hurricanes and storm surges anymore. A growing number of inland properties are being identified as at risk not just to wind and water hazards, but to wildfire and other perils as well. The diversity of climate risks means that the problem of quantifying and understanding them will not be solved simply by fixing out-of-date flood plain maps.
MSR investors are exposed to climate risk in ways that whole loan or securities investors are not. When climate events force borrowers into forbearance or other repayment plans, MSR investors not only forego the cash flows associated with missed interest payments that will never be made, but also incur the additional costs of administering the loss mitigation programs and making necessary P&I and escrow advances.
Overlaying climate scenario analysis on top of traditional credit modeling is unquestionably the future of quantifying mortgage asset exposure. And in many respects, the future is already here. Regulatory guidance is forthcoming requiring public companies to quantify their exposure to climate risk across three categories: acute physical risk, chronic physical risk, and economic transition risk.
Acute Risk
Acute climate risk describes a property’s exposure to individual catastrophic events. As a result of climate change, these events are expected to increase in frequency and severity. The property insurance space already has analytical tools in place to quantify property damage to hazard risks such as:
- Hurricane, including wind, storm surge, and precipitation-induced flooding
- Flooding, including “fluvial” and “pluvial” – on- and off-plan flooding
- Wildfire
- Severe thunderstorm, including exposure to tornadoes, hail, and straight-line wind, and
- Earthquake – though not tied to climate change, earthquakes remain a massively underinsured risk that can impact MSR holders
Acute risks are of particular concern for MSR holders as disaster events have proven to increase both mortgage delinquency and prepayment. The chart below illustrates these impacts after hurricane Katrina.

Chronic Risk
Chronic risk characterizes a property’s exposure to adverse conditions brought on by longer-term concerns. These include frequent flooding, sea level rise, drought hazards, heat stress, and water shortages. These effects could erode home values or put entire communities at risk over a longer period. Models currently in use forecast these risks over 20- and 25-year periods.
Transition Risk
Transition risk describes exposure to changing policies, practices or technologies that arise from a broader societal move to reduce its carbon footprint. These include increases in the direct cost of homeownership (e.g., taxes, insurance, code compliance, etc.), increased energy and other utility costs, and localized employment shocks as businesses and industry leave high-risk areas. Changing property insurance requirements (by the GSEs, for example) could further impact property valuations in affected neighborhoods.
———–
Converting acute, chronic and transition risks into mortgage modeling scenarios can only be done effectively at the loan level. Rep-lines cannot adequately capture them. As with most prepayment and credit modeling, accounting for climate risk is an exercise in scenario analysis. Building realistic scenarios involves taking several factors into account.
Scenario Analysis
Quantifying physical risks (whether acute or chronic) entails identifying:
- Which physical hazard types the property is exposed to
- How each hazard type threatens the property[1]
- The materiality of each hazard; and
- The most likely timeframes over which these hazards could manifest
Factoring climate risk into MSR pricing requires translating the answers to the questions above into mortgage modeling scenarios that function as credit and prepayment model inputs. The following table is an example of how RiskSpan overlays the impact of an acute event – specifically a category 5 hurricane in South Florida — on home price, delinquency, turnover and macroeconomic conditions.


Applying this framework to an MSR portfolio requires integration with an MSR cash flow engine. MSR cash flows and the resulting valuation are driven by the manner in which the underlying delinquency and prepayment models are affected. However, at least two other factors affect servicing cash flows beyond simply the probability of the asset remaining on the books. Both of these are likely impacted by climate risk.
- Servicing Costs: Rising delinquency rates are always accompanied by corresponding increases in the cost of servicing. An example of the extent to which delinquencies can affect servicing costs was presented in our previous paper. MSR pricing models take this into account by applying a different cost of servicing to delinquent loans. Some believe, however, that servicing loans that enter delinquency in response to a natural disaster can be even more expensive (all else equal) than servicing a loan that enters delinquency for other reasons. Reasons for this range from the inherent difficulty of reaching displaced persons to the layering impact of multiple hardships such events tend to bring upon households at once.[2]
- Recapture Rate: The data show that prepayment rates consistently spike in the wake of natural disasters. What is less clear is whether there is a meaningful difference in the recapture rate for these prepayments. Anecdotally, recapture appears lower in the case of natural disaster, but we do not have concrete data on which to base assumptions. This is clearly only relevant to MSR investors that also have an origination arm with which to capture loans that refinance.
Climate risk encompasses a wide range of perils, each of which affects MSR values in a unique way. Hurricanes, wildfires, and droughts differ not only in their geography but in the specific type of risk they pose to individual properties. Even if there were a way of assigning every property in an MSR portfolio a one-size-fits-all quantitative score, computing a “weighted average climate risk” value and applying it to a rep-line would be problematic. Such an average would be denuded of any nuance specific to individual perils. Peril-specific data is critical to being able to make the LTV, delinquency, turnover and macroeconomic assumption adjustments outlined above.
And there is no way around it. Doing all this requires a loan-by-loan analysis. RiskSpan’s Edge Platform was purpose built to analyze mortgage portfolios at the loan level and is becoming the industry’s go-to solution for measuring and managing exposures to market, credit and climate events.
Contact us to learn more.
[1] Insurability of hazards varies widely, even before insurance requirements are considered.
[2] In addition, because servicers normally staff for business-as-usual levels of delinquencies, a large acute event will create a significant spike in the demand for servicer personnel. If a servicer’s book is heavily concentrated in the Southeast, for example, a devastating storm could result in having to triple the number of people actively servicing the portfolio.
Improving MSR Pricing Using Cloud-Native Loan-Level Analytics (Part II)
- MSR investors are more exposed to acute climate risk than whole loan or securities investors are. MSR investors are not in a favorable position to recoup cash flows lost to climate disruptions.
- Climate risk can be acute, chronic, or transitional. Each affects MSR values in a different way.
- Integrating climate scenario analysis into traditional credit and prepayment modeling – both of which are critical to modeling MSR cash flows and pricing — requires a loan-by-loan approach.
- Climate risk cannot be adequately expressed or modeled using a traditional rep-line approach.
[pardot-form width=”400″ height=”600″ id=”8640″ title=”Improving MSR Pricing Using Cloud-Native Loan-Level Analytics (Part II) – WordPress”]
That climate change poses a growing—and largely unmeasured—risk to housing and mortgage investors is not news. As is often the case with looming threats whose timing and magnitude are only vaguely understood, increased natural hazard risks have most often been discussed anecdotally and in broad generalities. This, however, is beginning to change as the reality of these risks becomes increasingly clear to an increasing number of market participants and industry-sponsored research begins to emerge.
This past week’s special report by the Mortgage Bankers Association’s Research Institute for Housing America, The Impact of Climate Change on Housing and Housing Finance, raises a number of red flags about our industry’s general lack of preparedness and the need for the mortgage industry to take climate risk seriously as a part of a holistic risk management framework. Clearly this cannot happen until appropriate risk scenarios are generated and introduced into credit and prepayment models.
One of the puzzles we are focusing on here at RiskSpan is an approach to creating climate risk stress testing that can be easily incorporated into existing mortgage modeling frameworks—at the loan level—using home price projections and other stress model inputs already in use. We are also partnering with firms who have been developing climate stress scenarios for insurance companies and other related industries to help ensure that the climate risk scenarios we create are consistent with the best and most recently scientific research available.
Also on the short-term horizon is the implementation of FEMA’s new NFIP premiums for Risk Rating 2.0. Phase I of this new framework will begin applying to all new policies issued on or after October 1, 2021. (Phase II kicks in next April.) We wrote about this change back in February when these changes were slated to take effect back in the spring. Political pressure, which delayed the original implementation may also impact the October date, of course. We’ll be keeping a close eye on this and are preparing to help our clients estimate the likely impact of FEMA’s new framework on mortgages (and the properties securing them) in their portfolios.
Finally, this past week’s SEC statement detailing the commission’s expectations for climate-related 10-K disclosures is also garnering significant (and warranted) attention. By reiterating existing guidelines around disclosing material risks and applying them specifically to climate change, the SEC is issuing an unmistakable warning shot at filing companies who fail to take climate risk seriously in their disclosures.
Contact us (or just email me directly if you prefer) to talk about how we are incorporating climate risk scenarios into our in-house credit and prepayment models and how we can help incorporate this into your existing risk management framework.
It is, of course, impossible to view the human suffering wrought by Hurricane Ida without being reminded of Hurricane Katrina’s impact 16 years ago. Fortunately, the levees are holding and Ida's toll appears likely to be less severe. It is nevertheless worth taking a look at what happened to mortgages in the wake of New Orleans’s last major catastrophic weather event as it is reasonable to assume that prepayments could follow a similar pattern (though likely in a more muted way).
Following Katrina, prepayment speeds for pools of mortgages located entirely in Louisiana spiked between November 2005 and June 2006. As the following graph shows, prepayment speeds on Louisiana properties (the black curve) remained elevated relative to properties nationally (the blue curve) until the end of 2006.

Comparing S-curves of Louisiana loans (the black curve in the chart below) versus all loans (the green curve) during the spike period (Nov. 2005 to Jun. 2006) reveals speeds ranging from 10 to 20 CPR faster across all refinance incentives. The figure below depicts an S-curve for non-spec 100% Louisiana pools and all non-spec pools with a weighted average loan age of 7 to 60 months during the period indicated.

The impact of Katrina on Louisiana prepayments becomes even more apparent when we consider speeds prior to the storm. As the S-curves below show, non-specified 100% Louisiana pools (the black curve) actually paid slightly slower than all non-spec pools between November 2003 and October 2005.

As we pointed out in June, a significant majority of prepayments caused by natural disaster events are likely to be voluntary, as opposed to the result of default as one might expect. This is because mortgages on homes that are fully indemnified against these perils are likely to be prepaid using insurance proceeds. This dynamic is reflected in the charts below, which show elevated voluntary prepayment rates running considerably higher than the delinquency spike in the wake of Katrina. We are able to isolate voluntary prepayment activity by looking at the GSE Loan Level Historical Performance datasets that include detailed credit information. This enables us to confirm that the prepay spike is largely driven by voluntary prepayments. Consequently, recent covid-era policy changes that may reduce the incidence of delinquent loan buyouts from MBS are unlikely to affect the dynamics underlying the prepayment behavior described above.

RiskSpan’s Edge Platform enables users to identify Louisiana-based loans and pools by drilling down into cohort details. The example below returns over $1 billion in Louisiana-only pools and $70 billion in Louisiana loans as of the August 2021 factor month.
Edge also allows users to structure more specified queries to identify the exposure of any portfolio or portfolio subset. Edge, in fact, can be used to examine any loan characteristic to generate S-curves, aging curves, and time series. Contact us to learn more.

When it comes to climate concerns for the housing market, sea level rise and its impacts on coastal communities often get top billing. But this article in yesterday’s New York Times highlights one example of far-reaching impacts in places you might not suspect.
Chicago, built on a swamp and virtually surrounded by Lake Michigan, can tie its whole existence as a city to its control and management of water. But as the Times article explains, management of that water is becoming increasingly difficult as various dynamics related to climate change are creating increasingly large and unpredictable fluctuations in the level of the lake (higher highs and lower lows). These dynamics are threatening the city with more frequency and severe flooding.
The Times article connects water management issues to housing issues in two ways: the increasing frequency of basement flooding caused by sewer overflow and the battering buildings are taking from increased storm surge off the lake. Residents face increasing costs to mitigate their exposure and fear the potentially negative impact on home prices. As one resident puts it, “If you report [basement flooding] to the city, and word gets out, people fear it’s going to devalue their home.”
These concerns — increasing peril exposure and decreasing valuations — echo fears expressed in a growing number of seaside communities and offer further evidence that mortgage investors cannot bank on escaping climate risk merely by avoiding the coasts. Portfolios everywhere are going to need to begin incorporating climate risk into their analytics.
As hurricane (and wildfire) season ramps up, don’t sleep on the increase in prepayment speeds after a natural disaster event. The increase in delinquencies might get top billing, but prepays also increase after events—especially for homes that were fully insured against the risk they experienced. For a mortgage servicer with concentrated geographic exposure to the event area, this can be a double-whammy impacting their balance sheet—delinquencies increase servicing advances, prepays rolling loans off the book. Hurricane Katrina loan performance is a classic example of this dynamic.
