Register here for next month’s call: Thursday, October 15th 2026, 1 p.m. ET.
Key Takeaways
- Prepayment models continue to track realized speeds well across Fannie, Freddie, and Ginnie collateral, with modeled CPRs running only modestly ahead of actuals
- Non-QM Credit Model 7.1 is getting an October 4th update that broadens the default definition (60+ days delinquent that liquidates = default), roughly doubling measured default rates — though re-estimated severity should offset much of that on a total-loss basis
- The planned “v4.0” prepayment model rebuild has been re-sequenced: an incremental v3.9 release (better FICO/LTV/loan-size controls, FHA/VA accuracy, re-estimated turnover) now comes first, with beta testing in early Q1 2027; the full structural rebuild slides to a Q4 2027 beta
- New deployment options — a Python wheel now in beta, with a REST API/Docker container, Windows DLL, and AWS Batch support to follow — will let clients run RiskSpan’s models inside their own infrastructure, with an MCP/AI connector on the longer-term roadmap
- The Fed funds rate looks set to stay elevated through 2026-2027, the 10-year Treasury is at its highest level since roughly 2007 (~5%), and mortgage rates could push above 7.5% by mid-2027 — a higher-for-longer environment that should keep housing inventory tight but limit the risk of a significant home price decline
This month’s call covered prepayment model back-testing, a deep dive on the model development roadmap (Non-QM Credit Model 7.1, the re-sequenced prepayment model plan, and new deployable model options), and the latest macro and housing picture. Janet Joswick, RiskSpan’s Head of Product, presented in place of Divas Sanwal this month.
You can read the recap below or click here for the entire recording.
Prepayment Model Back-Testing
Modeled CPRs continue to track observed speeds closely across both agency and Ginnie Mae collateral, with model results running only slightly fast versus actuals in the most recent observations. The full interactive backtesting dashboards — with additional cohort and cut options — are available in the RiskSpan platform under RS Insights.
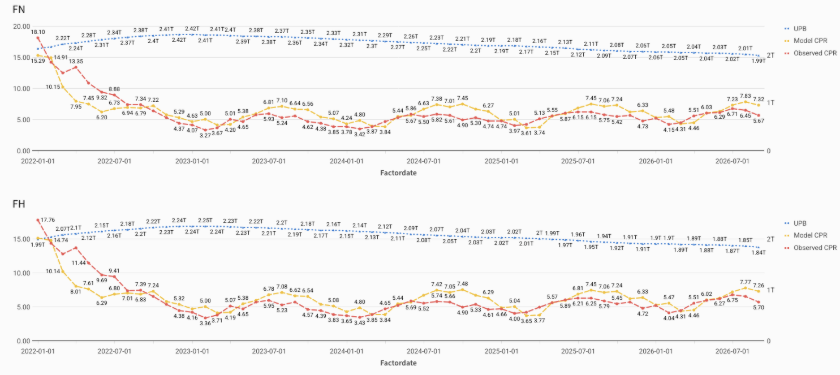
FN/FH WAC 5.5 and Below — Modeled vs. Observed CPR
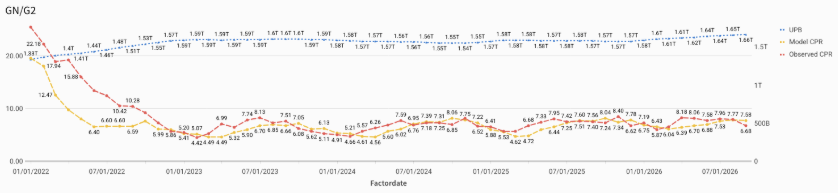
GN/G2 WAC 6 and Higher — Modeled vs. Observed CPR
Model Roadmap Updates
Non-QM Credit Model 7.1
An update to Credit Model 7.1 rolls out on October 4th. The headline change is a simplified default definition: any loan that reaches 60+ days delinquent and liquidates will now be flagged as a default, replacing a more nuanced (but harder to apply consistently) CoreLogic/Cotality-based definition. The change only affects late-stage transition rates (60→90, foreclosure, REO→default), but it roughly doubles measured default rates across documentation types.
Loss severity is being re-estimated in parallel, which is expected to partially offset the higher headline default rate on a total-loss basis — though the team is still working through how to model liquidations straight out of REO, where observed severity is frequently zero. Also landing in this release: prepayment penalty fees will flow through to final cashflows, which matters most for DSCR loans. Securities support for the credit model (currently whole-loan only) is targeted for December.
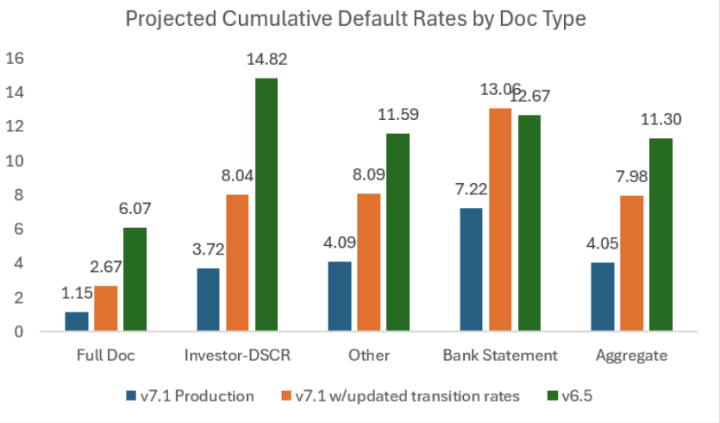
Projected Cumulative Default Rates by Doc Type: v7.1 Production vs. Updated Transition Rates vs. Legacy v6.5
Prepayment Model: Plan Shifted
Based on client feedback, RiskSpan has re-sequenced its prepayment model plans. Rather than moving straight to the full structural rebuild originally envisioned as v4.0, a faster, incremental v3.9 release will come first, building on the existing 3.8 agency model. Key improvements include additional FICO/LTV/loan-size controls, better floor and override controls, improved FHA-vs-VA accuracy within the Ginnie model (a frequent client pain point), and re-estimated turnover using post-COVID and recent jumbo-loan data. Beta testing is targeted for early Q1 2027, with full production shortly after.
The larger structural rebuild — now positioned as v4.0, with dedicated sub-models for curtailment, buyout, and cash-out — is still planned, with beta testing now targeted for Q4 2027 and production release in H1 2028. Clients interested in the v3.9 beta are encouraged to reach out to the RiskSpan team.
Deployable Model — Coming to Beta
RiskSpan is piloting a standalone, deployable version of its models for clients who want to run them inside their own infrastructure rather than through the platform UI or API. First out: a Python wheel (pip-installable, no server or network hop), already in beta with one client. On the roadmap: a REST API/Docker container, a Windows DLL for native C/C++ integration, and AWS Batch support. Further out, RiskSpan is also exploring an MCP connector that would let users run projections and calibrations conversationally through Claude or other AI tools, without writing code. Clients with use cases for model access outside the platform are encouraged to reach out.
Macroeconomic Update
The Fed funds rate is expected to stay elevated, with CME FedWatch data showing the current 375–400 bps range likely moving to 400–425 bps by year-end; a rate cut looks unlikely through 2026–2027.
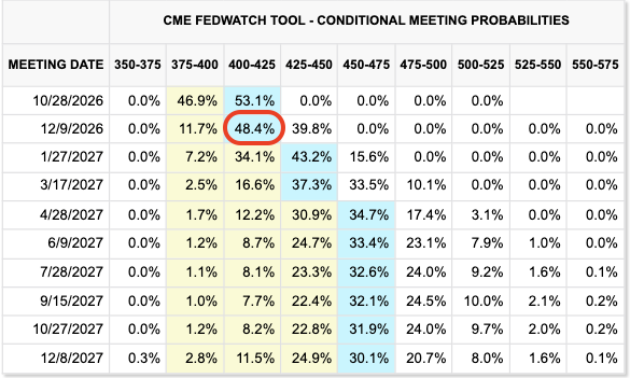
CME FedWatch Tool — Conditional Meeting Probabilities
The Treasury curve has shifted up in an almost parallel move over the past month, with the 10-year around 5% — its highest level since roughly July 2007.
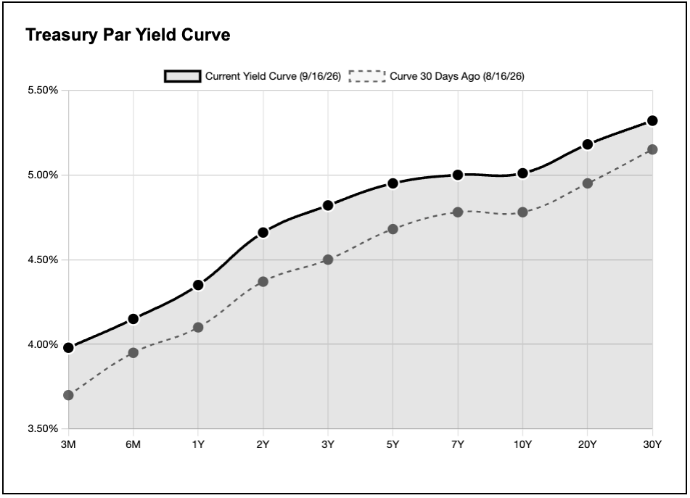
Treasury Par Yield Curve: Current vs. 30 Days Prior
Market consensus forecasts have the 10-year Treasury climbing above 5.4% in 2027, with 30-year mortgage rates potentially exceeding 7.5% by mid-2027. Mortgage rates have already moved sharply higher in recent weeks, with Mortgage News Daily quoting 7.24% as of September 16th.
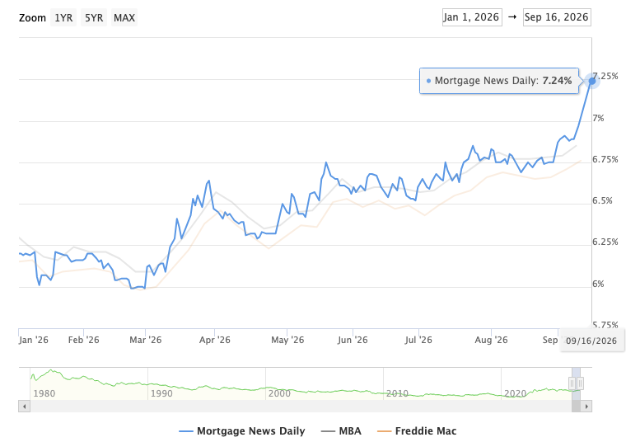
30-Year Fixed Mortgage Rate, Trailing 2 Years (Mortgage News Daily / MBA / Freddie Mac)
For housing, the combination of persistently high rates, negative homebuilder sentiment (fewer housing starts, less incentive spending), and low existing-home inventory — owners remain reluctant to give up lower-rate mortgages — should keep turnover and supply constrained.
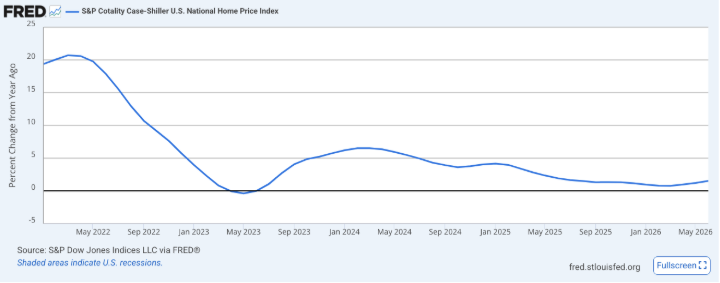
S&P Cotality Case-Shiller U.S. National Home Price Index, YoY % Change
RiskSpan’s view: that inventory scarcity should limit the risk of a significant home price decline, even as affordability stays stretched and core inflation remains elevated despite continued Fed intervention.
We continue to add additional analytics reports on the RiskSpan Platform. Please visit www.riskspan.com to request access.
As always, please feel free to contact us to discuss or learn more.
Register here for next month’s call: Thursday, September 17th 2026, 1 p.m. ET.
Key Takeaways
- Prepayment models continue to track realized speeds well, even as July speeds fell across the board: roughly 4% for FN/FH coupons 5.5 and below, 3.8–4.7% for FN/FH 6 and higher, and 1.7% (≤5.5) and 7.5% (6+) for Ginnie
- A deeper look at the conventional universe shows where the v3.7 model is straining: it ran 1.7 CPR fast on FH30 in July (10.0 modeled vs. 8.3 actual), missed month-over-month direction for out-of-the-money cohorts, and shows S-curves that are too flat for unseasoned loans and too steep for seasoned ones
- Federal debt has reached $40 trillion (about 125% of GDP, with a deficit near 6% of GDP), while consumer stress is concentrated in credit cards (~13% of balances 90+ days delinquent), autos (approaching 6%), and borrowers aged 70+
- The 30-year Treasury touched 5.30%, its highest level in roughly 20 years; the Fed funds rate (350–375 bps) is expected to hold at the next two meetings, with a meaningful chance of an increase and no cuts expected through 2027
- Consensus forecasts put the 10-year Treasury above 5% in 2027 and 30-year mortgage rates above 7% around the turn of the year; with core inflation near 2.5%, a weakening labor market, and tight inventory, home prices look more likely to stagnate than fall significantly
This month’s call covered prepayment model back-testing, a conventional deep dive on model performance and CBR/CCR trends, federal and consumer debt, and the latest macro and housing picture. Yashwant and Anish Roy of RiskSpan’s quantitative modeling team and Divas Sanwal presented.
You can read the recap below or click here for the entire recording.
Prepayment Model Back-Testing
Modeled CPRs continue to track observed speeds closely, though speeds declined across all cohorts with the August factor data update. Fannie/Freddie coupons 5.5 and below fell approximately 4%. For coupons 6 and higher, Fannie speeds fell 4.7% and Freddie 3.8%. Ginnie Mae coupons 5.5 and below fell approximately 1.7%, while Ginnie 6 and higher fell approximately 7.5%.
The team attributes the slowdown in premium coupons (6 and higher) primarily to a 7 bp rise in the driving mortgage rate, partially offset by a 5% increase in day count. For coupons 5.5 and below, the decline reflects an 8% month-over-month drop in seasonal housing turnover. The full interactive back-testing reports are available in the RiskSpan platform.
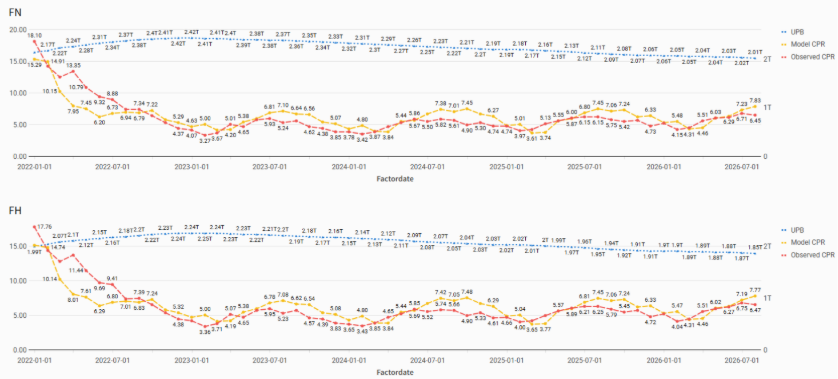
FN/FH WAC 5.5 and Below — Modeled vs. Observed CPR
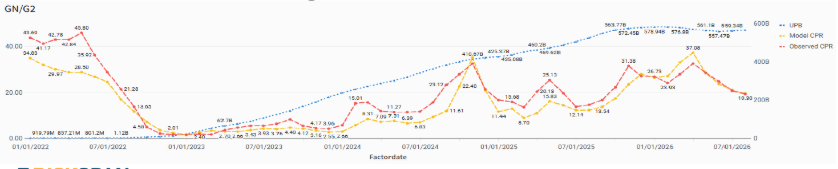
GN/G2 WAC 6 and Higher — Modeled vs. Observed CPR
Conventional Deep Dive: Model Performance and CBR/CCR Trends
As in prior months, the quantitative modeling team took a closer look at the conventional universe using model v3.7. This research also supports the next-generation prepayment model initiative by providing a more granular view of prepayment behavior and highlighting opportunities for future enhancements.
FH30 Aggregate and Coupon-Level Speeds
FH30 printed 8.3 CPR in July 2026 versus a model prediction of 10.0 CPR, a fast bias of 1.7 CPR. Month over month, actual speeds fell 4% while model speeds rose 4%. Following client feedback, the team added 3-, 6-, and 12-month error ratios this month. At the aggregate level, the model carries a 12% fast bias over the trailing three months, versus only 2% over six and twelve months. Over the trailing 12 months, coupons 1.5%–5.5% have been persistently about 10% faster than actuals, while coupons 6.0%–7.0% have been persistently about 10% slower.
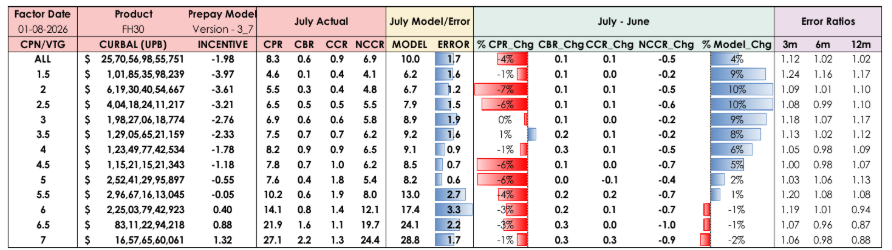
FH30 Aggregate and Coupon-Level Speeds — Actual vs. Model v3.7 (July 2026)
Missed Directionality for Out-of-the-Money Cohorts
The model missed month-over-month direction for out-of-the-money cohorts: model speeds rose about 7% while actuals fell about 3%. In-the-money cohorts behaved as expected, with model speeds down 1% and actuals down 2%. The team believes the miss is driven by the model’s seasonality component, which needs further calibration. Level errors are largest on the higher, in-the-money coupons, but month-over-month sensitivity is greater for out-of-the-money cohorts. Behind the aggregate 4% decline in actual speeds, the 7 bp rise in the 30-year driving rate and 8% drop in turnover seasonality were partly offset by a 5% increase in day count.
S-Curves by Loan Size and Seasoning
New this month, the team plotted S-curves of actuals against the model by loan size and moneyness, split into unseasoned (WALA 0–18, left) and seasoned (WALA 18–60, right) loans. The findings point in opposite directions:
- Unseasoned loans: the model S-curve is too flat. The in-the-money $400K+ cohort has a significant slow bias of about 12 CPR at a 7% coupon. Out-of-the-money cohorts converge within about 5 CPR, except the $0–200K cohort, which runs about 10 CPR slow. The model also does not capture the expected rise in speeds with loan size at a given incentive.
- Seasoned loans: the model S-curve is too steep. The in-the-money $400K+ cohort has a fast bias of about 7 CPR at a 7% coupon, and the $0–200K cohort is about 5 CPR fast. The model did not apply enough burnout decay.
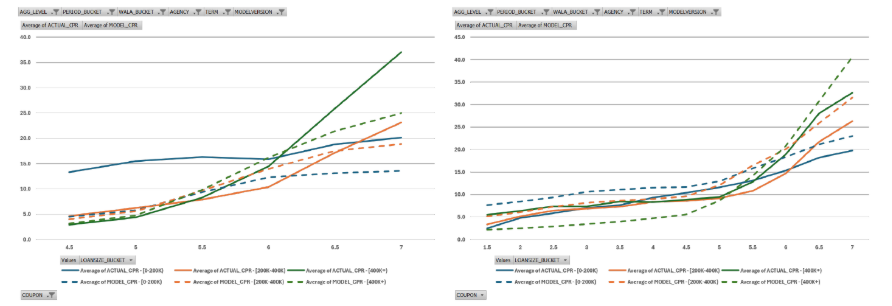
FH30 vs. Model (v3.7) S-Curve by Loan Size — Last 3 Months, WALA 0–18 (L) vs. 18–60 (R)
Buyout and Curtailment Across the Coupon Stack
Curtailment (CCR) follows a hump shape across coupons, peaking around 5.5%. This is primarily a seasoning effect: the 5.5% cohort has the lowest WALA, curtailment is front-loaded and peaks around a WALA of four, and the pattern is amplified by occupancy and purpose mix. Buyout (CBR), by contrast, rises sharply with coupon, especially at the high end. At a 7% coupon, CBR is roughly 3–5 times that of lower coupons, and the 7% coupon also has the lowest average FICO in the stack (725), consistent with higher-coupon loans being disproportionately associated with borrower credit stress.
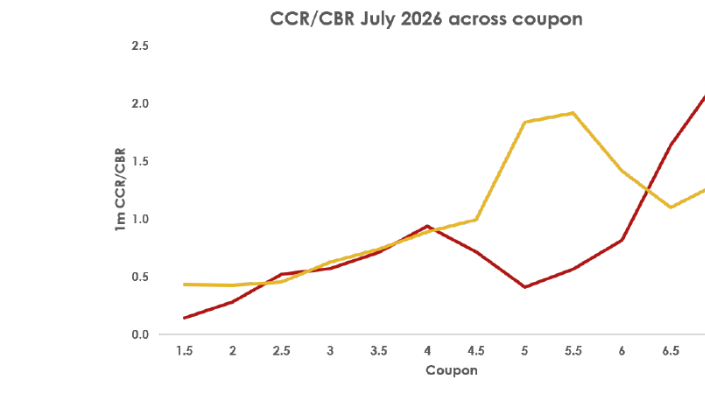
FH30 CBR and CCR Across Coupon (Actual), July 2026
Debt and Consumer Credit
The call opened this section with a new milestone: total U.S. national debt has reached $40 trillion. Roughly $50 trillion is expected within about five years, which RiskSpan’s reference thresholds treat as the point at which federal debt becomes unsustainable.
| Federal Metric | Current (Aug 2026) | Unsustainable Threshold |
| Total National Debt | $40 trillion | ~$50T by 2031 |
| Debt-to-GDP Ratio | 124.6% (June) | 140% (Penn Wharton) |
| Federal Budget Deficit | ~6% of GDP | 4–5% unsustainable |
| Deficit/Revenue Ratio | $1.33 spent per $1 revenue | $1.20+ unsustainable |
Federal Government Debt vs. Reference Thresholds
Federal interest costs are a growing concern. With the 30-year Treasury at 5.30%, new issuance replaces older, cheaper debt at higher rates, and debt service is already the government’s second-largest expense after Social Security. Unlike Social Security, it cannot be cut without risking the country’s credit rating.
Household debt stands at approximately $18.77 trillion, up about 2.1% year over year (and essentially flat versus $18.78 trillion in Q1, per the NY Fed’s August report). Mortgages make up about $13.6 trillion of that, leaving roughly $5 trillion of non-mortgage debt, with the fastest growth in auto loans and credit cards.
| Debt Category | Amount | % of Total | YoY Growth |
| Total Household Debt | $18.77T | 100% | ~2.1% |
| Mortgage Debt | $13.58T | 72.3% | ~2.0% (all-time high) |
| Auto Loans/Leases | $1.72T | 9.2% | 2.9% |
| Credit Cards | $1.26T | 6.7% | 3.9% |
| Student Loans | $1.87T | 9.9% | Slowed with payment pause |
| Other | $0.4T | 2.1% | Varies |
Household Debt Breakdown, Q2 2026
Where the Stress Is Showing
- Credit cards: There are approximately 650 million credit card accounts, roughly three per adult, and the count has grown rapidly over the last decade while other account types have been flat. Card balances of about $1.3 trillion sit against roughly $5.5 trillion in limits (about 20% utilization), and approximately 13% of balances are 90+ days delinquent, close to the financial-crisis peak. Much of this delinquent balance sits with smaller banks and fintechs rather than large banks, which have been careful about extending credit to lower-credit borrowers.
- Auto loans: 90+ day delinquency is approaching 6%, higher than at any point during the financial crisis. With the used-car market where it is, servicing and even repossession are often unprofitable, which is a concern for lenders as well as borrowers.
- HELOCs: Home equity revolving balances have grown meaningfully over the last four years, with about $0.5 trillion drawn against roughly $1 trillion in limits (about 50% utilization).
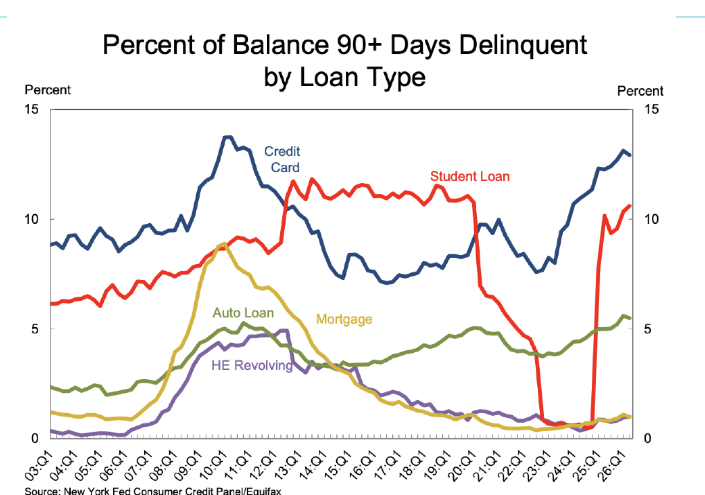
Percent of Balance 90+ Days Delinquent by Loan Type (NY Fed Consumer Credit Panel/Equifax)
One notable finding in the NY Fed data: younger borrowers have always shown the highest delinquency transition rates, but the 70+ age group now stands out for auto loans and credit cards, with rising transitions into serious delinquency. These borrowers are often on fixed incomes, so RiskSpan views this as an indirect signal of how inflation is eroding households’ ability to maintain their lifestyles.
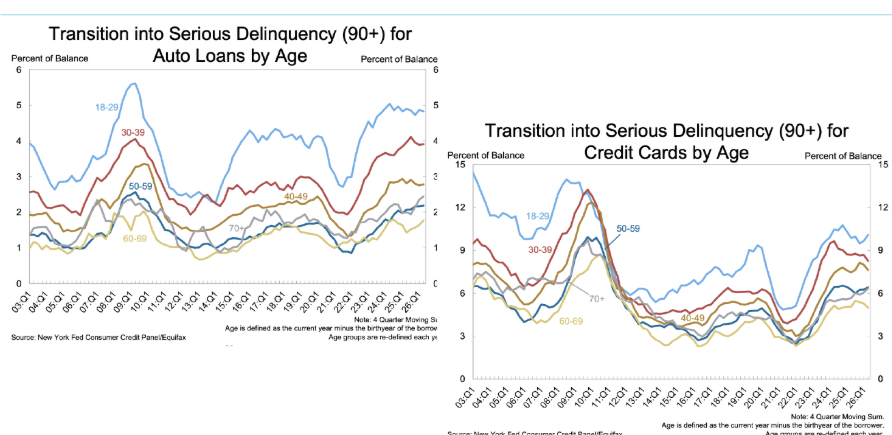
Transition into Serious Delinquency (90+) by Age — Auto Loans (L) and Credit Cards (R)
Where Averages Deceive
The average hides a sharp split in debt burden. The illustrative comparison below shows how much the mix of debt matters: a median household’s debt is dominated by low-rate mortgages, while the bottom quartile carries disproportionately high-rate revolving and subprime debt. Any economic shock could have an outsized impact on the credit market through that bottom segment.
| Median Household | Bottom Quartile | |
| Gross income | ~$80,000 | ~$40,000 |
| Disposable income | ~$65,000 | ~$35,000 |
| Debt | ~$35,000 | ~$15,000 |
| Debt mix | Low-rate mortgage (3.5–4%), card balance (~20%), auto loan (~8%), student loans | Subprime auto (~12%), credit cards (~24%), medical debt |
| Debt burden (% of disposable income) | ~30–35%: stretched but managing | 40–50%: severely strained |
Median Household vs. Bottom Quartile (Reference Figures)
Macroeconomic Update
Rates
The Fed made no change to the Fed funds rate in July and does not meet in August. The current range is 350–375 bps, and CME FedWatch data point to a hold in September (about 67% probability), a year-end range of 375–400 bps, and a meaningful likelihood of an increase this year. A rate cut looks unlikely through 2026–2027.
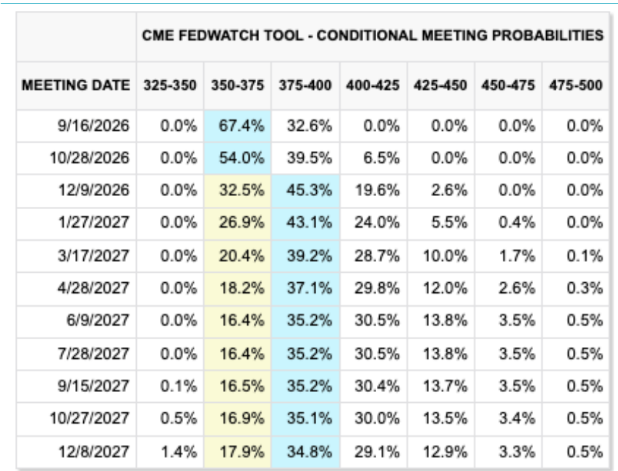
CME FedWatch Tool — Conditional Meeting Probabilities
On the Treasury side, the Treasury curve (Aug 17–18) showed the 2-year at 4.19%, 5-year at 4.36%, 10-year at 4.72%, and 30-year at 5.30%, the highest 30-year yield in roughly 20 years.
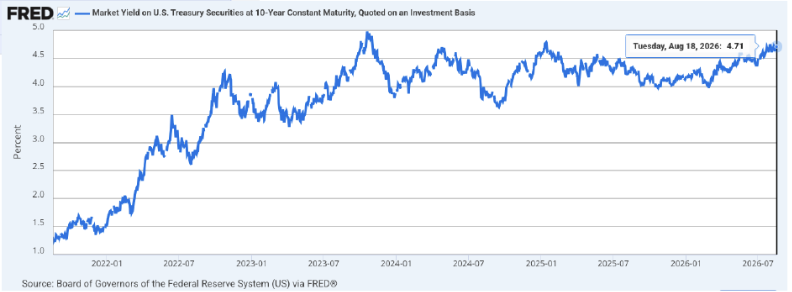
10-Year Treasury Constant Maturity Yield (FRED)
Market consensus has the 10-year Treasury moving above 5% in 2027, and 30-year mortgage rates rising above 7% around the end of this year or early 2027, peaking near 7.2%. Mortgage rates dipped just below 6% in late February, but have since climbed to roughly 6.75–6.80% (Mortgage News Daily), and the consensus path suggests more room to rise before they fall.
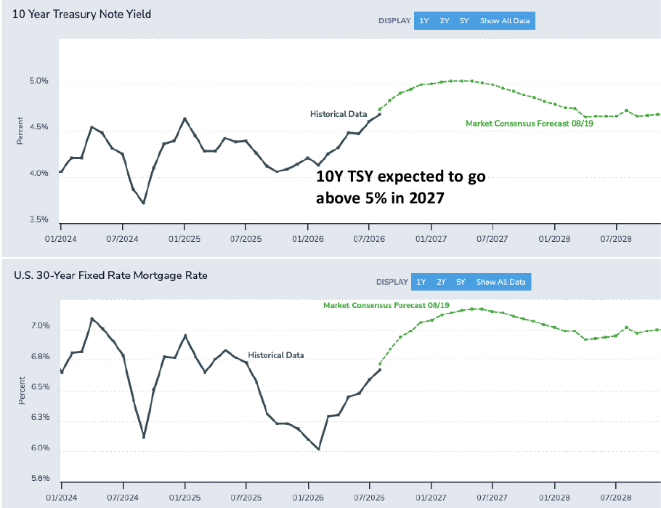
10-Year Treasury and 30-Year Fixed Mortgage Rate — Market Consensus Forecast (as of 8/19)
Inflation, Growth, and Labor
Core inflation has sat around 2.5% for a long time, well above the Fed’s 2% target. Much of the recent volatility in headline inflation, which peaked near 4.2% in May before easing to 3.5% in June and 3.4% in July, has been driven by energy prices. With core measures still elevated, the Fed has little flexibility to cut. The Producer Price Index is also rising, a signal of higher consumer inflation in the coming months, since retailers have limited capacity to absorb further cost increases.
| Inflation Measure | July 2026 | June 2026 | Fed Target |
| CPI (Headline) | 3.4% YoY | 3.5% YoY | 2.0% |
| Core CPI (ex-food/energy) | 2.5% YoY | 2.6% YoY | ~2.0% |
| PCE (Headline) | 3.2% YoY (est.) | 3.3% YoY | 2.0% |
| Core PCE (ex-food/energy) | 2.6% YoY (est.) | 2.7% YoY | 2.0% |
| Energy Component | Fell 5.7% MoM | Up 15.7% YoY | N/A |
Headline vs. Core Inflation
On growth, current estimates put 2026 GDP growth at around 2% (Goldman Sachs at 2.8%, Deloitte at 2.0%), with 2027 expected to be weaker, and Deloitte’s downside scenario is recessionary. The labor market is showing strain: July nonfarm payrolls fell by 23,000, a first-time decline, and June was revised down sharply to +20,000. Unemployment ticked down to 4.1%, but only because labor force participation also fell to 61.4%, and with wage growth slowing to 3.2%, real wages are now negative.
| Labor Market Metric | July | June | Change |
| Nonfarm Payrolls | -23,000 | +20,000 (revised) | -43,000 |
| Unemployment (U-3) | 4.1% | 4.2% | -0.1pp |
| Labor Force Participation | 61.4% | 61.5% | -0.1pp |
| Wage Growth (YoY) | 3.2% | 3.5% | -0.3pp |
| CPI Inflation (YoY) | 3.4% | 3.5% | -0.1pp |
| Real Wage Growth | -0.2% | 0.0% | -0.2pp |
Labor Market, July 2026
Implications for the Housing Market
The Case-Shiller National Home Price Index is still growing, but only about 1% year over year. Persistently high mortgage rates mean little refinance activity, and out-of-the-money loans are likely to stay that way. Homebuilder sentiment has turned negative as costs rise and margins look thin, so housing starts are expected to decline. Builder incentives such as down payment help and rate buydowns, which have supported a significant share of new-home sales in recent years, are coming under pressure.
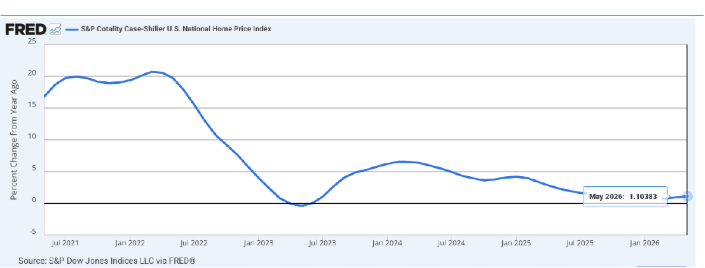
S&P Cotality Case-Shiller U.S. National Home Price Index, YoY % Change
RiskSpan’s view: with few new homes available and builder incentives fading, inventory constraints make a significant home price decline unlikely. Prices should stay close to current levels, with perhaps a moderate increase. Geopolitics remains the major macro driver of markets, so it is worth keeping an eye on.
We continue to add additional analytics reports on the RiskSpan Platform. Please visit www.riskspan.com to request access.
As always, please feel free to contact us to discuss or learn more.
Arlington, VA – July 17, 2026 – RiskSpan, a leading provider of data, modeling and analytics solutions for loan and structured finance investors, today announced the general availability of Credit Model 7.1, a purpose-built NonQM credit model delivered inside the RiskSpan Platform. Paired with RiskSpan’s existing NonQM prepayment model, the launch makes RiskSpan the only vendor offering a purpose-built prepay and credit model suite for NonQM alongside an integrated, tape-to-cashflow workflow in a single environment.
The launch comes as the NonQM market extends a multi-year run of outsized, accelerating growth. Non-QM RMBS issuance nearly doubled year-over-year in the third quarter of 2025 — up 97% to a record $20.9 billion, from $10.6 billion in the same quarter of 2024 — according to Morningstar DBRS. That surge continues a longer trend: Fitch Ratings reports that issuance across its rated Non-QM/Non-Prime RMBS portfolio grew more than 800% between 2020 and 2023, and KBRA projects broader non-agency RMBS issuance, which includes NonQM, to grow another 15% in 2026 to $160 billion. That growth has outrun the tools available to evaluate it: as dealer tapes arrive faster and allocations close on tighter timelines, investors and issuers are increasingly underserved by legacy credit and prepay models built for agency or older non-agency collateral rather than NonQM’s doc-type-driven borrower behavior.
Credit Model 7.1 introduces a full transition-state credit model for NonQM collateral, with each transition estimated independently models for Bank Statement, DSCR, Full Doc, and Other documentation types. The model incorporates ten loan- and borrower-level factors — including FICO, mark-to-market LTV, DTI, and loan purpose — alongside three macroeconomic drivers, and is trained on approximately $87 billion in UPB across roughly 226,000 NonQM loans spanning January 2018 through August 2025. The release also includes AI-powered tape cracking and collateral analysis tools, and API access for clients integrating model output into their own workflows, with a user-facing backtesting dashboard coming soon.
Divas Sanwal, Head of Modeling at RiskSpan, added: “NonQM borrower behavior varies meaningfully by documentation type, and generic credit and prepay frameworks simply don’t capture that. Credit Model 7.1 was built from the ground up on NonQM collateral, segmented by doc type, and validated with published backtesting — giving risk teams, auditors, and counterparties the transparency they need to stand behind the model.”
The NonQM analytics market today is served by third-party models fit on broader non-agency collateral, standalone cashflow engines, and in-house models built on limited internal history. RiskSpan is the only vendor combining purpose-fit NonQM prepay and credit models, loan-level workflow tools, and proprietary historical data in one platform. Credit Model 7.1 is available now to RiskSpan Platform and Loans Module clients, with container deployment and additional integrations planned in later phases.
About RiskSpan
RiskSpan delivers a single analytics solution for loan and structured finance (public and private) credit investors of any size – to make faster, more precise trading and portfolio management decisions and meet reporting requirements without manual work, multiple vendors and internal solutions.
RiskSpan’s contributions span the full lifecycle of structured finance pricing and data operations, including advanced cash flow and valuation models, automated data pipelines, quality controls, and reconciliation frameworks designed to meet the demands of institutional investors, dealers, and risk managers.
Learn more at www.riskspan.com.
For media inquiries, please contact:
Samantha Wilcox
sawilcox@riskspan.com
425-652-6700
Register here for next month’s call: Thursday, August 20th, 2026, 1 p.m. ET.
Key Takeaways
- Prepayment models remain reliable, but the fast bias showing up in in-the-money cohorts is worth watching if rates keep climbing and more loans move into the money
- Non-QM credit risk is becoming a bigger focus right as CM 7.1 goes live — the model is arriving just as delinquency trends turn less benign
- The market has flipped from pricing rate cuts to pricing a hike this year — a real shift in the rate outlook, not noise
- Elevated rates and mortgage costs look like a multi-year reality rather than a temporary plateau, with labor data adding a note of underlying softness beneath a falling headline unemployment rate
This month’s call covered prepayment model back-testing, a deep dive on conventional model performance, the growing Non-QM universe, the production release of RiskSpan’s Non-QM Credit Model (CM 7.1), and the latest macro picture.
You can read the recap below or click here for the entire recording.
Prepayment Model Back-Testing
The prepayment model continues to closely track realized speeds across Fannie, Freddie, and Ginnie collateral. Discount coupons (WAC 5.5 and below) remain structurally low and range-bound at roughly 4–8 CPR, consistent with these loans sitting out of the money in a turnover-driven regime. Premium coupons (WAC 6 and above) eased slightly in June, as a 13 bp increase in the driving mortgage rate outweighed a 5% rise in day count — visible in a modest month-over-month flattening of the conventional S-curve. FHA/VA aging-ramp peaks have also come down from prior levels, with VA loans continuing to ramp faster and higher than FHA.
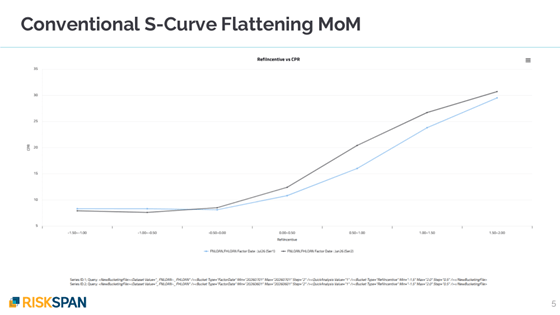
Conventional S-Curve Flattening MoM
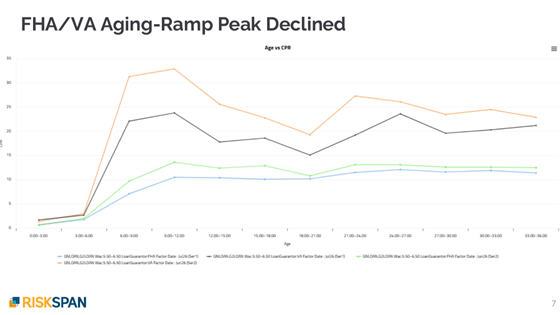
FHA/VA Aging-Ramp Peak Declined
Conventional Deep Dive
A closer look at FH30 and FN30 performance found the model running fast versus actuals in June — a bias of roughly 1 CPR — with month-over-month direction captured well but magnitude off: the model overreacts in out-of-the-money cohorts and underreacts in in-the-money cohorts, where its error is markedly larger (~2 CPR vs. ~0.8 CPR).
Curtailment and buyout activity move in opposite directions over a loan’s life. Curtailments are front-loaded, peaking in the newest vintages and fading with age, while buyouts build slowly and grow as loans season and credit stress accumulates. The effect is large: comparing 2023 to 2025 vintages in higher-coupon cohorts, Freddie Mac loans show roughly 7x the buyout activity, and Fannie Mae loans show roughly 3x.
Non-QM Universe and Credit Model 7.1
Non-QM issuance is tracking toward roughly $100B for 2026 — Q2 came in around $27B, down 16% quarter-over-quarter but up 58% year-over-year — with originations running at about $170–180B. Delinquency data gave a mildly encouraging signal, with the 2023 vintage appearing to plateau around 24 months of loan age, though risk stays concentrated in bank-statement and self-employed borrowers and lower FICO bands. Zooming out, delinquency has been climbing across consumer credit broadly (subprime auto, personal loans, mortgage, Non-QM) since 2021.
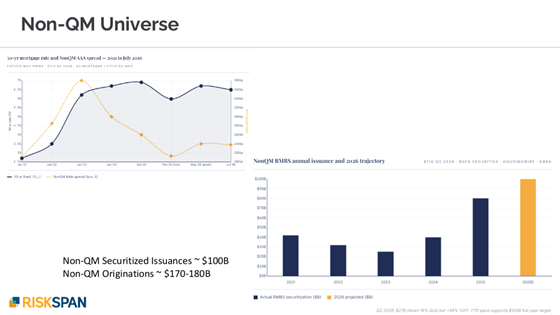
Non-QM RMBS Issuance and 2026 Trajectory
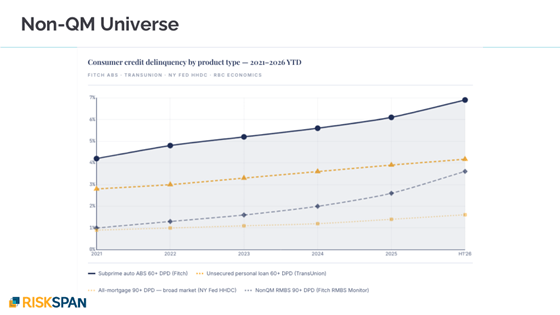
Consumer Credit Delinquency by Product Type
Against that backdrop, RiskSpan’s Non-QM Credit Model — CM 7.1 — has moved into production and is now available to all clients. It runs four independent transition models by documentation type (Bank Statement, DSCR, Full Doc, Other), feeding into a single liquidation-timeline and severity model recalibrated to current Non-QM performance.
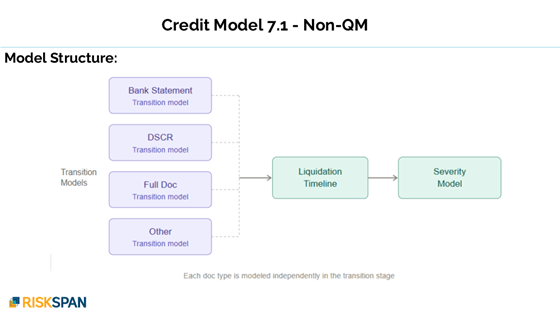
CM 7.1 Model Structure
Macroeconomic Update
The biggest change this month is at the Fed. A couple of months ago the market was pricing in up to two rate cuts this year; CME FedWatch data now show meaningful odds of a hike instead, with the Fed funds rate seen moving from 350–375 bps toward 375–400 bps by year-end.
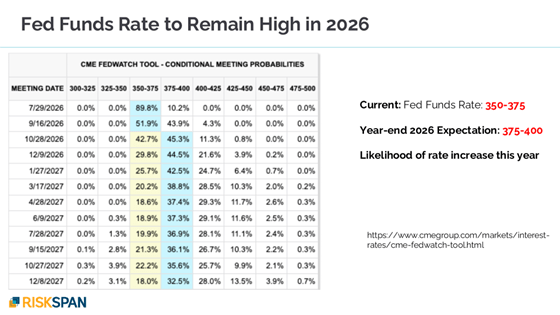
Fed Funds Rate to Remain High in 2026
Longer rates have followed suit. The 10-year Treasury, just above 4.5%, is expected to climb another 20–25 bps toward ~4.9% before easing — but to hold above 4% for a couple of years. Mortgage rates, currently around 6.5–6.6%, are expected to reach as high as ~6.9% by spring 2027 and stay above 6.5% for the next two to three years.
The labor market sent a mixed signal. June payrolls rose just 57K, roughly half of what was expected, and April/May were revised down a combined 75,000 jobs — pointing to real underlying softness. Headline unemployment actually ticked down to 4.2%, but that came from falling labor force participation (61.5%, the lowest since 2021) rather than hiring; the household survey showed 507,000 fewer people employed. On a brighter note, CPI eased to 3.5% year-over-year and wage growth matched it exactly — the first time in 12–18 months that real wage growth hasn’t been negative.
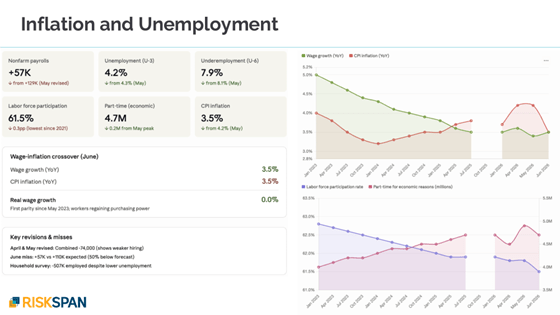
Inflation and Unemployment

We continue to add additional analytics reports on the RiskSpan Platform. Please visit www.riskspan.com to request access.
As always, please feel free to contact us to discuss or learn more.
Arlington, VA – June 25, 2026 – RiskSpan, a leading provider of data, modeling and analytics solutions for loan and structured finance investors, announced their collaboration with LSEG (London Stock Exchange Group) to deliver next-generation data and pricing across structured finance and related asset classes.
Across the broader LSEG ecosystem, RiskSpan powers mission-critical valuation operations by processing reference data workflows for more than 165,000 CUSIPs daily. Leveraging RiskSpan’s platform along with its reference data extraction and normalisation capabilities, LSEG also delivers daily evaluated pricing for structured products, supporting approximately 100,000 CUSIPs.
Bernadette Kogler, CEO of RiskSpan, said: “Our collaboration provides great value to clients. LSEG brings world-class evaluated pricing, reference and derived data strategy, and global market distribution. RiskSpan enhances those capabilities with structured finance analytics and modeling, scalable data engineering, and rigorous validation and workflow tooling. Together, we are raising the standard for how structured products are priced, validated, and delivered to the market.”
Todd Hartmann, LSEG Group Head of Data & Feeds, said: “This collaboration with RiskSpan strengthens our structured finance pricing capabilities and reinforces our commitment to delivering high-quality, transparent data and analytics to the market. By combining our skillsets, we are enhancing the scalability and consistency of pricing across complex asset classes.”
This reflects a shared commitment to delivering reliable, scalable infrastructure that supports the evolving needs of the structured finance market, including mortgage-backed securities, asset-backed securities, and hard-to-value instruments.
About RiskSpan
RiskSpan delivers a single analytics solution for loan and structured finance (public and private) credit investors of any size – to make faster, more precise trading and portfolio management decisions and meet reporting requirements without manual work, multiple vendors and internal solutions.
RiskSpan’s contributions span the full lifecycle of structured finance pricing and data operations, including advanced cash flow and valuation models, automated data pipelines, quality controls, and reconciliation frameworks designed to meet the demands of institutional investors, dealers, and risk managers.
Learn more at www.riskspan.com.
For media inquiries, please contact:
Samantha Wilcox
sawilcox@riskspan.com
425-652-6700
Register here for next month’s call: Thursday, July 16th 2026, 1 p.m. ET.
Key Takeaways
- Prepayment model continues to perform well; discount coupon speeds (WAC 5.5 and below) remain stable across Fannie/Freddie and GNMA, driven by housing turnover
- Premium coupon speeds (WAC 6.0+) declined as elevated rates reduced refi incentive; UPB rising steeply on new gross issuance of low-seasoning loans
- FN/FH S-curve has flattened materially from April to June; GNMA saw similar compression but at tighter intervals and with less magnitude
- Non-QM prepay speeds declined across all doc types in May remits; Non-QM DQ60+ rates ticked down marginally
- Non-QM Credit Model CM 7.1 in beta; available July 15; dedicated webinar coming before release
- Fed held rates at June 17–18 meeting; year-end expectation shifted to 375–400 bps; meaningful probability of a hike as early as September; dot plot revised to 3.8% for 2026
- Mortgage rates near 6.5%, back to summer 2025 levels; 6% viewed as 2026 floor; 10-yr TSY expected above 4% for years
- CPI at 3.8% YoY, real wage growth -0.4% (first negative since 2022); U-6 underemployment at 8.1%
- Home prices near-flat nationally (+0.67% YoY); inventory-constrained, not demand-driven; significant geographic divergence
You can read the recap below or click here for the entire recording.
Prepayment Model Back-Testing: June Factor Data Update
The prepayment model continues to track realized speeds closely across Agency collateral (results available in Edge under Vertex). The June factor data captures May remittances.
Fannie/Freddie — Discount Coupons (WAC 5.5 and Below)
Model CPR closely tracks observed CPR, confirming the model is well-calibrated in the turnover regime. With minimal refi incentive at current rate levels, prepayment activity is driven almost entirely by housing turnover, which has held steady.

Figure 1: FN/FH Discount Coupon Back-Testing — Model CPR vs. Observed CPR
Fannie/Freddie — Premium Coupons (WAC 6.0 and Higher) and S-Curve
Premium speeds declined due to elevated mortgage rates and fewer day counts in May vs. April. UPB is also rising steeply, reflecting gross issuance of newly originated loans with limited seasoning that further dampens prepay. The S-curve flattening tells the fuller story: comparing April, May, and June factor months, the curve has collapsed from the April peak (green), with borrowers responding progressively less to the same level of refi incentive.

Figure 2: FN/FH Premium Coupon Back-Testing — Model CPR vs. Observed CPR

Figure 3: FN/FH S-Curve Flattening — April, May, and June Factor Months
GNMA — Discount and Premium Coupons
GNMA discount speeds remain supported by turnover. Premium speeds are declining but proved more resilient than conventional — approximately 14% reduction vs. 24% for Fannie/Freddie. The GNMA S-curve is compressing, but at tighter intervals than the more pronounced slope collapse seen in conventional.

Figure 4: GN/G2 Discount and Premium Coupon Back-Testing — Model CPR vs. Observed CPR
Non-QM Historical Performance
Based on Cotality data through the Edge platform’s historical performance module, capturing the June factor date (May remittances).
Prepayment Speeds
Speeds declined across all three major doc types reflecting the rate environment: bank statement 29→22 CPR, DSCR 21→16 CPR, full doc 17→16 CPR. Full doc loans carry a lower WAC (~5.1% vs. 6.9–7.1% for bank statement and DSCR) and are more locked in, though they show a steeper S-curve response when refi incentive is held constant. Many DSCR loans remain within prepayment penalty terms, though 2023 originations with three-year terms are now beginning to exit that window, which could lift speeds going forward.

Figure 5: Non-QM CPR by Documentation Type (July 2023–June 2026)
Delinquencies
DQ60+ rates ticked down marginally in May remits: bank statement ~4%, DSCR ~3%, full doc ~0.72%. A wide gap persists across doc types even after controlling for FICO and LTV. The 2023 vintage remains the highest-delinquency cohort, driven by somewhat looser underwriting and a credit burnout effect — stronger borrowers in that high-WAC vintage have already paid down or refinanced, leaving a residual pool more likely to be credit-impaired.

Figure 6: Non-QM DQ60+ by Documentation Type (July 2023–June 2026)

Figure 7: Non-QM DQ60+ by Vintage and Loan Age
Non-QM Credit Model: CM 7.1 Update
CM 7.1 is in beta testing and will be generally available on July 15, 2026. A dedicated webinar is planned before the production release. The model uses a three-stage architecture with four independently estimated transition models (Bank Statement, DSCR, Full Doc, Other) feeding a unified liquidation timeline and severity model — capturing the meaningfully different performance characteristics across Non-QM documentation types seen in the historical data above.

Figure 8: CM 7.1 Model Structure
Macroeconomic Update: June 2026
Federal Reserve — On Hold, With a Hike Now on the Table
The Fed held rates at its June 17–18 meeting (350–375 bps). The big shift is in forward expectations: comparing CME FedWatch probabilities from May 20 to June 17, the likelihood of a rate hike has risen materially, with a meaningful probability of an increase as early as September. Year-end 2026 market expectation has shifted from 350–375 to 375–400 bps. The Fed’s own June dot plot revised the 2026 median funds rate to 3.8%, up from 3.4% in March, as inflation surprised to the upside and strong payrolls data reduce pressure to ease.

Figure 9: CME FedWatch Conditional Probabilities (May 20 vs. June 17) and Fed Dot Plot
Rates, Inflation, and Home Prices
Treasury and mortgage rates: The 10-year TSY consensus forecast peaks near 4.6% by year-end 2026 and stays above 4% for the next several years. Mortgage rates have been notably volatile since late February, climbing from ~6% back to ~6.5% as of mid-June. The team views 6% as the effective 2026 floor.
Inflation and labor: CPI at 3.8% YoY vs. wage growth of 3.4% produces real wage growth of -0.4% — the first negative year since 2022. U-3 unemployment is 4.3%; U-6 underemployment is 8.1%. Labor force participation is at its lowest since 2021. May payrolls came in at 172K vs. 80K expected but gains were concentrated in leisure/hospitality and local government. The Fed’s June projections raised 2026 PCE inflation to 3.6% (from 2.7% in March).
Home prices: Case-Shiller National at +0.67% YoY (March 2026); 20-City Composite at +0.83%. Gains appear to be inventory-constrained rather than demand-driven. Geographic divergence is significant — some MSAs are in negative territory, which is a relevant risk factor for Non-QM collateral concentration.

Figure 10: 10-Year Treasury Consensus Forecast and Mortgage Rate Trend

Figure 11: Inflation, Wage Growth, and Labor Market Dashboard

Figure 12: Case-Shiller National and 20-City Composite Home Price Indices
Summary
| Topic | Key Takeaway |
| Prepayment Model | Performing well; discount speeds stable (turnover-driven); premium speeds declined on elevated rates and fewer May day counts; UPB rising steeply on new gross issuance |
| FN/FH S-Curve | Materially flatter from April to June; borrowers responding less to refi incentive; newer vintages pulling down aggregate |
| GNMA Performance | Discount speeds stable; premium speeds down but more resilient than conventional (14% reduction vs. 24% for FN/FH); S-curve compression at tighter intervals |
| Non-QM Prepay | Bank statement 29→22 CPR; DSCR 21→16 CPR; Full doc 17→16 CPR; rate-driven; DSCR partly shielded by prepay penalty terms |
| Non-QM DQ | DQ60+ ticked down marginally: bank statement ~4%, DSCR ~3%, full doc ~0.72%; 2023 vintage remains highest-DQ cohort (loose underwriting + credit burnout) |
| CM 7.1 Credit Model | Beta testing now; available July 15; dedicated webinar before release; four doc-type transition models feeding unified liquidation and severity model |
| Fed Policy | Held at 350–375 bps (June 17–18 meeting); year-end expectation shifted to 375–400; hike possible as early as September; dot plot revised to 3.8% median for 2026 vs. 3.4% in March |
| Rates | 10-yr TSY consensus peaks ~4.6% year-end, stays above 4% for years; mortgage rates ~6.5%, back to summer 2025 levels; 6% viewed as 2026 floor |
| Inflation & Labor | CPI 3.8% YoY; wage growth 3.4%; real wages -0.4% (first negative since 2022); U-3 4.3%, U-6 8.1%; May payrolls 172K vs. 80K expected |
| Home Prices | Case-Shiller National +0.67% YoY (March 2026); gains inventory-driven, not demand-driven; significant geographic variation with some MSAs negative |
We continue to add additional analytics reports on the RiskSpan Platform. Please visit www.riskspan.com/request-access to request free access.
As always, please feel free to contact us to discuss or learn more.
Register here for next month’s call: Thursday, June 18th 2026, 1 p.m. ET.
Key Takeaways
- Prepayment models continue to perform well; April discount coupon speeds remain stable, driven primarily by housing turnover
- Premium coupon speeds fell sharply in May factor data as the March mortgage rate sell-off reduced refinancing incentive and flattened the S-curve
- GNMA premium coupons showed a moderate speed decline but proved more resilient than conventional counterparts
- Non-QM Credit Model CM 7.1 enters beta testing in June and is targeted for production release around July 10th; a dedicated webinar is planned for the second half of June
- No Federal Reserve rate cuts are expected in 2026; CME FedWatch now shows a meaningful probability of a rate hike later this year or in early 2027
- Mortgage rates have climbed back to levels last seen in summer 2025, with the Freddie Mac survey rate at 6.51% and Mortgage News Daily at 6.65%
- The 10-year Treasury rose approximately 50 basis points since February; market consensus expects it to reach ~4.8% by year-end and remain above 4% for the next 2–3 years
- CPI inflation rose to 3.8% year-over-year in April; core CPI at 2.8% — both well above the Fed’s 2% target
- Home prices stagnating nationally (~0.67% YoY per Case-Shiller); San Francisco has turned negative while New York continues to grow at ~4.8%
- Consumer stress deepens: low- and middle-income households carry credit card debt roughly 3x their monthly spending at ~23% APR; buy now, pay later obligations add further hidden risk not captured in credit bureau data
You can read the recap below or click here for the entire recording.
Prepayment Model Back-Testing: May Factor Data Update
The prepayment model continues to track realized speeds closely across Agency collateral. Results are available on the Edge platform under the Vertex module.
Fannie/Freddie — Discount Coupons (WAC 5.5 and Below)
April speeds for Fannie/Freddie discount coupons remained relatively stable. Because these lower-coupon loans carry little to no refinancing incentive, prepayment activity is driven almost entirely by housing turnover, which has held steady.

Figure 1: FN/FH Discount Coupon Back-Testing — Model CPR vs. Observed CPR
Fannie/Freddie — Premium Coupons (WAC 6.0 and Higher)
Premium coupon speeds fell sharply in the May factor data, reflecting the March mortgage rate sell-off. Rising rates reduced refinancing incentive and caused a notable flattening of the S-curve. The May S-curve sits meaningfully below both the April curve and the long-run historical average (January 2014–May 2026), with the gap widening at higher incentive levels. A diminishing media effect in the May cohort contributed to the flatter shape.

Figure 2: FN/FH Premium Coupon Back-Testing — Model CPR vs. Observed CPR

Figure 3: EDGE Historical Performance — FN/FH S-Curve (Refi Incentive vs. CPR)
GNMA — Discount and Premium Coupons
GNMA collateral showed a similar pattern. Discount coupon speeds remained supported by turnover activity, while premium coupon speeds saw a moderate decline consistent with the higher-rate environment. Notably, GNMA premiums proved more resilient than their conventional counterparts when compared against the conventional S-curve, reflecting structural differences in the GNMA borrower population.

Figure 4: GN/G2 Discount and Premium Coupon Back-Testing — Model CPR vs. Observed CPR
Non-QM Credit Model: CM 7.1 Update
CM 7.1, RiskSpan’s new Non-QM Credit Model, is on track to enter beta testing in June with a targeted production release around July 10, 2026. A detailed webinar covering the model will be held in the second half of June.
Model Structure
CM 7.1 uses the same three-stage architecture as RiskSpan’s agency credit model:
- Transition Models (four, one per documentation type) — each independently estimated
- Bank Statement
- DSCR
- Full Doc
- Other
- Liquidation Timeline Model — applied once a loan enters default
- Severity Model — estimates final losses on the defaulted balance
Each documentation type is modeled independently at the transition stage, then fed into a unified liquidation timeline and severity model. This segmentation reflects meaningfully different performance characteristics across Non-QM documentation types.

Figure 5: CM 7.1 Model Structure — Four Transition Models Feed into Unified Liquidation and Severity Models
Macroeconomic Update: May 2026
Federal Reserve — No Rate Cuts Expected; Hike Risk Emerging
The Fed funds rate remains at 350–375 bps. CME FedWatch futures indicate it is highly unlikely to be cut in 2026. More notably, the conditional probabilities have shifted over the past 4–6 weeks to reflect a meaningful likelihood of a rate hike in the latter part of 2026 or early 2027. With persistent inflation and a new Fed chair, the market sees little room for easing.

Figure 6: Federal Funds Target Range — Upper Limit (Source: FRED) and CME FedWatch Conditional Probabilities
Treasury Yield Curve — Significantly Higher Than February
The Treasury yield curve has shifted materially upward since the February 2026 trough, when the 10-year yield was at its lowest recent level and mortgage rates briefly approached 6%. Since then:
- The 10-year and 30-year Treasuries rose approximately 50 basis points
- The 2-year Treasury rose approximately 75–80 basis points
- As of May 21, the 10-year Treasury stood at approximately 4.60%
This move is attributed to geopolitical dynamics (including the situation around Iran) and a declining global appetite for U.S. Treasuries, with recent auctions clearing at progressively higher yields. Market consensus projects the 10-year to reach approximately 4.8% by December 2026 and to remain above 4% for the next 2–3 years.

Figure 7: Treasury Yield Curves — January through May 2026
Mortgage Rates — Back to Summer 2025 Levels
Mortgage rates have given back much of the progress made earlier in the year. As of the call date, the Freddie Mac primary survey rate was 6.51% and the Mortgage News Daily rate was 6.65% — levels last seen in August 2025. The expectation is that mortgage rates will remain at or above 6.25% for the foreseeable future, with a sub-6% rate considered unlikely in the near term.

Figure 8: 10-Year Treasury Yield Forecast and Primary Mortgage Rate Trend (Mortgage News Daily, MBA, Freddie Mac)
Inflation — Staying Elevated
The April 2026 CPI print came in at 3.8% year-over-year; core CPI (excluding food and energy) ran at 2.8%, well above the Fed’s 2% target. The PCE index was not yet published at call time but was expected to confirm continued inflationary pressure. Combined with stable unemployment, this leaves the Fed with limited flexibility to ease.
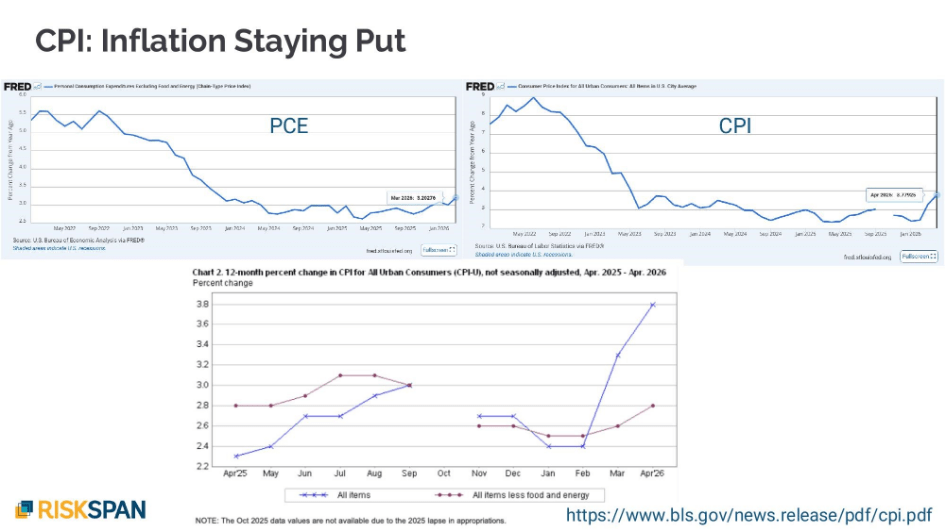
Figure 9: PCE Inflation (ex. Food & Energy) and CPI — Year-over-Year % Change
Home Prices — Stagnating, with Pronounced Regional Variation
National home price growth has slowed to near-zero. The Case-Shiller National Index showed approximately +0.67% year-over-year as of February 2026, while the 10-City Composite came in at +1.74%, suggesting urban markets are modestly outperforming. Regional divergence is pronounced: San Francisco has recorded negative price growth for approximately the past six months (-0.34% YoY), while New York remains solidly positive at +4.78%.
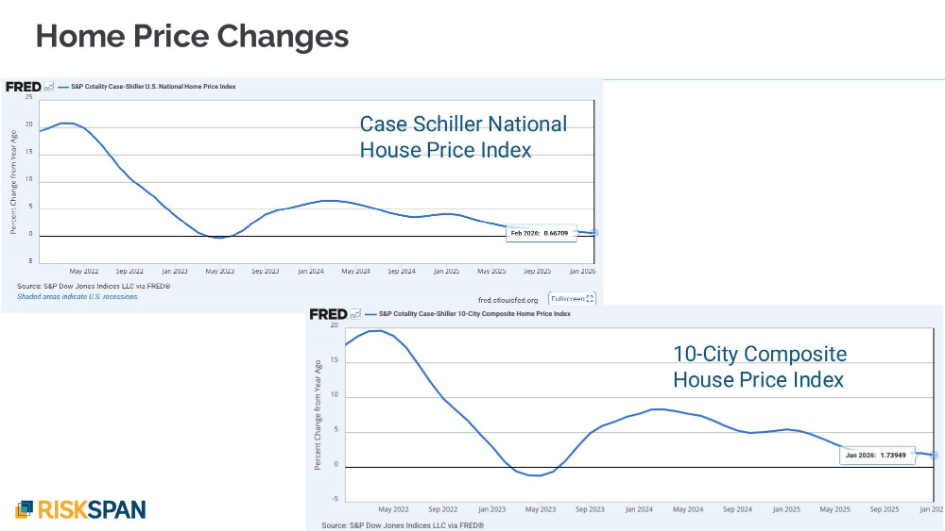
Figure 10: Case-Shiller National and 10-City Composite Home Price Indices — Year-over-Year % Change

Figure 11: Case-Shiller San Francisco and New York Home Price Indices — Year-over-Year % Change
Consumer Stress: Evidence from Credit Card Spending
This month’s call featured a deep dive into consumer financial stress, drawing on research from the Federal Reserve Bank of Boston. The analysis is particularly relevant to mortgage credit risk given evidence of rising delinquencies in FHA and Non-QM collateral.
Credit Landscape
Agency loans (excluding FHA) continue to show low delinquency rates with no significant deterioration. FHA, however, is exhibiting elevated delinquencies that remain high even after accounting for the trial modification policy introduced in October 2025, which holds more loans in delinquent states during the modification process. The Non-QM universe has also begun to show a rising delinquency trend over the past 12–18 months.
Boston Fed Analysis: Spending and Debt by Income Group
A study from the Federal Reserve Bank of Boston segments credit card behavior across three income cohorts and reveals a striking disparity between spending levels and outstanding balances:
- Low-income ($0–$39K): monthly spending ~$25B vs. revolving debt ~$80B — a 3x ratio; this group is primarily revolving rather than paying off balances
- Middle-income ($59K–$83K): spending ~$37B vs. debt ~$105B — also approximately a 3x ratio
- High-income ($121K+): spending ~$170B vs. debt ~$185B — roughly 1:1, consistent with transactor behavior (spend and pay off monthly)
Low- and middle-income households are therefore carrying roughly three months’ worth of spending as permanent revolving debt, at credit card APRs recently running around 23% on new issuances. Total credit card outstanding nationally has reached approximately $1.25 trillion.

Figure 12: Aggregate Credit Card Spending by Income Group, January 2015–May 2025 (Source: Boston Fed / Federal Reserve Y-14M)

Figure 13: Aggregate Credit Card Debt by Income Group, January 2015–April 2025 (Source: Boston Fed / Federal Reserve Y-14M)
Buy Now, Pay Later: An Untracked Risk
Buy now, pay later (BNPL) services have grown rapidly and appear to be used disproportionately by lower-income households. Because BNPL obligations are not reported to credit bureaus, they represent an invisible liability not reflected in standard debt figures. The team flagged this as a developing risk to monitor, particularly for its potential impact on borrower liquidity and mortgage performance in the FHA universe.
Summary
| Topic | Key Takeaway |
| Prepayment Model | Performing well overall; April discount speeds stable (turnover-driven); May premium speeds fell sharply on March rate sell-off and S-curve flattening |
| GNMA Performance | Discount speeds supported by turnover; premium speeds declined moderately but more resilient than conventional counterparts |
| Non-QM Credit Model | CM 7.1 beta in June; production release ~July 10; dedicated webinar in second half of June |
| Mortgage Rates | Freddie Mac at 6.51%; Mortgage News Daily at 6.65%; back to summer 2025 levels; sub-6.25% rate unlikely near-term |
| Fed Policy | No cuts expected in 2026; CME FedWatch shows meaningful probability of hike later in 2026 or early 2027 |
| Treasury Yields | 10-year up ~50 bps since February; 2-year up ~75–80 bps; consensus at ~4.82% by year-end |
| Inflation | CPI 3.8% YoY (April); core CPI 2.8%; PCE similarly elevated; well above 2% target |
| Home Prices | National ~+0.67% YoY; San Francisco negative; New York +4.78%; highly geography-dependent |
| Consumer Stress | Low/mid-income households revolving 3x monthly spending at ~23% APR; BNPL obligations add hidden risk; FHA and Non-QM delinquencies trending higher |
We continue to add additional analytics reports on the RiskSpan Platform. Please visit www.riskspan.com/request-access to request free access.
As always, please feel free to contact us to discuss or learn more.
Register here for next month’s call: Thursday, May 21st, 2026, 1 p.m. ET.
Key Takeaways
- Prepayment models continue to perform well, with March speeds driven by a February rate rally and day count effects
- A new Non-QM Credit Model (CM 7.1) is on track for release near end of Q2 2026, with a dedicated webinar planned for end of May or early June
- Housing turnover analysis reveals rate sensitivity at positive refinancing incentive levels — a finding that will inform the next prepayment model
- Mortgage rates hit a six-month high in March before pulling back; rates are expected to remain above 6% through 2026 and 2027
- No Federal Reserve rate cuts are expected in 2026; the consumer remains under pressure from elevated rates and rising credit card balances
You can read the recap below or click here for the entire recording.
Prepayment Model Back-Testing: April Factor Data Update
The prepayment model continues to track realized speeds closely across Agency collateral. Results are available on the Edge platform under the Vertex module.
Fannie/Freddie — Discount Coupons (WAC 5.5 and Below)
Discount coupons showed a modest uptick in March speeds, driven primarily by two factors:
- A day count effect: March had three more collection days than February
- Seasonal turnover patterns typical of the spring housing market

Figure 1: FN/FH Discount Coupon Back-Testing — Model CPR vs. Observed CPR
Fannie/Freddie — Premium Coupons (WAC 6.0 and Higher)
Premium coupons saw a sharper increase in prepayment speeds in March, driven primarily by the rates rally in February. With rates subsequently moving higher in March, May factor data is expected to show a decline in speeds — a clear convex response consistent with model expectations.

Figure 2: FN/FH Premium Coupon Back-Testing — Model CPR vs. Observed CPR
GNMA — FHA and VA Segmentation
GNMA performance showed a similar pattern to Fannie/Freddie across discount and premium coupons. A notable enhancement this month: the team has introduced the ability to split GNMA back-testing results by FHA vs. VA segments on the Vertex report, providing additional analytical granularity.
Two segment-level observations:
- FHA: FHA: The model has shown a slight drift in prepayment speeds over the past year. This is primarily attributed to the FHA trial modification policy change in 2025, under which servicers are no longer required to buy out delinquent loans — a policy shift that has meaningfully reduced prepayment speeds relative to historical levels.
- VA: VA: A discrepancy between modeled and actual speeds reflects the default VA-to-PMMS spread assumption being too tight. Users can adjust the VA spread to current market levels within the platform to bring results into closer alignment with observed speeds.

Figure 3: FHA Segment Back-Testing

Figure 4: VA Segment Back-Testing
New Non-QM Credit Model: CM 7.1
Guanlin Chen from the Quantitative Modeling Group presented an overview of the upcoming Non-QM Credit Model, version 7.1, expected to be available to all users near end of Q2 2026.
Model Structure
CM 7.1 follows the same three-component framework as RiskSpan’s agency credit model:
- 1. Transition Model — generates a time-varying transition matrix estimating transition probabilities across delinquency states and time periods
- 2. Liquidation Timeline Model — applied once a loan enters default
- 3. Severity Model — estimates final losses on the defaulted balance
A key design decision: the model is built with separate sub-models for each documentation type, consistent with the segmentation used in the Non-QM prepayment model: Bank Statement, DSCR, Full Doc, and Other. This segmentation reflects the meaningfully different performance characteristics across these loan types and allows for more accurate, documentation-specific projections.
Transition Matrix Design
The transition matrix tracks loans across delinquency states — current (0), one-month delinquent (1), two-month delinquent (2), foreclosure (F), and REO (R) — with additional granularity for delinquency history.
Back-Testing Results
Initial back-testing of the 30-day delinquency transition demonstrates that the model captures the overall trend in Non-QM credit performance well across all four documentation types. The COVID period was intentionally excluded from model training — including it would have caused extreme unemployment levels to dominate the model and distort sensitivity to other risk factors.

Figure 5: NonQM Credit Model — Current to 30DPD Transition: Actual vs. Projection by Documentation Type
A dedicated webinar covering CM 7.1 in detail is planned for end of May or early June. Please stay tuned.
Housing Turnover Analysis: Rate Sensitivity at Positive Refinancing Incentive
Shane Lee from the Quantitative Modeling team presented new research on housing turnover behavior in a positive refinancing incentive environment.
Background
Total prepayment has two components: housing turnover (prepayment driven by home sales) and refinancing. In current model design, housing turnover is assumed to be weakly rate sensitive — and in the positive refinancing incentive regime, sensitivity is held at zero. The question the team set out to answer: is that assumption correct?
Data Sources
- NAR: National Association of Realtors (NAR) Existing Home Sales — measures the number of homes sold including single-family, condo, and co-op properties (including sales without mortgages)
- Equifax ADS: Equifax ADS Data — tracks trade lines per consumer, allowing the team to identify housing turnover by flagging cases where an existing mortgage closes and a new mortgage originates at a different ZIP code for the same borrower

Figure 6: ADS vs. NAR Data Comparison — Prepaid Mortgages vs. Home Sale Units
Key Finding
During the post-COVID refinancing boom, housing turnover activity increased significantly — by almost 50% above the baseline level. This elevated turnover coincided with the period of low rates and high refinancing activity, driven in part by the work-from-home migration wave.

Figure 7: Housing Turnover CPR — ADS Data (nearly 50% above baseline during COVID refi boom)
This finding suggests that housing turnover is more rate-sensitive in a positive refinancing incentive environment than current models assume — a potential source of underestimation when projecting prepayment speeds in a low-rate environment. Research is underway to incorporate this into Prepayment 4.0.
Macroeconomic Update: April 2026
Federal Reserve — No Rate Cuts Expected in 2026
CME FedWatch futures currently indicate no Federal Reserve rate cuts this year. The overall expectation is that the Fed funds rate (currently 350–375 bps) will remain unchanged through year-end 2026.

Figure 8: Federal Funds Target Range — Upper Limit (Source: FRED)
Mortgage Rates — Elevated and Volatile
Mortgage rates hit a six-month high in March, with Freddie Mac’s primary rate reaching 6.45% and Mortgage News Daily data showing rates approaching 6.64%. Rates have since pulled back modestly as some geopolitical uncertainty subsided. The 10-year Treasury rate is expected by market consensus (econforecasting.com) to remain above 4% for the next three to five years — implying mortgage rates are unlikely to fall significantly below 6%.

Figure 9: 10-Year Treasury Yield — Historical and Market Consensus Forecast

Figure 10: Primary Mortgage Rate Trend
Unemployment and Inflation
- March unemployment rate: 4.3% — trending upward
- PCE (excluding food and energy): approximately 3% — still above the Fed’s 2% target

Figure 11: Unemployment Rate

Figure 12: PCE Inflation (ex. Food & Energy)
Consumers continue to face pressure from elevated gasoline and oil prices. Credit card balances have risen significantly over the past two years, adding to the financial strain on households.
Home Prices — Stabilizing but Elevated
Home price growth remains positive but has decelerated substantially from the 20%+ year-over-year peaks observed in mid-2022:
- Case-Shiller National Index: approximately 1% year-over-year growth
- 10-City Composite: slightly above the national index
- FHFA All-Transaction Index: somewhat stronger, indicating variation across market segments

Figure 13: Case-Shiller U.S. National Home Price Index — Year-over-Year % Change
Two regional case studies highlight the range of outcomes: Austin, TX and Boise, ID both experienced peak growth of 30–35% in 2021–2022, followed by sharp declines through 2023, and are now returning to modest positive territory. Housing supply remains severely constrained.
Summary
| Topic | Key Takeaway |
| Prepayment Model | Performing well overall; March speeds driven by February rate rally and day count effects |
| GNMA Segmentation | New FHA/VA split available in Vertex; FHA drift tied to 2025 trial mod policy change |
| NonQM Credit Model | CM 7.1 on track for end of Q2 2026; dedicated webinar coming end of May / early June |
| Housing Turnover | Rate sensitivity confirmed in positive refi regime; ~50% above baseline during low-rate period; research underway for Prepayment 4.0 |
| Mortgage Rates | Hit six-month high of 6.64% in March; expected to remain above 6% through 2026–27 |
| Fed Policy | No rate cuts expected in 2026; Fed funds rate at 350–375 bps |
| Home Prices | Growth slowing (~1% nationally); supply constraints persist |
We continue to add additional analytics reports on the Platform. Please visit www.riskspan.com/request-access to request free access.
As always, please feel free to contact us to discuss or learn more.
Register here for next month’s call: Thursday, April 16th, 2026, 1 p.m. ET.
Key takeaways from this month’s call:
- Non-mortgage credit is deteriorating more rapidly than mortgage credit
- BNPL usage may be masking underlying financial strain
- Macroeconomic conditions are likely to remain restrictive, reinforcing current trends
- Prepayment models remain well-calibrated, even as borrower behavior begins to shift
You can read the recap below or click here for the entire 20-minute recording.
Credit Performance by Asset Class
The data shows a clear divergence between mortgage and non-mortgage credit:
- Mortgage delinquencies remain relatively low, supported by tighter underwriting standards
- Credit card delinquencies have increased meaningfully since 2022
- Auto loan delinquencies are approaching levels observed during the Global Financial Crisis, particularly among younger borrowers
The following charts from NYFed illustrate how younger age cohorts are consistently exhibiting higher delinquency rates across credit types (mortgages, credit cards, and autos).


BNPL Usage as a Potential Blind Spot
Buy Now, Pay Later (BNPL) usage continues to expand.

Adoption is highest among younger borrowers.

A meaningful portion of usage is for essential expenses such as groceries
Because BNPL obligations are not consistently captured in traditional credit metrics, they may obscure underlying levels of consumer leverage and stress.

Macroeconomic Outlook: Rates Expected to Remain Elevated
The macroeconomic environment continues to support a “higher-for-longer” rate outlook.
- Market expectations suggest no Federal Reserve rate cuts through 2026.
- The 10-year Treasury rate is expected to remain above 4% over the next several years.
- Mortgage rates, after declining earlier in 2026, have risen again and are expected to remain near or above 6%.
At the same time:
- Inflation remains above target levels
- Unemployment is trending upward
These conditions suggest a continued tightening backdrop for borrowers, with limited relief from monetary policy in the near term.
Housing Market: Moderation Continues
Home price growth remains positive but has slowed:
- Case-Shiller index shows modest annual growth (~1.3%)
- FHFA index indicates somewhat stronger growth (~3.3%)
Differences between indices suggest variation across market segments, with relatively stronger performance in more affordable segments and geographic differences on home prices.
Prepayment Trends: Stable Performance with Emerging Shifts
Against this macro and consumer backdrop, prepayment behavior continues to evolve.
- Prepayment models remain closely aligned with realized speeds across FN/FH and GNMA collateral, as shown in the coupon-level comparisons.
- Refinance behavior is well captured, including sensitivity to changes in mortgage rates.
There are, however, early indications of shifting borrower behavior:
- Prepayment speeds increased in February despite fewer collection days, suggesting a gradual weakening of the mortgage rate “lock-in” effect.
- Short-term rate increases may moderate this trend, but the directional change is notable.
GNMA Segmentation Enhancements
The introduction of FHA and VA segmentation in GNMA back-testing provides additional analytical detail.
FHA performance shows some divergence, likely reflecting recent policy changes affecting delinquent loan buyouts.

VA results are more sensitive to spread assumptions and can be adjusted to align with market conditions.

We continue to add additional analytics reports on the Platform. Please visit www.riskspan.com/request-access to request free access.
As always, please feel free to contact us to discuss or learn more.
Register here for next month’s call: Thursday, March 19th, 2026, 1 p.m. ET.
In this month’s Models & Markets call, RiskSpan’s quantitative modeling team tackled:
- The record debt levels now carried by U.S. households (and the consumer stress that is building beneath the surface);
- The likely persistence of higher rates;
- RiskSpan’s forthcoming non-QM credit model, and;
- (as always) how RiskSpan’s prepayment model is performing
You can read the recap below or click here for the entire 20-minute recording.
$18 Trillion in Household Debt (and Growing)
U.S. household debt reached $18.8 trillion at the end of 2025 and continues to climb. Mortgages account for the largest share at roughly $13 trillion, with auto loans, student loans, credit cards, and HELOCs making up the balance.

Using conservative assumptions for average interest rates for each category, we estimate that these balances equate to roughly $1.1 trillion in annual interest payments and $2.5 trillion in total annual debt service payments – the approximate cost required each year just to keep households current.
A Distributional Problem
The aggregate debt figure masks meaningful stress at the lower end of the income spectrum:
- A median household (~$80K gross income) may devote roughly 37% of disposable income to debt service.
- Bottom-quartile households (~$32K gross income) may spend 40–55% of disposable income servicing debt.
Lower-income households are disproportionately exposed to higher-rate revolving credit and subprime auto loans, as opposed to 3–4% fixed-rate mortgages. The averages therefore understate the severity of strain on the more vulnerable segments.

Are Reported Delinquencies Understating Stress?
Delinquencies are rising across income levels, particularly in lower-income areas. Lenders, however, may be quietly modifying or re-aging loans, particularly in consumer credit categories (e.g., auto loans). Such modifications can:
- Push missed payments to the back of the loan
- Reset accounts to “current” status
- Avoid immediate charge-offs
While this suppresses reported delinquency statistics, borrower balances may continue to grow. This implies that reported delinquency rates may really be more of a floor, as aggregate DSCR and household stress may be greatly understated.
Consumer strain is real and potentially worse than what is suggested by the headline metrics.
Coming in Q2: RiskSpan’s Non-QM Credit Model!
RiskSpan’s forthcoming non-QM credit model will feature four distinct documentation categories:
- Bank Statement
- Full Documentation
- DSCR/Investor
- Other (e.g., VOE, asset depletion)
Each segment is modeled independently through a transition-matrix framework covering:
- Current
- 30-day DQ
- 60-day DQ
- 90+ DQ
- Termination (voluntary and involuntary)
Prior delinquency figures prominently in the model, with clean loans having relatively low base transition rates from current to delinquent, while loans with prior delinquency history can experience transition probabilities up to 10x higher. Capturing this conditional risk dynamic is central to the model’s design.
Back-testing (shown below for the Full Doc segment) indicates the model is tracking historical delinquency transition rates reasonably well, though development remains ongoing.

Macro Considerations
Consistent with prior months, the macro backdrop continues to reinforce a “higher-for-longer” rate environment.
Fed and Policy Outlook
- Fed Funds expectations imply limited cuts in 2026.
- No immediate expectation of a March rate cut.
10-Year Treasury
- Consensus forecasts suggest the 10-year Treasury will remain above 4% for the next 2–3 years.
- Recently, it has hovered around ~4.1%, down slightly from prior highs.
Mortgage Rates
Primary mortgage rates are approaching 6%, but not sustainably breaking below it. In our view, mortgage rates are likely to remain around or above 6% through 2026, possibly into 2027.
Labor, Inflation, and Home Prices
- Unemployment ticked down slightly.
- Job creation surprised to the upside.
- Inflation remains sticky in the 2.5–3% range
- National home prices showed modest year-over-year growth (~1.4%).
Traditional seasonal adjustments may be less reliable in today’s inventory-constrained housing market. Turnover seasonality appears to be shifting earlier in the year, with implications for both pricing and prepayment dynamics.
Prepayment Model Performance: Stable & Improving
Despite macro headwinds and rising consumer stress, RiskSpan’s prepayment models continue to perform well.
GSE Discounts (WAC 5.5 and Below)

Prepayments declined slightly in the most recent month, primarily due to fewer collection days and normal January seasonality (lower turnover). Overall model fit remains strong.
One identified refinement: the model’s seasonal peak appears slightly delayed (June/July shifting toward August). This will be addressed in the next version update
GSE Premiums (WAC 6 and Above)

Refinance speeds have been largely unchanged over the past two months. S-curve comparisons between December and January show no material differences once recount adjustments are made. A modest ~1.5 CPR change in recent data appears driven by turnover rather than refi activity.
Ginnie Mae: FHA vs. VA Enhancement
Performance across Ginnie segments remains solid, with recent prepayment dips again attributable to fewer collection days. However, we have observed divergence between FHA and VA: Modeled FHA speeds tend to be overestimated, while modeled VA speeds tend to be underestimated compared to recent historicals.
To address this, RiskSpan is adding a loan guarantor filter to the back-testing report, enabling FHA and VA splits (expected early March). This enhancement will improve transparency and precision in Ginnie performance analysis.
We continue to add additional analytics reports on the Platform. Please visit www.riskspan.com/request-access to request free access.
As always, please feel free to contact us to discuss or learn more.